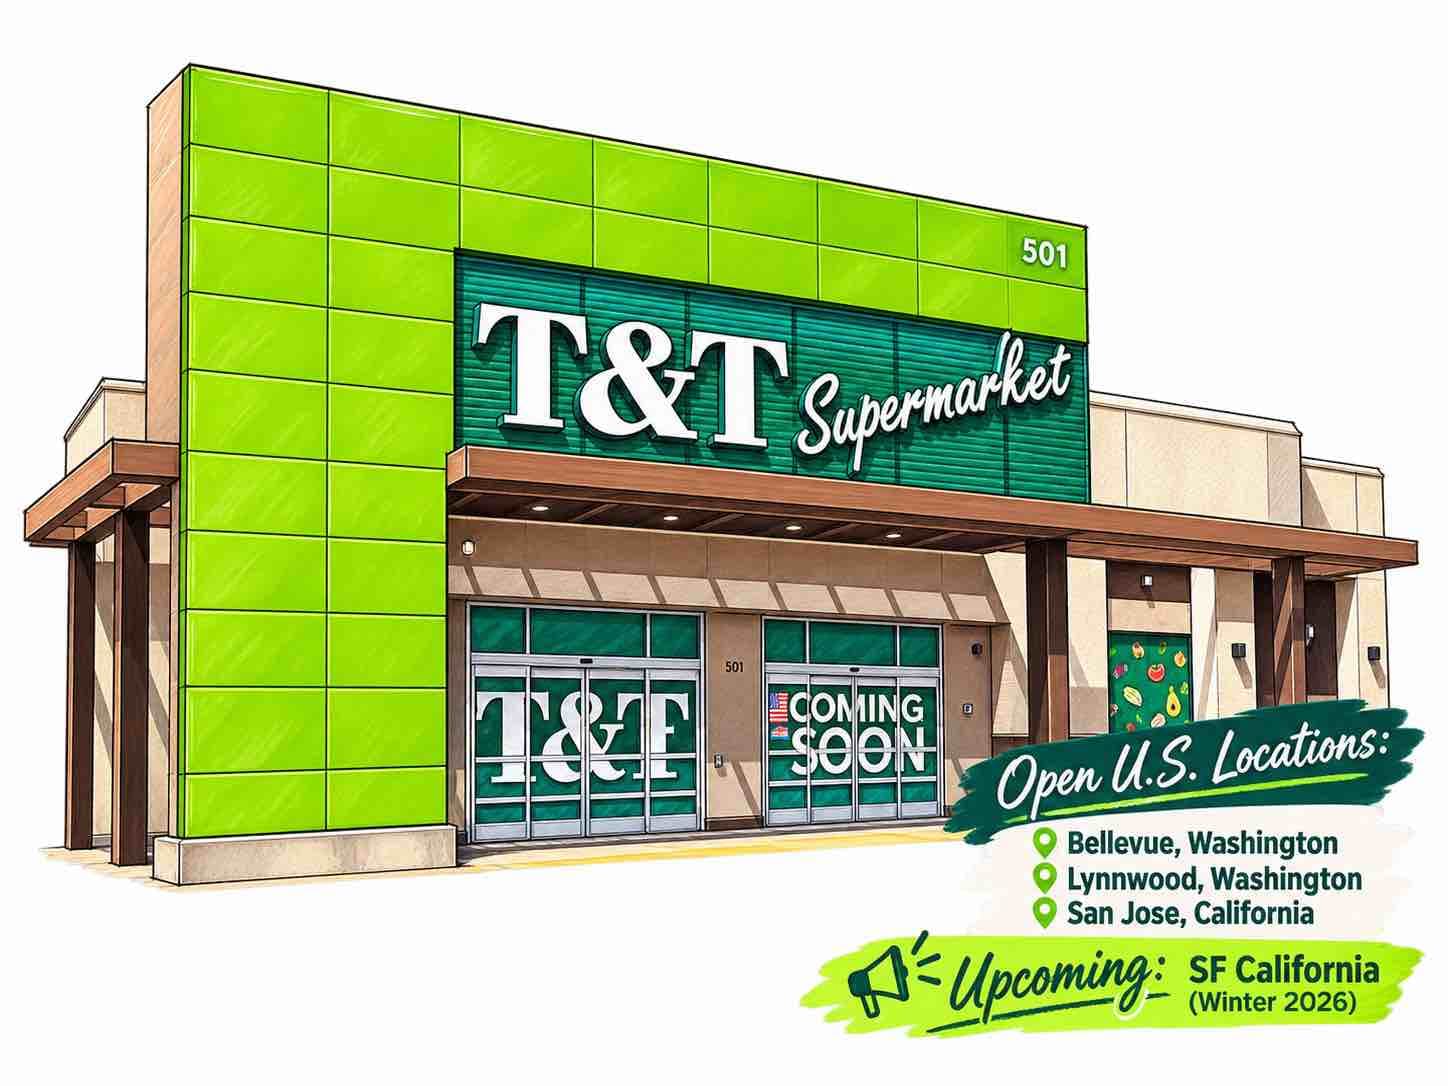
✨ Durable moat with US expansion upside - Rapid US expansion of T&T to major tech hubs (🌉SF upcoming in Winter 2026) - Incumbents that are extremely successful in Canada (picky consumers) fair very well in the US, see: $ATZ - UGC marketing to further spread the word is a great move as the products the store sell are inherently visual - No moat distruptions from discount grocers like LIDL at home 🇨🇦 compared to grocers in the US like $KR - Recession proof, inflation proof. Sits on land/in communities that prevents others incumbents from ever entering - Trading at the low end of its range since the stock split last year ($60-69)read more
Here’s my main thesis for $HNST: it’s a perfect small cap progressive build: solid foundation in balance sheet of over $100 million, no debt, solid earnings. Credit to my friends who use their products, so I was able to ‘One Up On Wall Street’ Peter Lynch style this stock. Unfortunately, I did catch this a hit too late after its monstrous run, 40% in one day! The stock over my predictions for the remainder of 2026 will bullishly hit $10.
I made some profit on $SHOP recently and bought $ATZ@145 cad avg price, and since then it has dropped to $130. Is it a good time to buy more? Drop your suggestions.
David Steinberg walks on stage Thursday asking Wall Street for a new label for Zeta Global. In July it traded at ~3x sales. The AI infrastructure club it compares itself to ($PLTR, $SNOW, $CRWD, $DDOG, $MDB) trades at 7-34x. I went through the receipts before the event. Full 11-minute video at the bottom of this post. Here's where things stand. The promise tracker so far: - Athena (promised Oct 2025): DELIVERED. Not usable on launch day, but live for everyone by March. Zeta says about 4 in 10 of its biggest customers use it now. - Palantir, promise 1 (move every data customer onto Palantir's system in about a month): DELIVERED, per Steinberg. - Palantir, promise 2 (land one joint customer that quarter): DELIVERED. They landed two. - Palantir's $100M/yr target: IN PROGRESS. Steinberg says it's "looking super low," but two customers isn't $100M yet. - OpenAI deal size: NOT DISCLOSED. Why Wall Street isn't fully buying it (all from Zeta's own paperwork): - The comparison chart grades Zeta with one ruler and the peers with another. It's disclosed in the footnotes, but it isn't apples to apples. - Stock-based comp was bigger than free cash flow last year. It's shrinking, and they buy back shares, but it isn't fixed. - The one that worries me: Zeta's own 2026 guidance has core growth (ex-Marigold, ex-political) slowing every quarter, from the high 20s to about 20%. The pitch says "price us like Palantir." The forecast says "we're slowing down." How I'm grading Thursday, announcement by announcement: - Is there a number? - Can customers use it that day? - Does it move anything outside marketing? Where I land: bullish, but I need to see more. The product's real, the partners are real, and the business is better than the price tag. A new label isn't something you announce. It's something the market gives you. Friday I post the Catalyst Check: every promise from the stage, graded. Full preview: https://youtu.be/U8lY6ZBeCLw I own shares. Not financial advice. $ZETA$PLTRread more
A marketing company just told Wall Street it's building its own chip. That's the headline grabbing attention. But the real story is AthenaOS. Zeta Live had four announcements total, and AthenaOS is the one actually aimed at Steinberg's $10B target Closest precedent: ServiceNow did a classic land-and-expand, starting in IT services, then into HR and customer service. Its market cap went from $15.2B to $106.5B in four years. AthenaOS has no customers yet, and rollout isn't until 2027. Want the full breakdown of all four announcements? Check out my newest video: https://youtu.be/Q-c8jlqEc5Y I own shares. Not financial advice.
Hi All! Costco is a company I’ve been wanting to hold as my main retail position because I believe in the business model so much. What’s your opinion on Costco? Currently a good buy? Off of the recent highs but is still and always seems to be expensive…
Dollar General reported second quarter earnings as follows: Net Sales Increased 5.2% to $11.3 Billion Same-Store Sales Increased 3.5% Operating Profit Increased 29.2% to $769.2 Million Diluted Earnings Per Share ("EPS") Increased 33.3% to $2.48 Year-to-Date Cash Flow From Operations of $1.5 Billion Board of Directors Declares Quarterly Cash Dividend of $0.59 per share For fiscal 2026, Dollar General raised guidance expecting net sales growth of 4.0% to 4.3%, same-store sales growth of 2.5% to 2.9%, and diluted EPS between $7.80 and $8.00. The stock is up almost 11% pre-market https://ca.finance.yahoo.com/news/dollar-general-corporation-reports-second-105000423.htmlread more
Dollar Tree has reported quarterly earnings: Revenue: $4.89 billion vs analyst estimates of $4.86 billion (7% year-on-year growth, 0.6% beat) EPS (GAAP): $2.70 vs analyst estimates of $1.16 (significant beat) The company reconfirmed its revenue guidance for the full year of $20.6 billion at the midpoint EPS (GAAP) guidance for Q3 CY2026 is $0.88 at the midpoint, missing analyst estimates by 36.2% Operating Margin: 14.1%, up from 4.9% in the same quarter last year Free Cash Flow Margin: 13.8%, up from 3.8% in the same quarter last year Same-Store Sales rose 3.7% year on year (6.5% in the same quarter last year) Market Capitalization: $25.4 billion The stock is down 4.5% pre-market https://finance.yahoo.com/markets/stocks/articles/dollar-tree-nasdaq-dltr-surprises-105609194.htmlread more
As the economy continues to evolve, investors are always in search of the next big opportunity in the stock market. Dollarama Inc. (TSX: DOL), a leading discount store chain in Canada, has shown resilience and growth potential in recent years. For stock market investors looking ahead to 2027, several factors could contribute to the rise of Dollarama’s share prices. You can read our latest article here at ERIOB2 now. #WeAreHereForYou (TSX: DOL) What Could Drive Dollarama Stock Prices Higher in 2026? (Update, Live) Url: https://eriofficialblog2.wordpress.com/2026/09/21/tsx-dol-what-could-drive-dollarama-stock-prices-higher-in-2026-update-live Enjoy. #EnRouteInvestors #ERIOB2 #Dollarama #ConsumerDemand #ExpansionPlans #ProductDiversification #BrandPrestige #EconomicDownturnResilience #ConsumerLoyalty #SustainabilityInitiatives #TechnologicalAdvancements #CustomerSatisfaction #Finance #International #Canada #GTA #GreaterTorontoArea #Vaughan #Ontarioread more
Had to trim $AMD. This does not mean I am not confident in the stock. Still 59% of my portfolio. My plan is to continue to trim as it approaches $1000. I do plan on holding a chunk of shares for the long-term regardless of what happens with the stock price.
Most people read SpaceX's spectrum deal as bad news for $ASTS. My read: it's worse news for the carriers, and that pushes them toward AST. AT&T and Verizon are already on board. The real question is T-Mobile, still tied to Starlink into 2027. Does the carriers' new joint venture end up bringing T-Mobile to AST's table? What's your read? Full teardown premieres today, 2 PM ET: https://youtube.com/@tickerteardown?si=7Tc1U47A3tB6G7fx
is no longer a safe reliable trading play imo. I have trimmed down my USD holdings and switching to other fiats and markets. Too risky for me, Sorry not sorry. I'd rather trust Carneys economic policies than Trump's🧐 not financial advice. just a rant.
I’m still bullish on $ATZ (Aritzia). 📈💕 I believe in the brand, its long-term growth potential, and its ability to continue expanding its presence in the fashion industry. Short-term price movements and market volatility are part of investing, but I’m focused on the bigger picture rather than just the daily fluctuations. Great companies don’t always move up in a straight line, and sometimes patience is part of the journey. Do your own research, understand the risks, and invest based on your own conviction. I’m sharing my perspective, not financial advice. 💎🙌 #ATZ #Aritzia #LongTermInvesting #StockMarket
Ugly... the only fair thing to say about the recent performance of Lululemon. I started buying Lululemon shares in June 2025, with the bulk of my position being built from November 2025 to June 2026 with my largest purchases being around $118 (interestingly also where lulu was buying back shares). The story hasn't much changed, since then more just played out as the market had anticipated. Revenue continues to decline, we are seeing slight margin compression, and the managment team continues to cut guidance. My reviewed perception of Lululemon is a split tale of two stories. Story #1 📔 A company with a product offering that isn't resonating with customers, and weakening public sentiment due to detrimental advertising efforts. North American markets are not resonating with the products, and I don't anticipate the "Big Ass Bag" will likely improve that. Managment on the Q2 earnings call insists that the issues are with marketing, and that they aren't reaching the audience that they need to. Story #2 📘 Lululemon is not a failing business, backed by a fortified balance sheet and robust financials. Despite revenue declines, the company still produces significant cashflows and is a money machine. At a $11.3billion market cap (around $10billion if you don't include the $1.4billion in cash on the balance sheet), the company still generates around $1.2billion in free cashflow (let's round and consider that a 10% cash yiled), and continues to operate with zero debt. ROIC remains durable at a +30%, and the book value is growing at 20% per year. The story the market is leaning on is the recent revenue declines. I don't want to ignore this because I agree it's alarming and obviously not what we want to see the business doing. The interim leadership duo has done nothing but flounder, and if they were to remain at the helm I wouldn't see any hope of a narrative change. However, there is a silver lining. Heidi O'Neal will be joining the team this week. She has a massive battle ahead of her, but may be the change that the company desperately needs. Despite the current managment believing that marketing is the resounding weakness within the business, it's been obvious to everyone else that product newness, creativity, and uniqueness have been the culprit. This was the main point of contention with founder Chip Wilson who fought to get new creative minded board members their seats. Heidi O'Neal's history at Nike was responsible for product creativity, consumer strategy, and brand which are all things that Lulu needs to focus on to turn around. She has a successful background in driving new products efficiently to market and engaging with customers effectively. One quote I often go back to is "We want to buy a business an idiot could run, because one day an idiot will run it" from Charlie Munger. Lululemon has been horrendously mismanaged, and I firmly believe that they are on the brink of their turning point. Managment (despite me saying has been incompetent) has suggested that they expect the business to be nearing its trough. So, has my opinions or thesis changed at all on the business? No, not really. I don't have any expectations of relief until the back half of 2027, and if shares continue to trade down then so be it. I have no requirement or desire to try to compete or perform on a quarterly basis, but rather over the long term. I still see substantial fundamental value within this company. In the short term, it may continue to decline, and I'm sure I'll continue to be ridiculed, but that honestly doesn't bother me at all. I believe an inflection is coming, and patience will be rewarded. As active money movers flee the company, the patient sit calmly and build their positions. read more
I know NKE is going through a rough time right now but they are still a dominant retailer and I truly believe their share price will return to higher levels. I’m prepared to hold and DCA until they do. In the meantime I’ll enjoy a small hedge through the +4% dividend that they provide. FYI: There once was a company called AMZN that once lost over 90% of its share price value. There were doubters then and there are doubters now, but AMZN is still standing strong and so will NKE! Bless
Just saw some posts about there annual warehouse sale, people waited 5 hours in line just to get in then would shop for 4-5 hours. Lots of foreign buyers have started hiring shoppers to buy product and ship it over seas as well. Demand is real, the brand is strong, and the company is showing no signs of slowing down.