When I was in university, I was introduced to high-interest savings accounts, and TSFAs. I remember putting money into a CIBC high-interest savings account and being so excited when I saw I had made about $50 in interest. I thought, Wow, my money is growing! lol During tax season, I saw how much of that interest was being taxed. I don’t remember the exact amount, but it felt like almost half of that $50 was gone!!! I thought what benefit did I really get from this? SMH So I called CIBC and closed the account. That experience pushed me to learn more about registered accounts and their tax advantages. I had so much unused TFSA contribution room at the time, and my TFSA was basically just sitting there. I started investing through mutual funds at the bank at that time....and now we have come a long way. Today, my priority is making the most of my registered accounts, especially my TFSA and FHSA. And then a HISA ...maybe? Do you have a HISA? Which accounts do you prioritize, especially if you haven’t maxed out your registered accounts yet? read more
A few days ago I was entertaining myself with youtube. ANd I ran across a title which I will be paraphrasing because I can;t remember the exactly title name. It was like Top 6 Canadian Banks and Programmable money. I saw it as a way for banks to control our savings or cash we have in their accounts. Now the way I understood it was like this. For now they will only use programmable money within banks. Meaning if I have a BMO bank account and I owe you money which you bank with is TD. I can use my programmable money to send it to your TD bank account. But before it leave my account and enters yours we need it to get some kind of approval for this transaction to happen. ANd that person/thing whatever it is approving and reject it can easily reject that transaction if you or I did something bank didn't like. Or government didn't like. I see this as a type of control over our sovereignty, and the money we earn from whatever we do to earn money. Could this be the starting of the slippery slope that will bring us into CBCD currency, and just lock us out of our money whenever they think they can. Of course if this is true they will make it as a convenience for us, just look at how easy our money is being transacted without us lifting a finger. Even though we did something to create this transaction. I believe many Canadians will enjoy this as it will be a convenience for them, as I believe many Canadian are very lazy and trustworthy of these big banks and GOC. My problem is I don't trust any of them. I wonder if this does come into play, how hard is it going to be for me to exchange my fiat CAD into BTC? Unless it changed and I wasn't aware of it, but I tried to buy BTC with my BMO Mastercard, and everytime I tried in the past it got denied. I was told they didn't trust BTC, but i do. But they let me know that CC belongs to them not me. So I never tried to use it ever again, and I always try not to use it. But I do use it for car repairs and that's it. All I know if this happens I want to convert everything i have into BTC or other crypto currencies, maybe some gold and silver. I think its a rap that everyone has to opt into because this is the slippery slope to get us to CBCD currency. I don't know how true this is because it was a video on Youtube that I saw this. I tried to find it so I can post here but having trouble finding it. Good luck my fellow Canadians, The GOC is doing it best to enslave us all into a jail that is in our minds. I for me do not want to join this Programmable money. I will be letting my bankers know this today. They can use their own money. But has anyone heard about this? And what are your thought on it? Let me see if I find this video again. Have a great day everyone, and stay out of jail lol.read more
I saw this on LinkedIn the other day. Picture this; you have extra money sitting in your checking account right now. It’s earning almost zero interest, maybe 10 cents a year if you’re lucky. You know you could earn 4% or 5% somewhere else, but let’s be honest… logging into your bank app, setting up a transfer, and moving cash around is a hassle. So, your money just sits there. For decades, banks have relied on our laziness to make billions. They take your sitting, low-interest cash and use it to fund their entire business. Then came AI. For the last couple of years, investing in AI was simple: you either bought tech giants like $META, $MSFT, and $NVDA, or you missed out. But the storyline just flipped. Now, investors aren’t just looking at who is building AI, they are looking at who AI might destroy. And banks are right in the crosshairs. Imagine a personal AI assistant running in the background of your phone. Every night, it looks at your checking account, calculates what you need for bills, and automatically sweeps every extra dollar into a high-yield account paying top market rates. Zero effort from you. If millions of people start using AI agents to do this, that mountain of cheap cash banks rely on vanishes overnight. To keep your money, banks will have to pay you way higher interest rates, shrinking their profit margins fast. That’s why investors started selling some bank stocks recently. They aren't worried about banks going broke; they're worried software is about to steal their easiest profits. It makes you think: Would you trust a personal AI assistant to automatically move your money around to earn you more interest? — This is for informational and educational purposes and it is not a financial advice.read more
Today I read that $RBC / $RY Dominion Securities was founded in 1901, which means it is one of Canada's oldest investment firms. Apparently they started as a single office in Toronto and have grown alongside Canada's economy for more than 125 years. I think for us on Blossom it is a reminder that real wealth is rarely built overnight. The biggest fortunes are often created through patience, discipline, and staying invested through market cycles. The companies, funds, and portfolios that stand the test of time aren't always the most exciting today, but they often deliver the best results over decades. Sometimes the most powerful investing strategy is also the simplest: Buy quality assets and give them time to grow. This sounds familiar, as it likes Warren Buffet investment strategy. What's one investment you have held the longest, and would you buy it again today? — For educational purposes only, not financial Advice. read more
Al companies are still figuring out how to make money. Wall Street already has. - Morgan Stanley $MS estimates Al-related capex could eventually reach $10 trillion. - Bank of America $BAC says it has helped raise nearly $500 billion for Al-related companies since 2025. - GoldmanSachs $GS calls it an Al capex super cycle. Think about where the money goes before an Al product makes $1: Debt. Equity. Data centres. Power. Chips. Leases. IPOs. Someone has to finance all of it: $JPM J.P. Morgan $GS Goldman Sachs $MS Morgan Stanley $C Citi $BAC Bank of America Everyone is searching for the company that wins Al. The banks don’t necessarily need to know.They can finance the race.read more
Why was Canadian Banc Corp. (TSX: BK) halted today by the Canadian Investment Regulatory Organization (CIRO)? 🤔 Does anyone know what triggered the trading halt, and has any official explanation been released? Curious to hear your thoughts.
Regulators fined Bank of America (BAC) more than $1.2 billion on Tuesday over widespread failures in the banking giant's safeguards against money laundering and other illicit financial activity. The Treasury Department said the nation's second-largest bank failed to properly monitor trillions of dollars in transactions and to report more than $5 billion in suspicious activity, including transactions potentially tied to Chinese money-laundering networks, narcotics trafficking, and fraud. https://finance.yahoo.com/markets/article/bank-of-america-hit-with-12-billion-penalty-over-money-laundering-failures-201623796.html
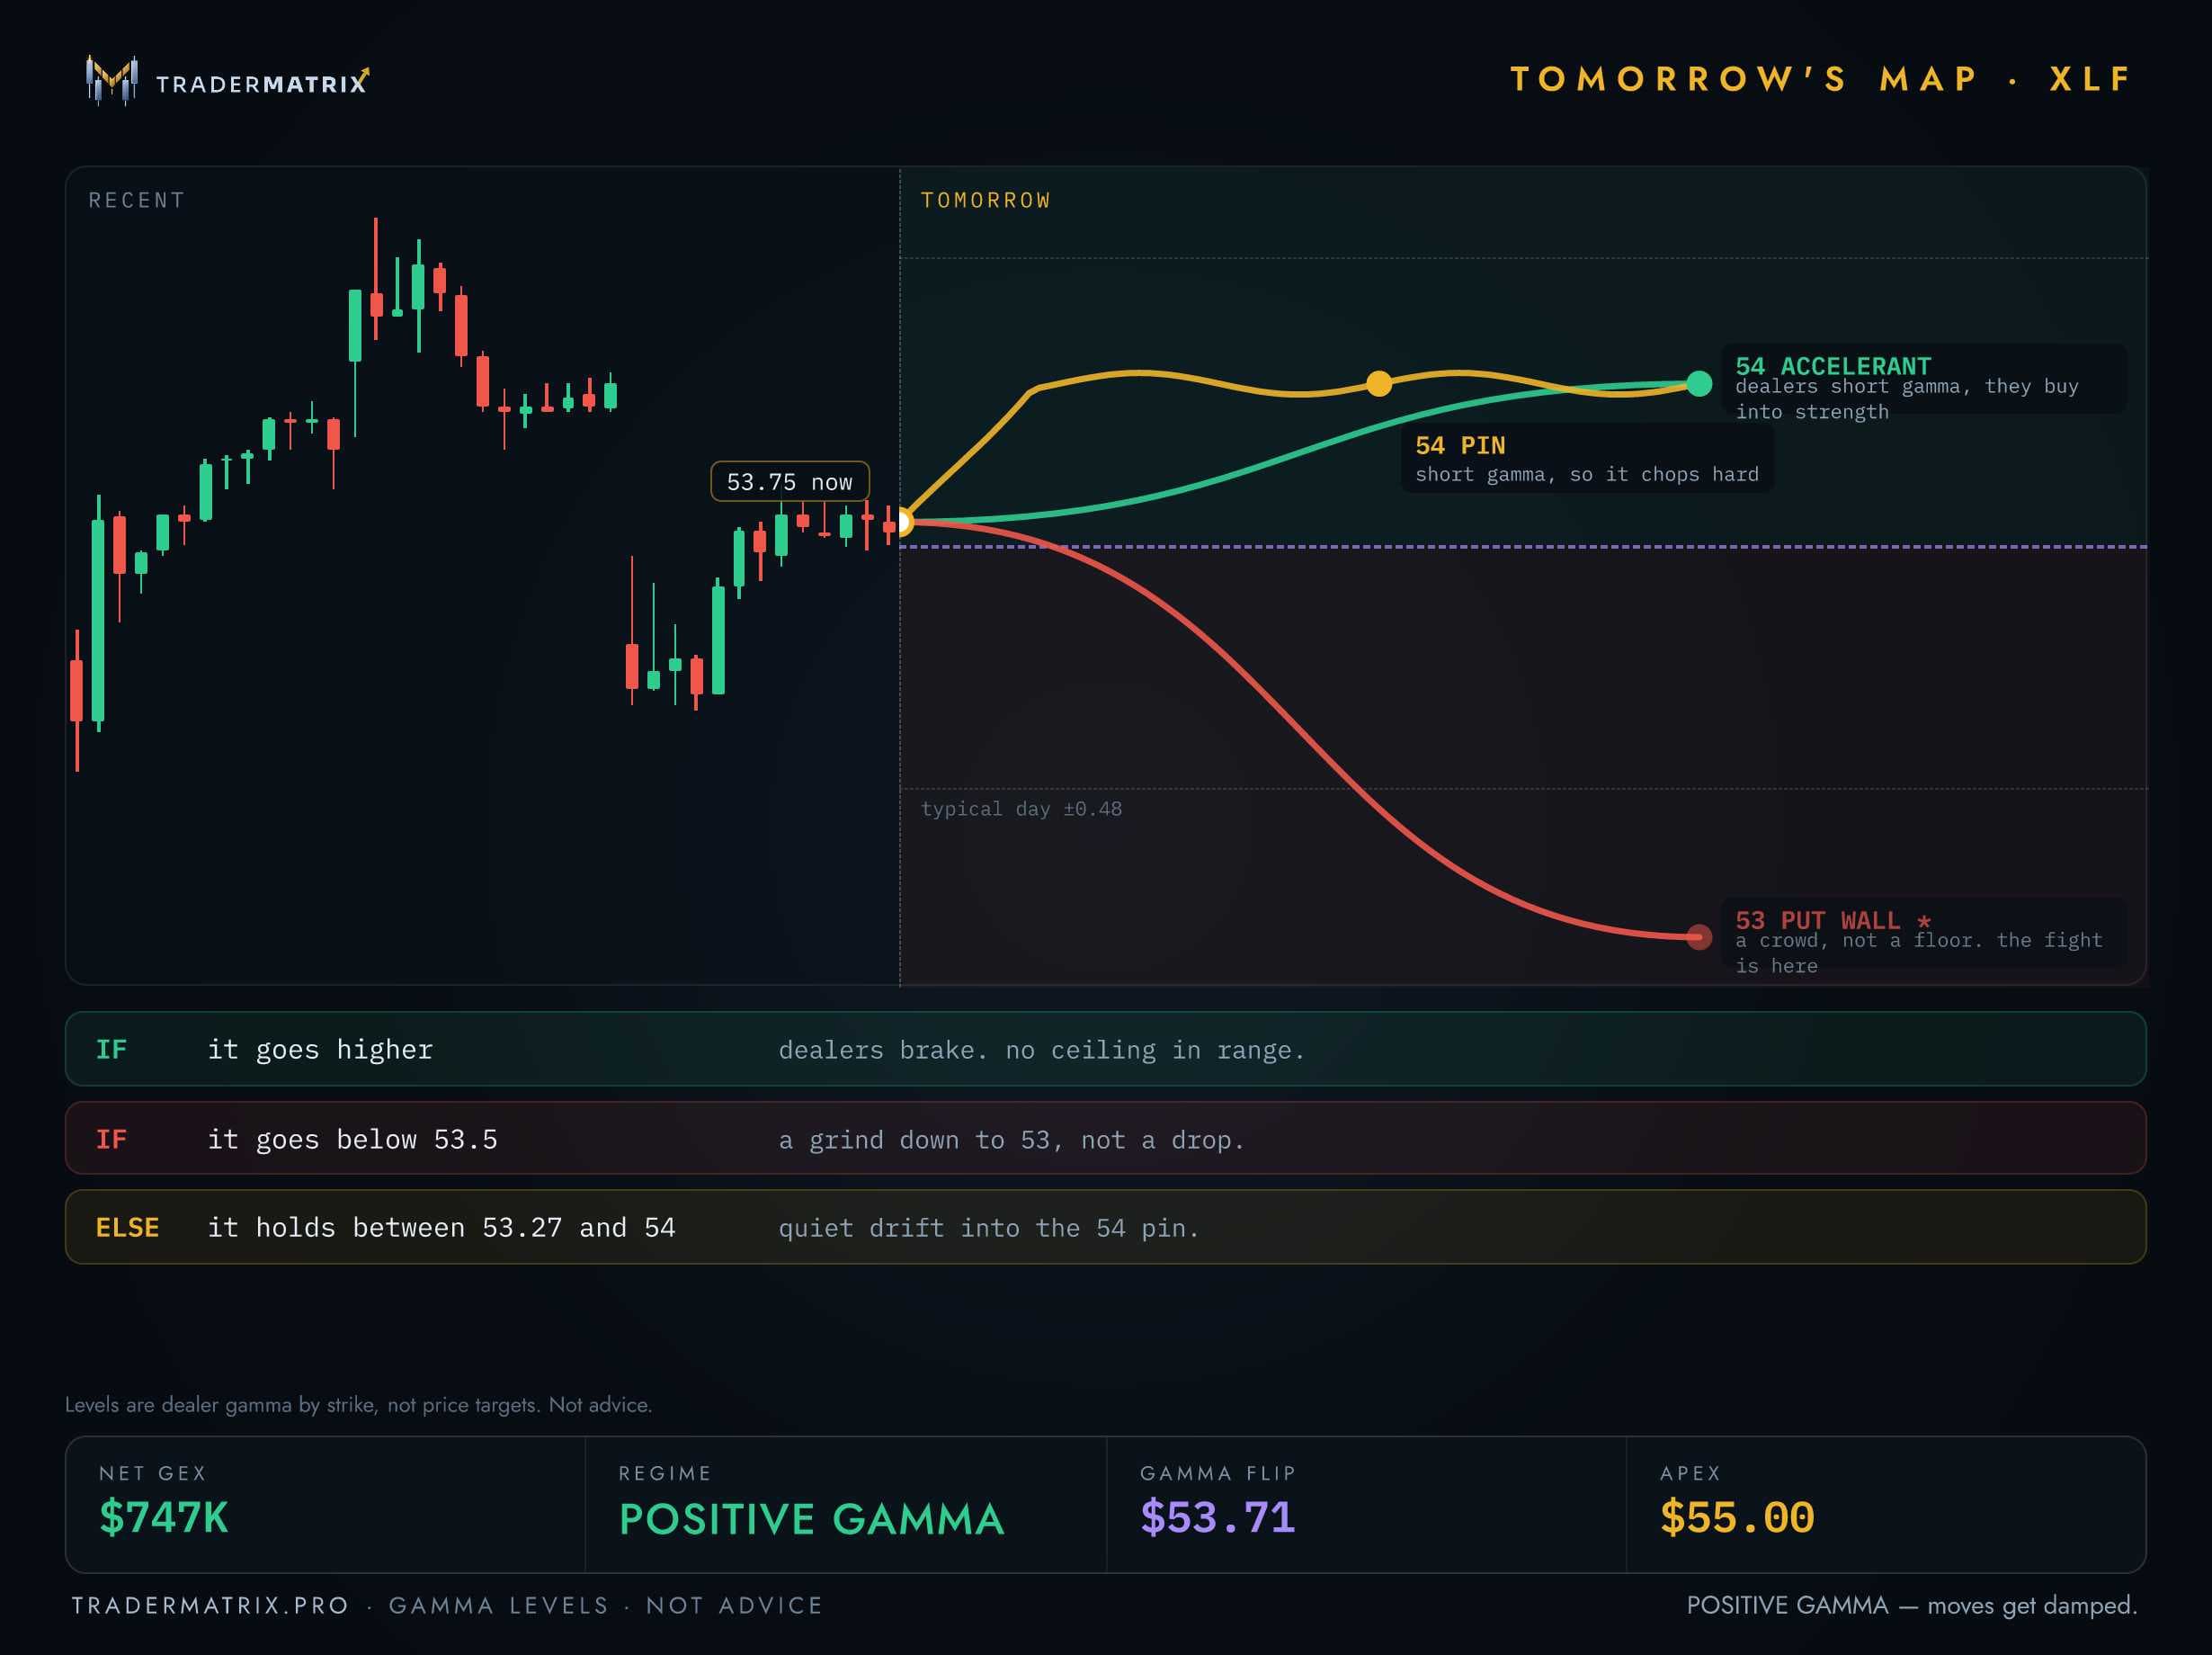
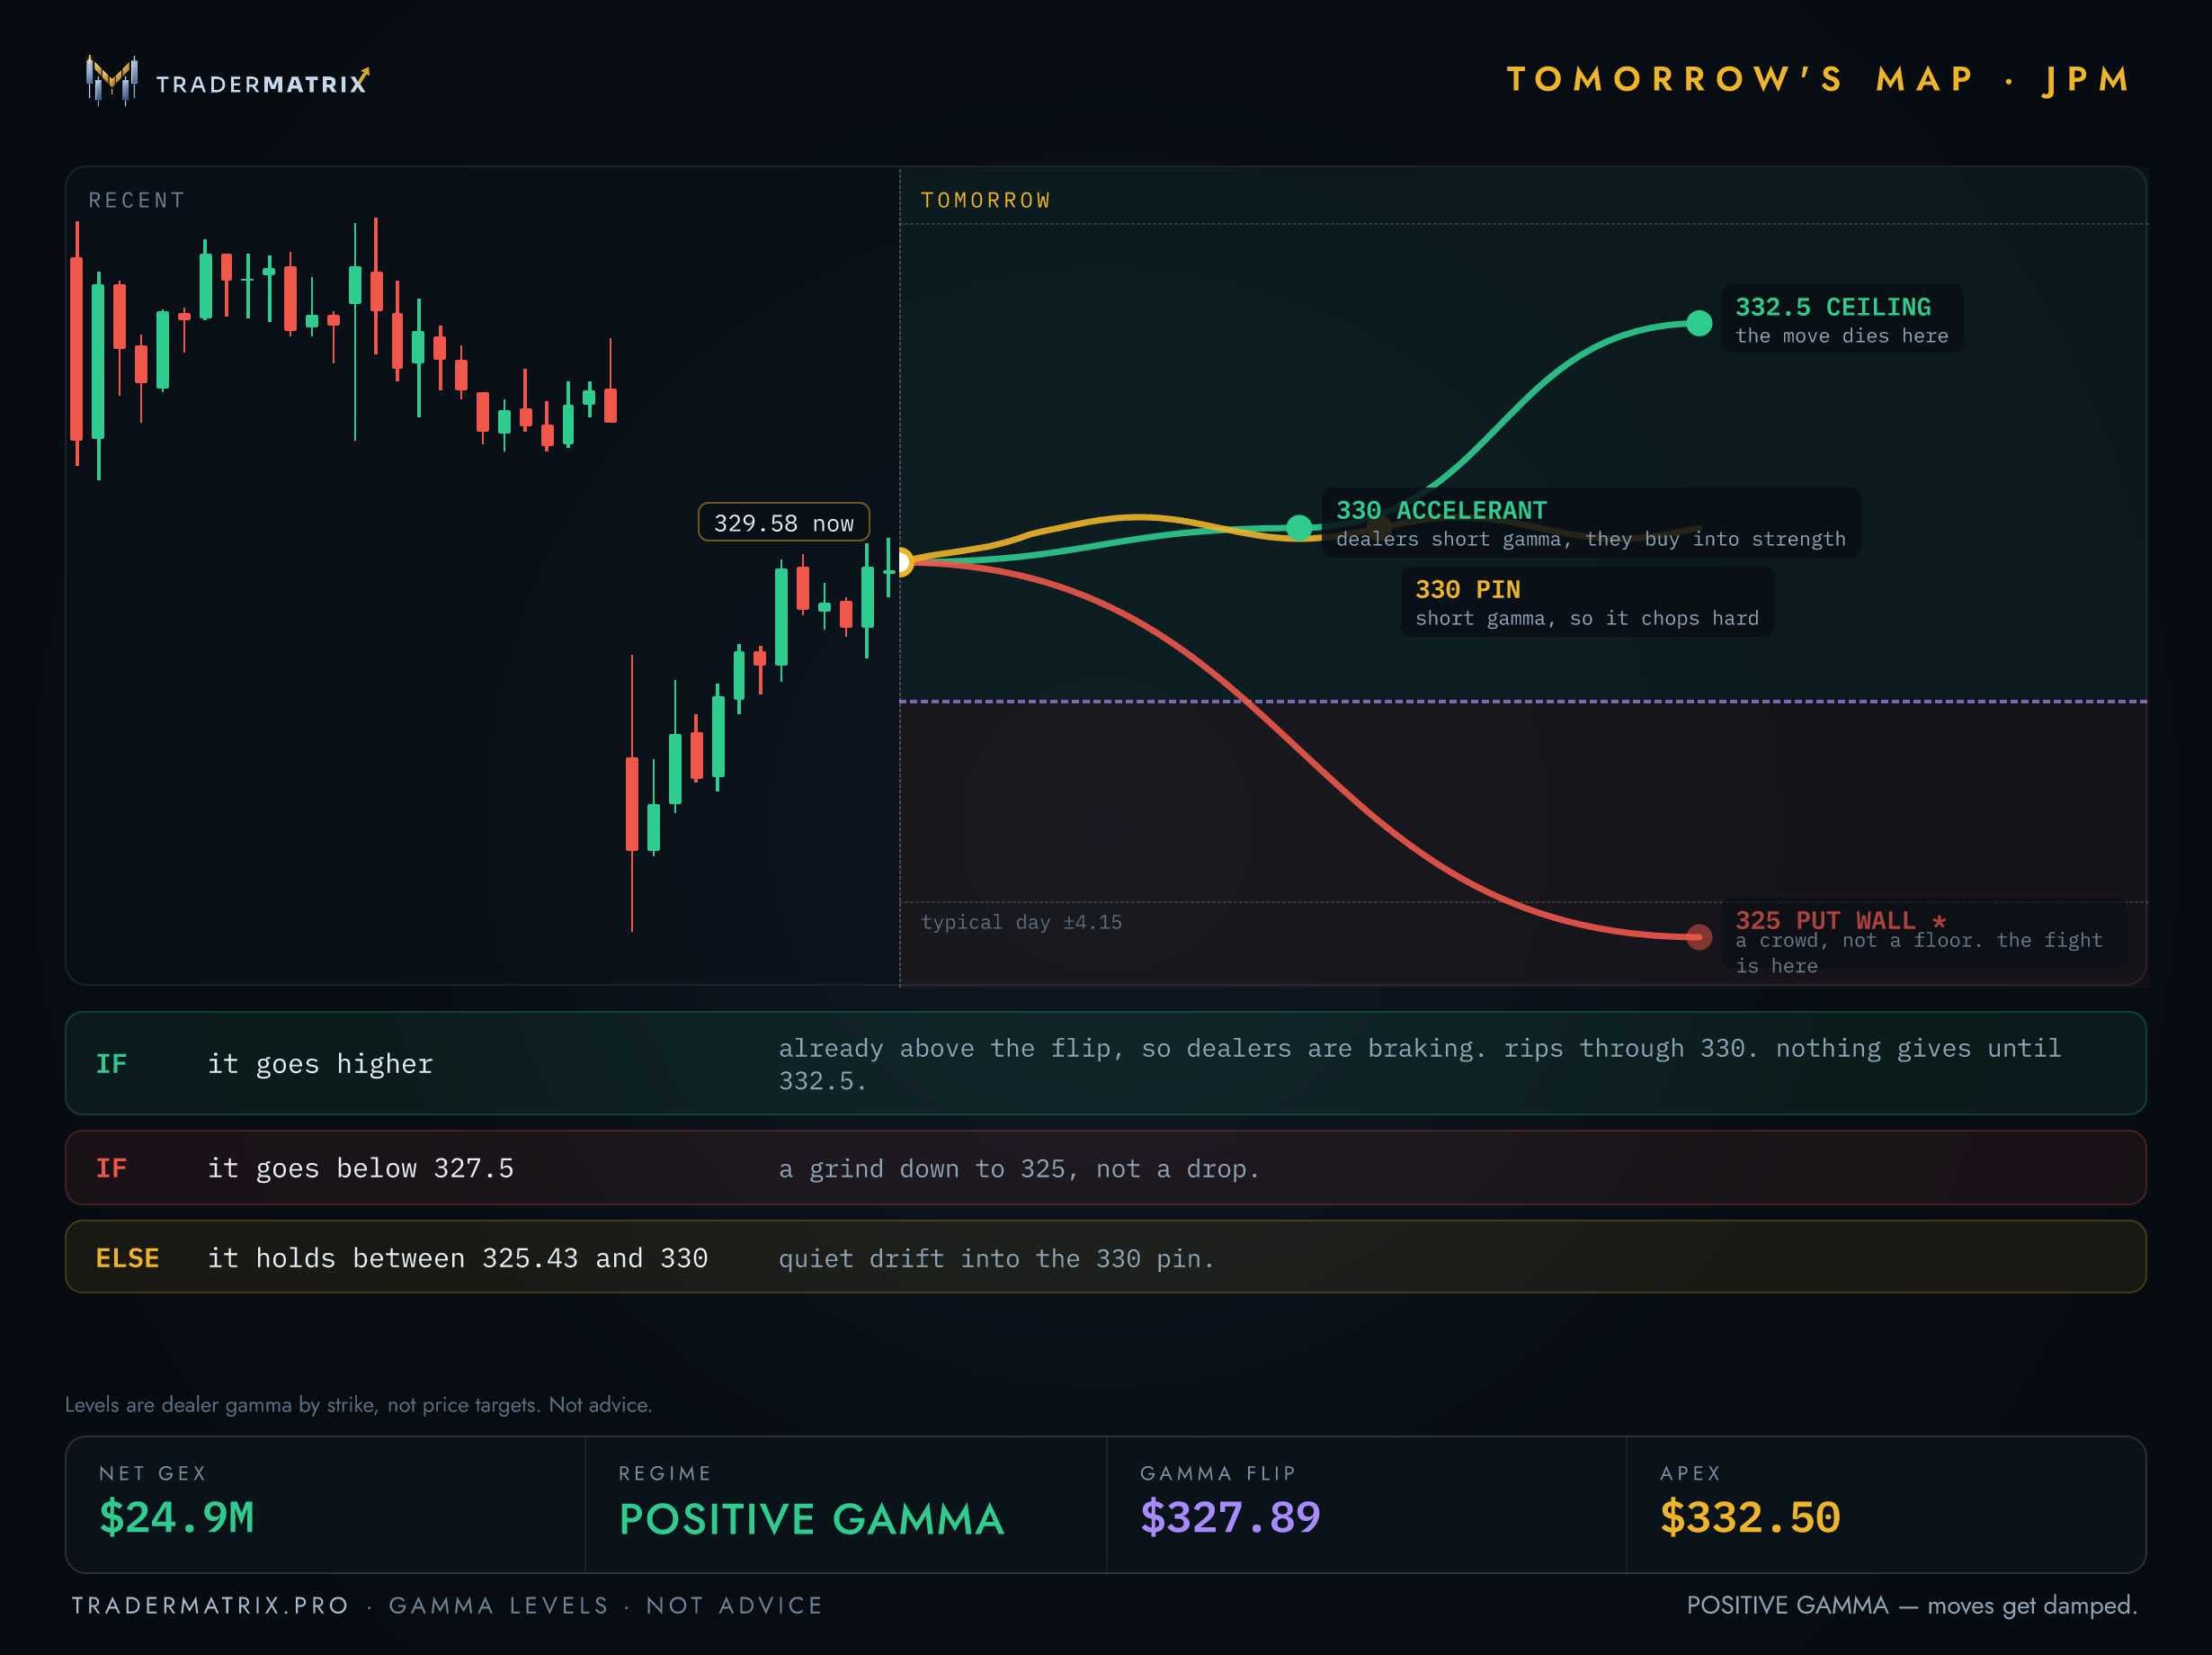
I think financials are starting to bottom. Not bottomed. Starting to. Quick RSI guide, because the rest of this uses it RSI is a score from 0 to 100. It shows how hard something has been getting bought or sold. - Over 70: overbought. Ran too hot, stretched. - Around 40 to 60: the middle. Nothing stretched. - Under 30: oversold. Sold too hard, a bounce gets likely. - Under 20: rare. Usually panic. And you read it on three charts, big to small: - Weekly: the big trend. Slow, matters most. - Daily: the swing in the middle. - Hourly: just timing. Fast and noisy. Bottoms usually line up in that order. Weekly cools off, daily gets washed out, hourly stops falling first, then price follows. $XLF right now, big to small - Weekly: was in the high 60s in late summer, almost hot. Now mid 40s. All the heat is out. Not oversold, but not stretched anymore either. - Daily: fell into the mid 20s around the start of October and sat under 30 for days. That is where the price made its low, around $53. Now back in the low 30s and holding there. - Hourly: today it dipped early, got bought, and closed near the top of its day. The selling just stopped pushing. Smallest signal, but it is the right order. Why banks, in plain words Rates went up too fast, and banks felt it first. Borrowing slowed, mortgages got too expensive, and the old bonds banks hold lost value. If rates calm down, banks are one of the first groups you would expect to stop falling. Today they did not fall. $XLF was down a little, but it never went back to last week's low, even with rates spiking again. A week ago, today would have made a new low. The big names held it up. $JPM fell under its 200 day line, around $328, this morning, and buyers pulled it back above by the close. $V was up a bit, like always in this selloff. $BRK.B was flat. The selling was in the smaller banks, and I am not dressing that up. Big names holding first is how bottoms start, but the rest still have to catch up. The money, from TraderMatrix - Financial stocks took in more options money than almost any other sector today, third best of eleven. For every $1 bet down, close to $3 was bet up. - $JPM: all of its flow was calls, close to $1M. One bigger bet needs it back in the mid $340s by next week, right after earnings. - $XLF itself: only a few tiny put bets. No size. The money likes the big banks more than the fund. - Dark pools, the big private trades, went the other way on JPM. The app read them as selling, but the app guesses on that, it says so itself. And the stock still closed fine. - No dark pool trades at all in $XLF. Nothing hidden either way. The dealer map, charts below - $55: the biggest dealer level, above price. Levels like that pull price up. That is the target. - $54: a pin, a level price gets stuck on. - $53: a crowd of put bets. The map calls it a crowd, not a floor, and says the fight is here. Same spot as last week's low. - The flip line sits right at the price. We are on it. - Honest part: the app argues with itself. The chart says dealers calm moves, another page says they speed them up. I trust the levels, and the levels agree. $53, $54, $55. The top names have cleaner maps. JPM's big level sits just above it, around $330 to $332. $V's is up at $380 with a strong floor at $370. Both Apex charts are under this post, $XLF first, then $JPM. Rates, still the main thing The 10-year hit about 5.36% this morning, highest since 2002. Then buyers showed up in force at the government bond sale and it backed off to about 5.28%. My line for this idea is still 5%, we are not close. But buyers pushing back is new. What I need to see - Thursday's bond sale: buyers show up again. - $XLF through the $54 pin and a close over $55. - $JPM keeps holding the line it defended today. - October 13 earnings: not the headline number. Do they guide lending income up or down, and are bad loans getting worse. What kills it - $XLF under last week's low, around $53, and staying there. - $JPM loses its line for real. - Rates close above about 5.3%. Close, not a morning spike. Today spiked and could not hold it. That is the stack. Weekly cooled, daily washed out, hourly stopped pushing, biggest bank defended its line, money is betting up into earnings, and the dealers' biggest level sits overhead at $55. Against it: small banks still weak, the fund's own flow was nothing, and my app cannot agree with itself. Not proof of a bottom. Bottoms never come with proof. They come with a stack like this, and then price either follows or it does not. The maps and flow in this post come from TraderMatrix Pro, the main tool I pay for. My link: https://www.tradermatrix.pro/?ref=FZ9MX6FC. Full disclosure, it is an affiliate link and I earn a commission if you sign up. No fake discount. Just the tool on my screen every day. Are you seeing a bottom forming in financials, or is this just a pause before the next leg down? Not financial advice read more
HOW CAN YOU EVEN BE BEARISH ON $SOFI ‼️ - Members growing exponentially - Total Products growing exponentially - Total Deposits growing exponentially Are you buying $SOFI ?