COIN vs CONY to be a Growth Based Income portfolio
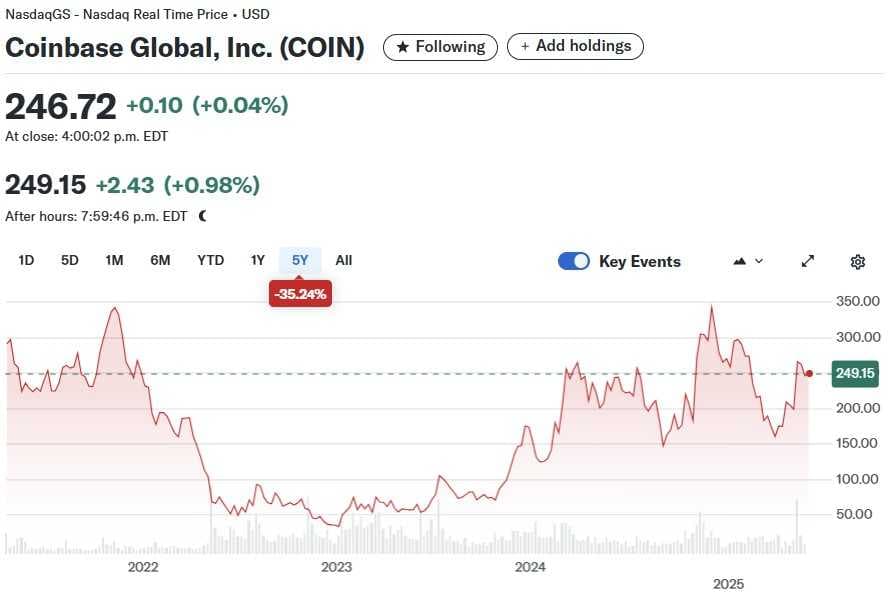
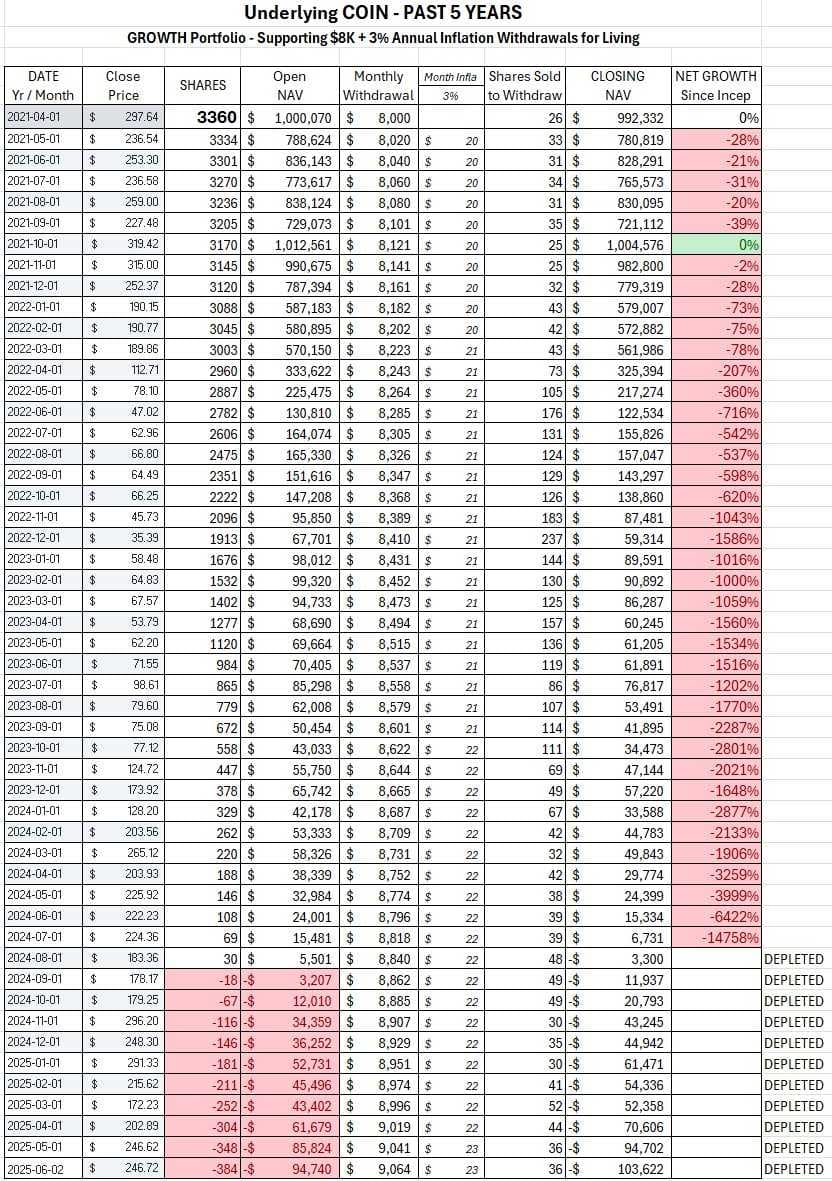
There is a constant attack by traditional growth strategy purists that just cant wrap their minds around the value of these high yield CC etfs to all us investors that have a priority on generating significant monthly income vs trying to maximize capital growth. One of their frequent arguments are "why invest in these CC etf - the underlyings will ALWAYS beat the CC etf in ROI". They repeatedly dismiss the critical factor - they never take monthly withdraws from the portfolio into their calculations. They sometimes say - the growth will be greater than the withdrawals so its not a problem. I decided to take a few hours and use an actual example to show why their logic is FLAWED when investors that buy CC ETFS need a portfolio that produces monthly income. I created a spreadsheet using the underlying $COIN within $CONY using the actual monthly closing prices for the past 5 years. As per their argument that Underlyings ALWAYS beat the CC ETF... and taking into the reality that investors of CONY and other CC etfs, do it to generate regular income for living expenses, I have used a $1 MILLION Portfolio that bought as many COIN shares that could be bought on the closing price of COIN 5 years ago. That would be 3360 shares. Since COIN generates no dividends, thru the entire next 5 years, the investor cannot buy any more shares since the portfolio generates any new Cash to buy more shares. I also set an initial reasonable monthly Cash Withdrawal of $8000 with a 3% annual increase in the monthly withdrawal to address inflation. Of course, since COIN generates no dividends, the only way the portfolio will be able to pay for these monthly withdrawals is to sell some of its COIN shares at the current price of COIN when you sell each month. As you can see on the attached spreadsheet... the GROWTH portfolio would be completely depleted after only the 4th year! The portfolio never even survived 5 years! I can also say at the same time, if CONY existed 5 years ago and an investor invested $1 million in CONY etf units, 5 years later, even if the NAV of their CONY portfolio was down 60%... it would still have a significant portion of its NAV remaining (much greater than ZERO) since its monthly distributions could easily have paid for the monthly $8000 - PLUS the excess distribution cash would have been reinvested to buy more CONY units to more than address the inflation. So, the CONY vs COIN example proves that the underlying DOES NOT ALWAYS BEAT THE CC ETF - in fact when considering the purpose of CC ETFS is to withdraw monthly cash - the underlyings in the long run would almost never beat the CC etf. IT simply cant unless the underlying keeps constantly growing for ever and ever... and what investor wants to rely on that happening!
19K views
119 Comments
Ed
@edsam · 1yr
Thanks for posting this. Having been called a unsophisticated "flat-earther" for not selling stocks for income, I appreciate your detailed analysis. These ETFs are tools for investors to achieve their desired outcome. The purists assume moral superiority because they confuse unrealized paper gains with steady spendable cash. They cannot accept other people who may have different priorities. When I look at my fellow "flat-earthers", I see them posting monthly income placing them in the top 1%. Your portfolio kept steady while you grew your income from $30k to $40+k monthly. All of us are enjoying financial freedom well before the traditional retirement age. How do they define success?
Zain @zains · 1yrEdited
Thanks for sharing, Perry ! They have a very different mindset, and while it may work for them, it doesn't for many. The group continues to argue the same point over and over. 1000s of people on Blossom and outside rely on the monthly income while the portfolio continues to grow.
Heath
@incomewealthinvestor · 1yr
My last debate went on for hours over the w/end and I used 3 of my top 10 holdings as an example for yearly TOTAL returns. I even threw in $BANK for good measure but unfortunately no admission, couldn’t be debunked. All the following use some sort of covered call option strategy. 1 year TOTAL return: $LBS 29.95% $BANK 21.97% $EIT-UN 17.64% $HDIV 15.82% Yes, my portfolio produces income and growth. Always be respectful when others are not, always prove your point not defend your position. Happy investing!!!
Jacob B
@jacobb · 1yr
Maybe everyone can agree that people have different strategies. If it works for you, then great. I’m not a fan of CCs, but I feel you both made fine arguments. I have a bias, but I just don’t care enough about what other people do to bother caring about strategy other than my own. Time will tell. People are different. Leave it at that.
See the full comment section 👀Sign up for the full Blossom experience!