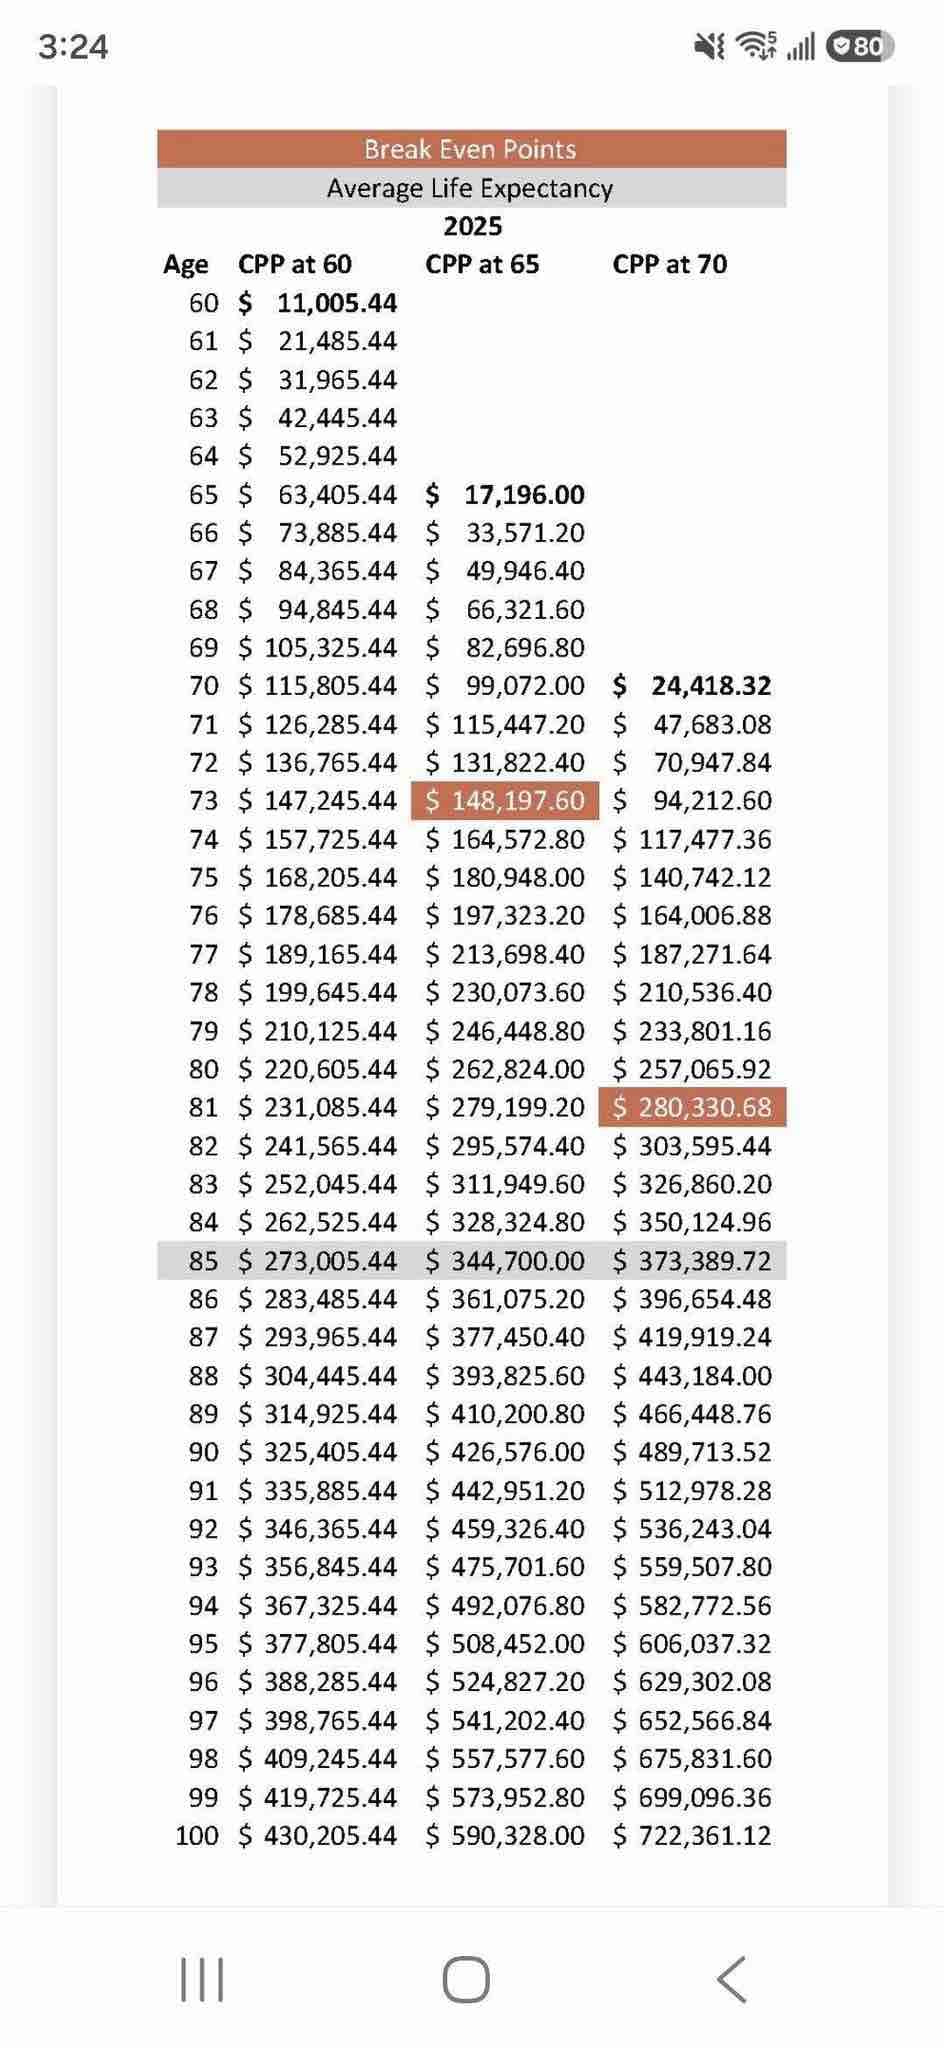
The age old question? Here’s a handy chart from 2025 that may help you in your decision making process. Let’s hear what you think?
526 views
35 Comments
Lisa @retired · 18d
I think there’s another side to the “wait until 70 for CPP” argument that people don’t always consider. Yes, you get more CPP by waiting, but if you have a large RRSP and non-registered portfolio, those investments could grow quite a bit while you wait. Then you may end up with larger withdrawals later, which could push your taxable income higher. And it’s OAS that gets clawed back, not CPP, but CPP and your withdrawals both count toward that income. So I don’t think waiting until 70 is automatically the best answer for everyone. I think it’s really about looking at your whole retirement picture and your after-tax income, rather than just maximizing the CPP payment.
Matt Gray@matt.41 · 18d
My opinion is to take it immediately. The chart is great for showing the breakeven points but it also doesn’t account for reinvesting some or all of the funds. If you’re not reinvesting any of the funds you obviously need the money as soon as possible to live off of. NOTE: not everyone’s situation is exactly the same and there are scenarios (I.e. taxes if not planned out earlier) where it makes sense to wait.
Paul N@pauln · 18d
Like everyone here has mentioned that it’s unique to everyone’s personal situation. A lot of financial advisors default straight to the wait to 70 option unless it’s life or death for you. This post is timely for me as I just started the 65 option. OAS starts next month. Firstly I get the max, not the Canadian average which is about $850 a month up surprisingly from $700 a few years ago. So this alone is a big reason some people need to delay unless of course you can manufacture a disability and get special compensations to up your CPP early. I have the good fortune of being able to grow my TFSA into the mid $300 k level and being able to draw decent distributions tax free monthly when required. So I’m treating my TFSA like a growing annuity, and any money I would remove plus new cap room will be topped up from my RRSPs every January 1st. I still don’t think people fully understand the power of a TFSA used correctly. Inflation is going to become a bigger and bigger concern for everyone regardless of how the true inflation numbers are being manipulated. If something your family buys has doubled, that’s your inflation number and not a manipulated basket of goods you don’t purchase. I honestly don’t know how people on the margins are making it these days. I feel I will be ok, however people on a “skinny” fire or retirement I’ll agree probably should wait to 70 but probably can’t, because their financial situation won’t allow them to. So it’s a good sentiment but an unrealistic goal for some. My plan works for me. I actually have been able to grow my investments now into my third year of retirement after all my spending has been calculated. But everyone has to find their own comfortable path for themselves.
Catherine @ffcatherine · 18d
If possible wait. Take out more from portfolio to bridge the gap if possible
See the full comment section 👀Sign up for the full Blossom experience!