Google 😱
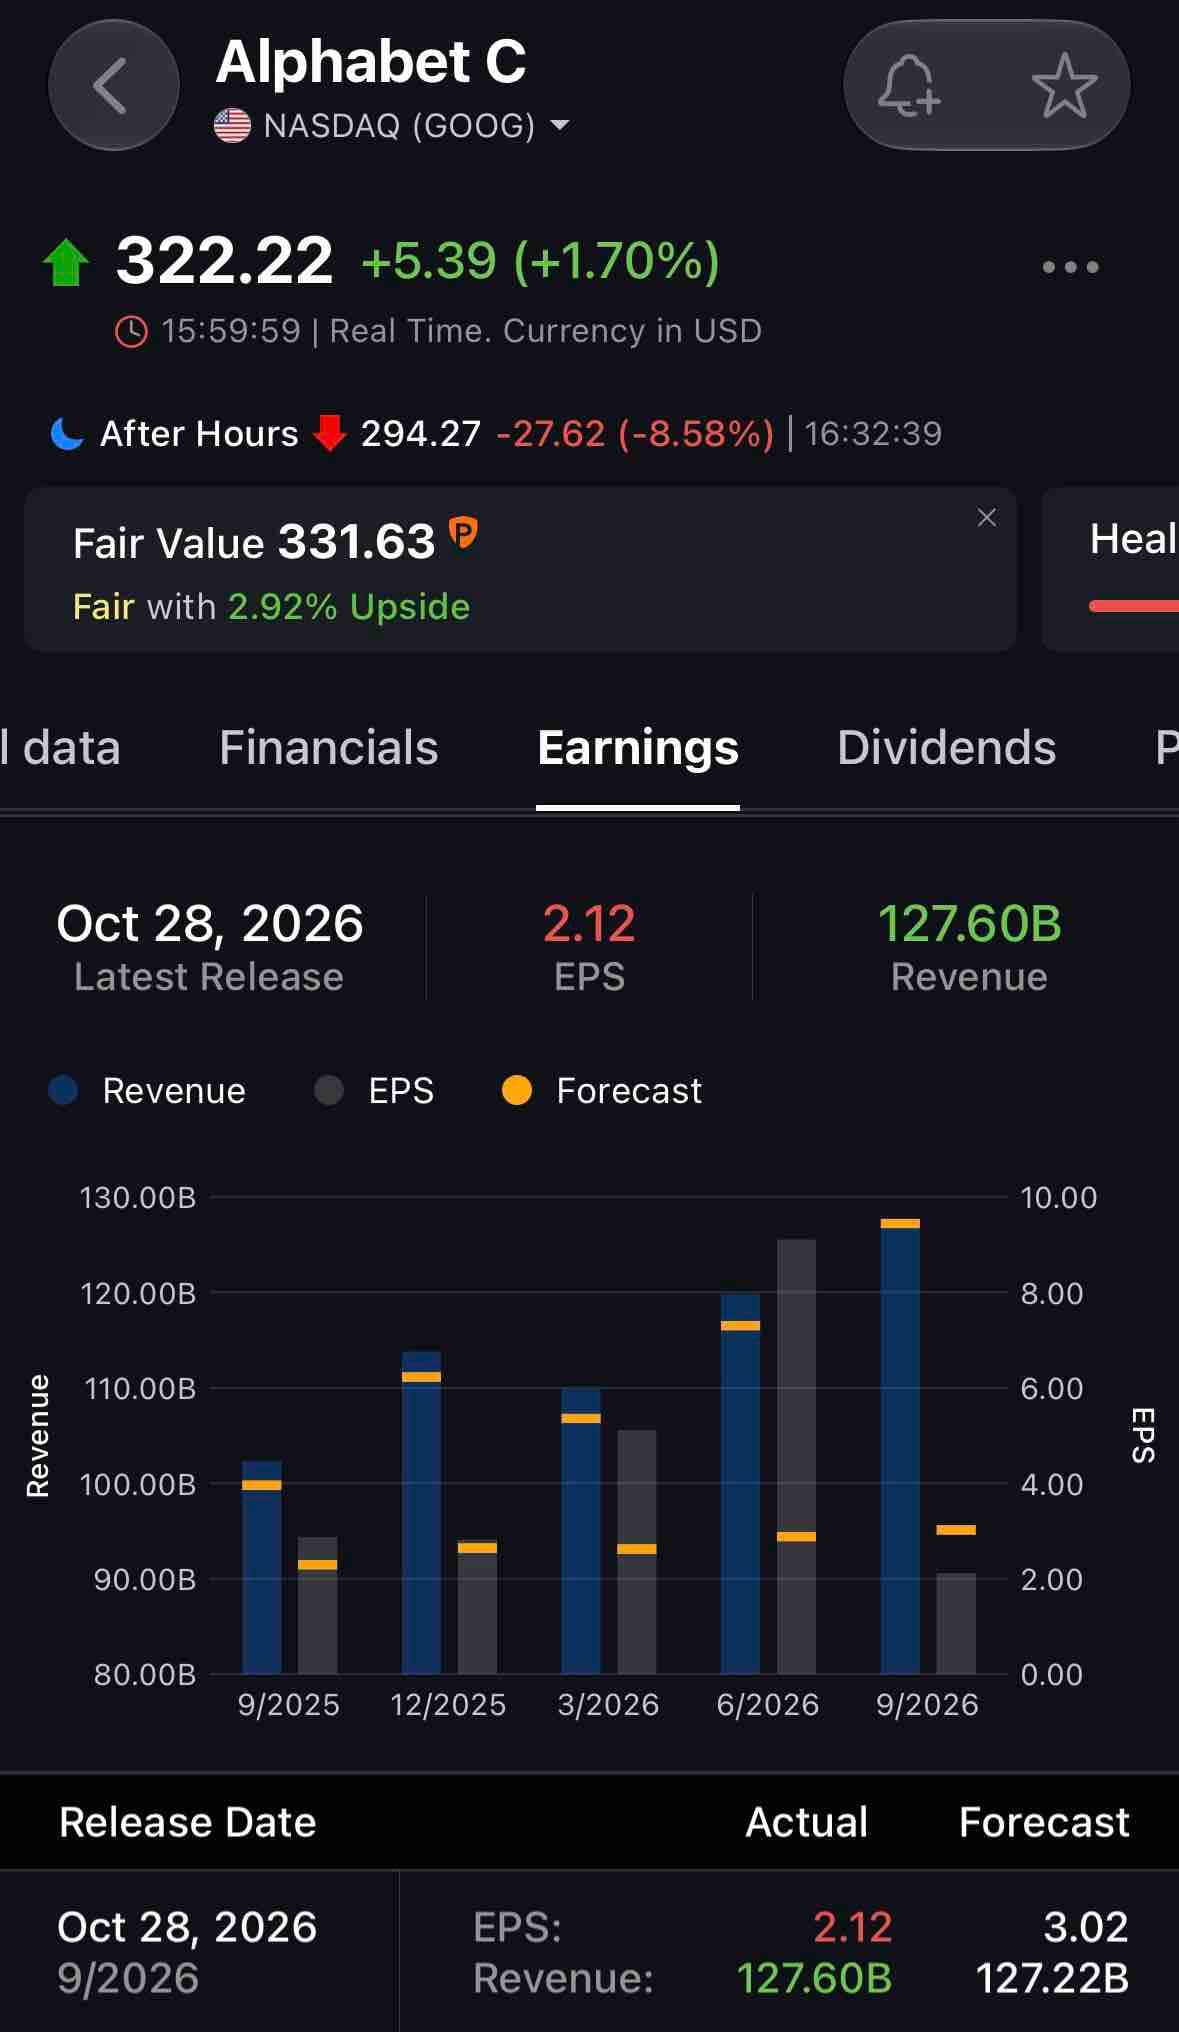
Alphabet reported tonight and the after hours reaction is ugly, down to around $295 at the low.
Let me walk through what actually happened, because it's more mixed than the EPS headline suggests.
EPS came in at $2.12 against a $3.02 consensus. That's a big miss on paper. But look under the hood. There was an $8.7B loss on equity securities in the quarter, which knocked about $0.55 a share off net income after tax.
That's an investment mark, not the business breaking.
Revenue was $127.6B, up 25%, but that was a narrow miss against a consensus closer to $128B, and the ad business was soft:
Search came in at $63.35B against roughly $65B expected, YouTube missed too, and total ads were about $82B against $83.5B expected.
Operating income of $40.6B also came in below the $43.2B some were modeling. I won't dress that up.
The core ad engine had a softer quarter than expected.
Cloud though, Cloud revenue surged 103% to $30.7B, well ahead of the $29.1B or so expected. It didn't just beat, it accelerated past last quarter's 82%.
Operating income at Cloud went from $3.6B a year ago to $11.1B. Growth and profitability at the same time. That's the monetization proof everyone keeps asking for.
The spending is the other half of the reaction. Capex hit $51.4B in the quarter, $132B year to date, and free cash flow went negative at minus $9.1B.
Ironically the capex actually came in below the $55 to $56B some expected, but negative free cash flow is negative free cash flow, and the market is punishing it.
Google is a core position for me, 25% of my TFSA, so I'm not writing this from the sidelines.
My honest read: Cloud is carrying the thesis right now, ads had a soft quarter, and the cash flow picture is what the stock will trade on until it turns. All three things are true at once.
Not financial advice. Just my read.