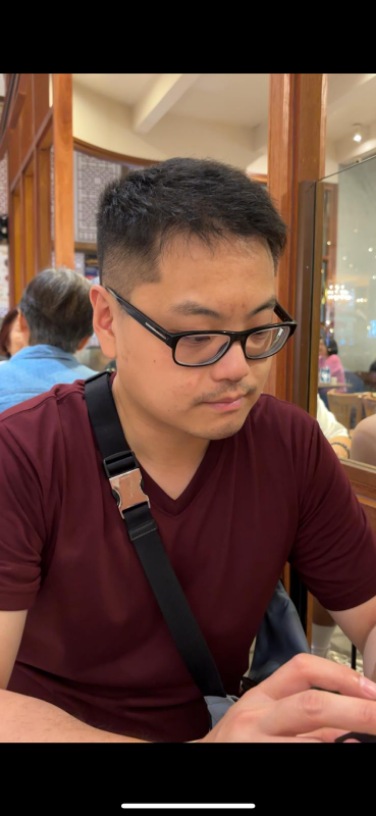
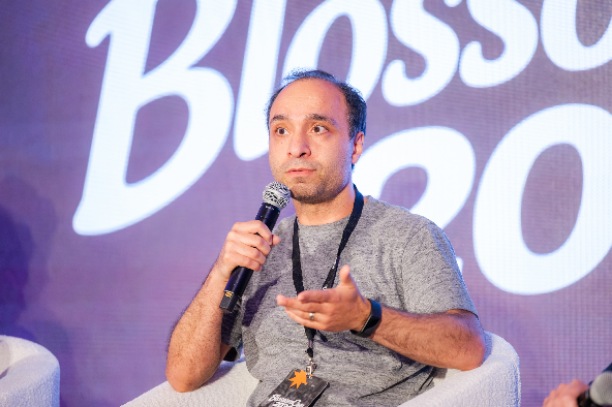
Tony retired in 2024 in his 30s with a portfolio size of just over $850,000. Can Income Investing Fund Early Retirement?! In this interview I talk to him to better understand what it took for him and his wife to walk away from their job in their 30s and live off their investments. We'll see hportfolio built around covered-call ETFs and investment income actually sustain early retirement? Tony, better known as @onemadtony on YouTube and Blossom, is a Vancouver-area investor who left the workforce in 2024 with approximately $850,000 invested. His portfolio has since grown to around $1.23 million, even after withdrawing more than $100,000 over roughly two and a half years. Tony shares his unconventional journey from early trading and dividend investing to covered-call ETFs, income investing, and financial independence in his late 30s. We explore how he structures his portfolio, manages retirement withdrawals, and balances investment income with long-term growth. In this interview, we discuss: 🟣How Tony's upbringing shaped his relationship with money and investing. 🟣 Why his mother's cancer diagnosis changed his perspective on work, retirement, and time with family. 🟣How he and his wife decided they could afford to leave their jobs. 🟣 His three-part portfolio strategy: living expenses, long-term core holdings, and a more flexible investing account. 🟣 Covered-call ETFs, distributions, and why a high yield doesn't automatically mean a sustainable return. 🟣 His real-life experiment comparing his income portfolio against $XEQT , $VFV , $QQC , and $HYLD under the same withdrawals. 🟣 Retiring with an approximate 5–7% annual withdrawal rate, keeping a cash reserve, and managing risk. 🟣 The psychological appeal of investment income versus selling shares to fund retirement. 🟣 Why understanding the risks of income investing is just as important as understanding its benefits. 🟣 What financial independence has taught Tony about enjoying the journey instead of waiting until you reach your goal. One of Tony's biggest takeaways is that financial independence isn't just about reaching a portfolio target. It's about having the freedom and flexibility to spend time with loved ones when it matters most. Tony also offers a thoughtful perspective on the income-investing debate: the strategy that works best on paper isn't necessarily the one that helps you feel comfortable enough to stick with it. But before relying on high-distribution ETFs to fund retirement, it's essential to understand where the distributions come from, the potential trade-offs, and what could go wrong. 🍿Fun Facts: Tony shares how @mr.financial is one of his most favorite Blossomers with his detailed, in-depth videos/posts which create good engagement. 😃 Also similar to @karyungtom, he plays and is a big fan of Magic: The Gathering! 💬 I'd love to hear from you: If you were financially independent today, would you prefer to live off investment distributions or sell a small percentage of your portfolio each year? Why? ... For me personally, I am comfortable enough to sell a small portion of my portfolio, as that way I could have more control over how much money I can withdraw and could potentially lower tax implication based on a more optimized drawdown strategy. https://youtu.be/GmRSZ-v4BO8
5,624 views
12 Comments
Tony Si@onemadtony · 16h
Thanks Moe! I had a great time!
Mr Financial
@mr.financial · 6h
Had to watch when I'm mentioned in a video 😆 jokes aside, it was a lovely interview. I can relate to @onemadtony and the desire to hang up the boots and spend time with loved ones while you still can. Going to a place with a lot lower cost of living or reducing expenses as you have is a clever way to go about it.
Heath
@incomewealthinvestor · 7h
Well done Tony 👏👏👏
Adam @abdidio97 · 16h
Fairly new to investing here, what do you think of todays crash in AI stocks
See the full comment section 👀Sign up for the full Blossom experience!