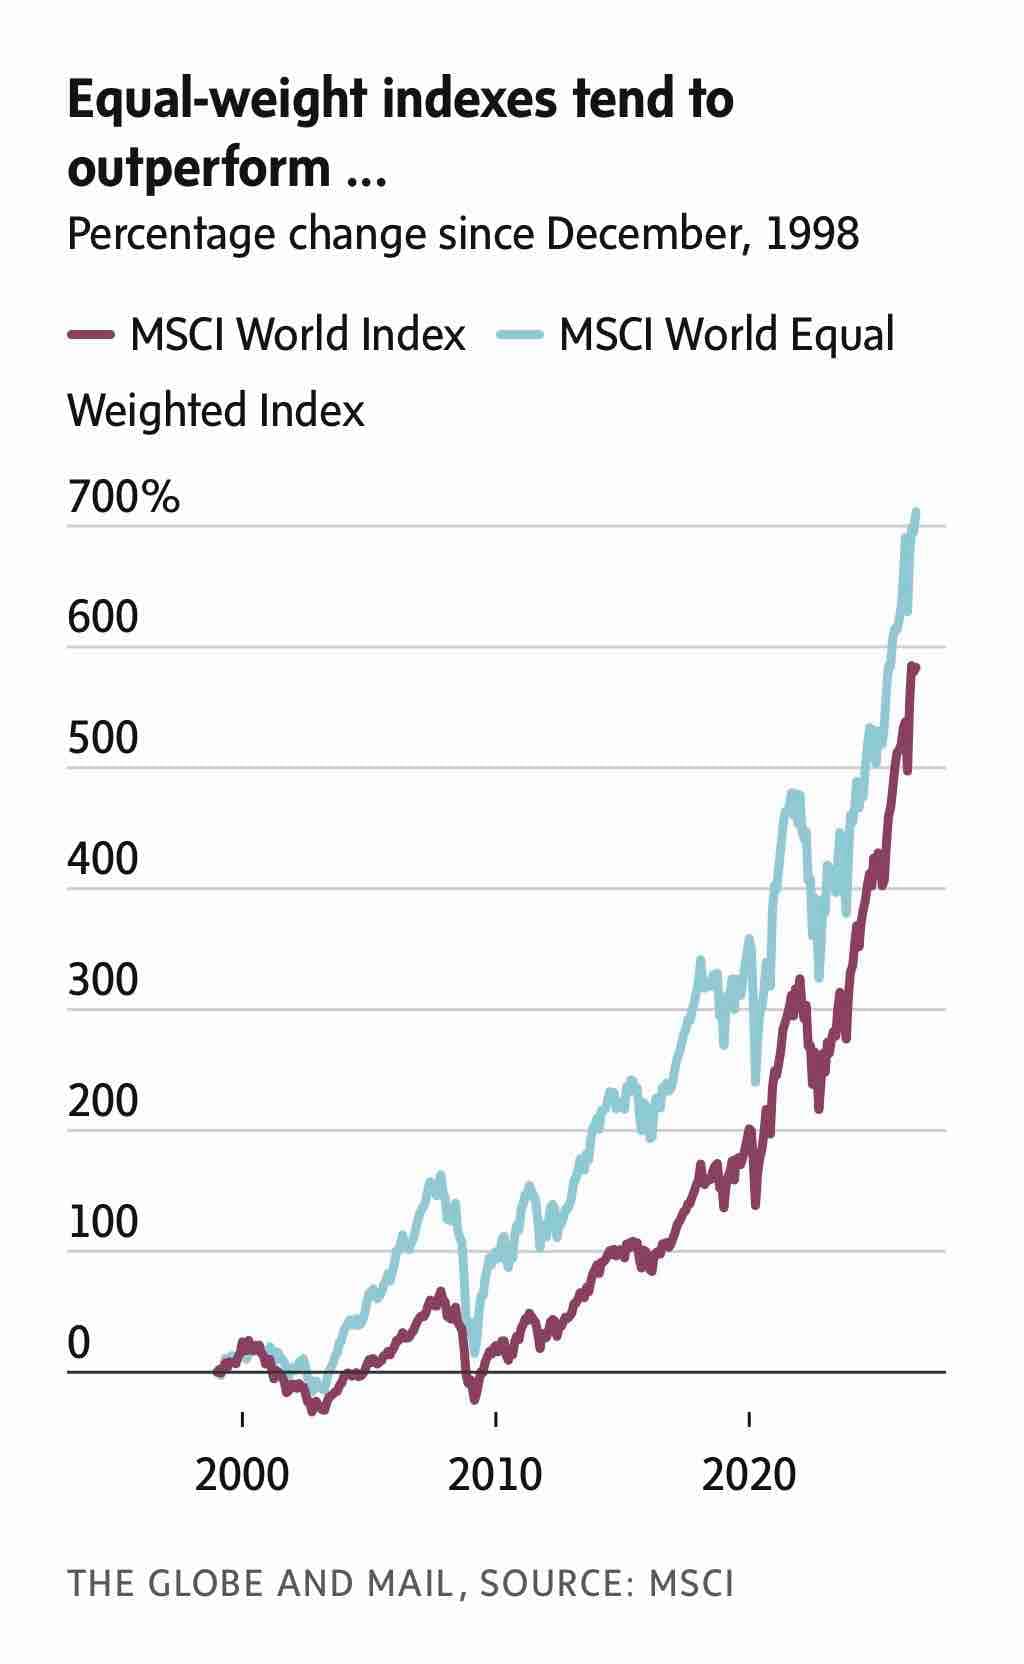
Hi there! My name is Andrew Galbraith, and I'm a reporter with The Globe and Mail in Vancouver. I usually write about stories at the intersection of markets and personal finance. I also write "Investor Clinic", a weekly column in which I do my best to try to help readers with their investment questions. I had a chance to check out BlossomCon last weekend and to meet people like @maxstocks, @joyeeyang, @crazycanuckinvestor, @zac_hartley and @coveredcalletfinvesting. I was impressed enthusiasm of the community here. While I'm not ready to share my own portfolio, I thought I might start by sharing my column. This week, I looked at the question of a reader searching for an equal-weight global equity ETF, which doesn't exist in Canada. Research suggests such an ETF would do well over time, but are there are costs to it -- and alternatives that might offer similar advantages. Here's a gift link - no Globe subscription required: https://www.theglobeandmail.com/gift/abf033097f2aee7cc380b493716e784abcd3170694bf0ae4c6f2ccb5a67962f4/FWFNKGXPSJCNNPDVUE4F6BLICA/ What do you think? Do you find the research compelling? Let me know - and feel free to share your own questions. I'll try to tackle them in upcoming columns!
2,590 views
24 Comments
Catherine @ffcatherine · 13d
Hi Andrew it was nice meeting you at the event in Vancouver 🙏🏻 Yes this is a great community of like minded investors
Ronan @ronan · 13dEdited
Welcome to Blossom A global equal weighted ETF like that would be very impractical to implement. While it would be nice to have it available, I doubt any of the fund managers will try implementing one soon The constant rebalancing required to keep it equal weighted would be a logistics nightmare. You’re basically always trading against the momentum of the market. Whatever sector is performing best, you have to rebalance against it to keep weighting equal. I’m guessing the MER+TER combo would be quite high leading you to actually underperform the benchmark anyways. That’s not what investors want in an “index” approach to investing. Like you said in the article as well, there may be periods of under/overperformance so why not buy the global market as is? It’s much simpler and likely not worth the effort
ETF Go@etf.go · 9d
Was there a time limit on the ‘free’ access? 😂 Great to have you here! Hopefully you’ll stick around and share some stories and insights. 🤞 As others have suggested - EW Indexes were the first attempt to break the periodic concentration risk that arises in MCap Indexes. Since then - Index strategies have continued to evolve and get smarter via Fundamental Indexes, Smart Beta Indexes and now Factor Indexes. There will certainly be times that EW Indexes lead the pack (when LgCaps falter or SmCaps boom) but personally I’d trust the research that shows the more persistent nature of Factors. That said - ‘strategy diversification’ could be seen as the 3rd/4th pillar of diversification (Asset Class, Region, Sector) so personally I see benefits to taking a ‘best of all worlds’ approach for those who want to periodically rebalance. Every strategy will have its day in the sun. We just don’t know which will rise/fall or when but we can take a broader blended approach and potentially smooth out some of the bumps. 👍
Ian S@ian_s · 12d
Great piece, Andrew, welcome to the community, and thanks for sharing it as a gift link. I’ll admit I read this one as a factor guy rather than an equal weight guy, so my take is slightly sideways from the column’s framing. My portfolio leans heavily on Avantis and Dimensional funds ($CAGE, $DFAX) rather than anything equal weighted, and I think that’s actually the more useful alternative for Canadian readers than trying to synthesize equal weight exposure from pieces. The appeal of equal weight is really about deconcentration. But systematic factor funds solve that same problem differently: instead of mechanically forcing every holding to the same weight and rebalancing back to par on a schedule, they tilt the portfolio toward smaller, cheaper, more profitable companies as a continuous process. Both attack concentration risk, but for different reasons, and I’d argue the factor route also picks up expected return premia that a pure equal weight index isn’t designed to target at all. Would be curious whether you looked at Avantis or DFA products at all while researching this, or if the column was scoped specifically to equalweight products.
See the full comment section 👀Sign up for the full Blossom experience!