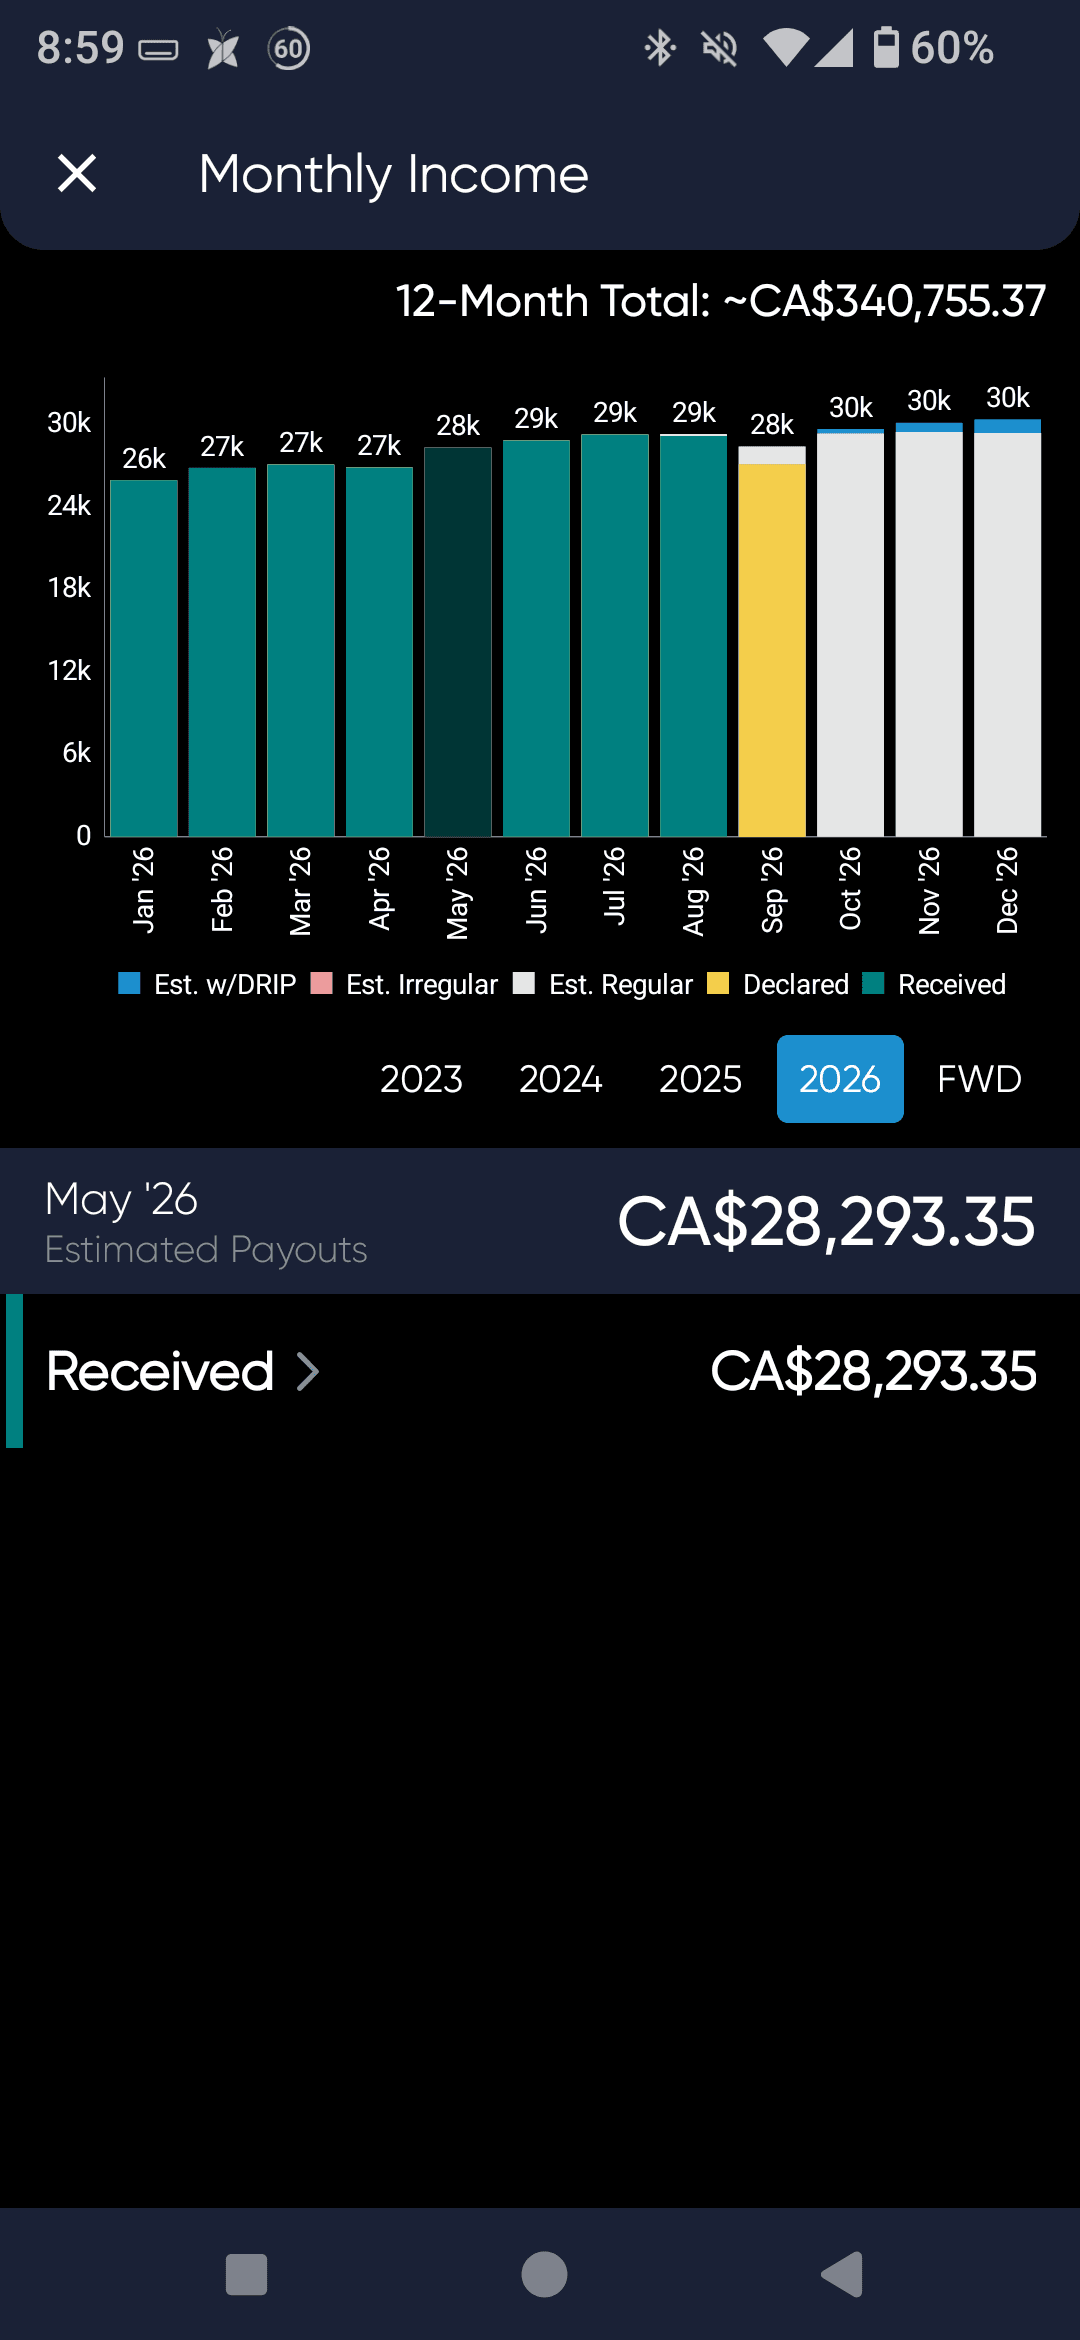
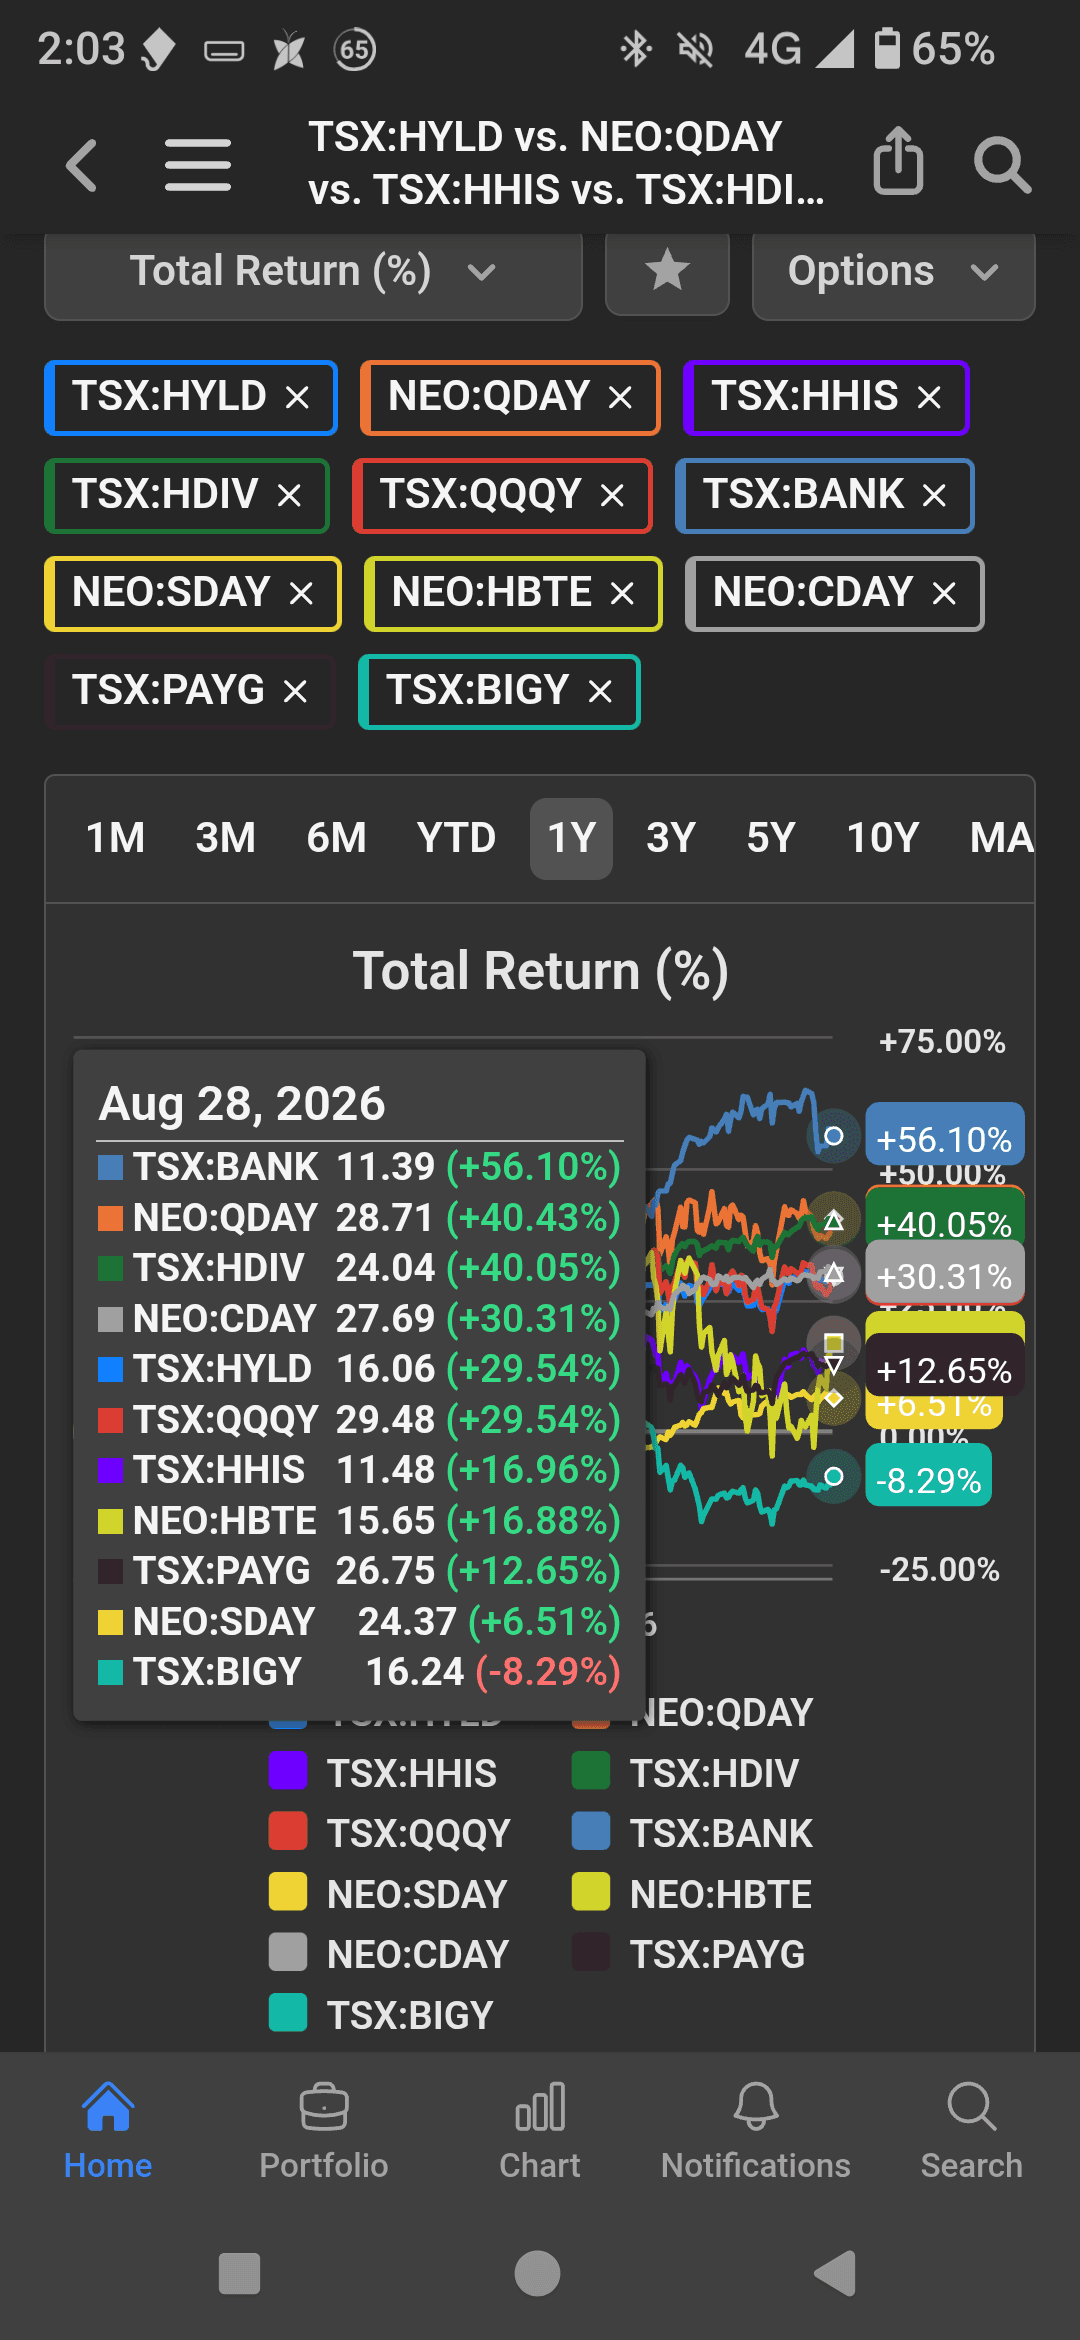
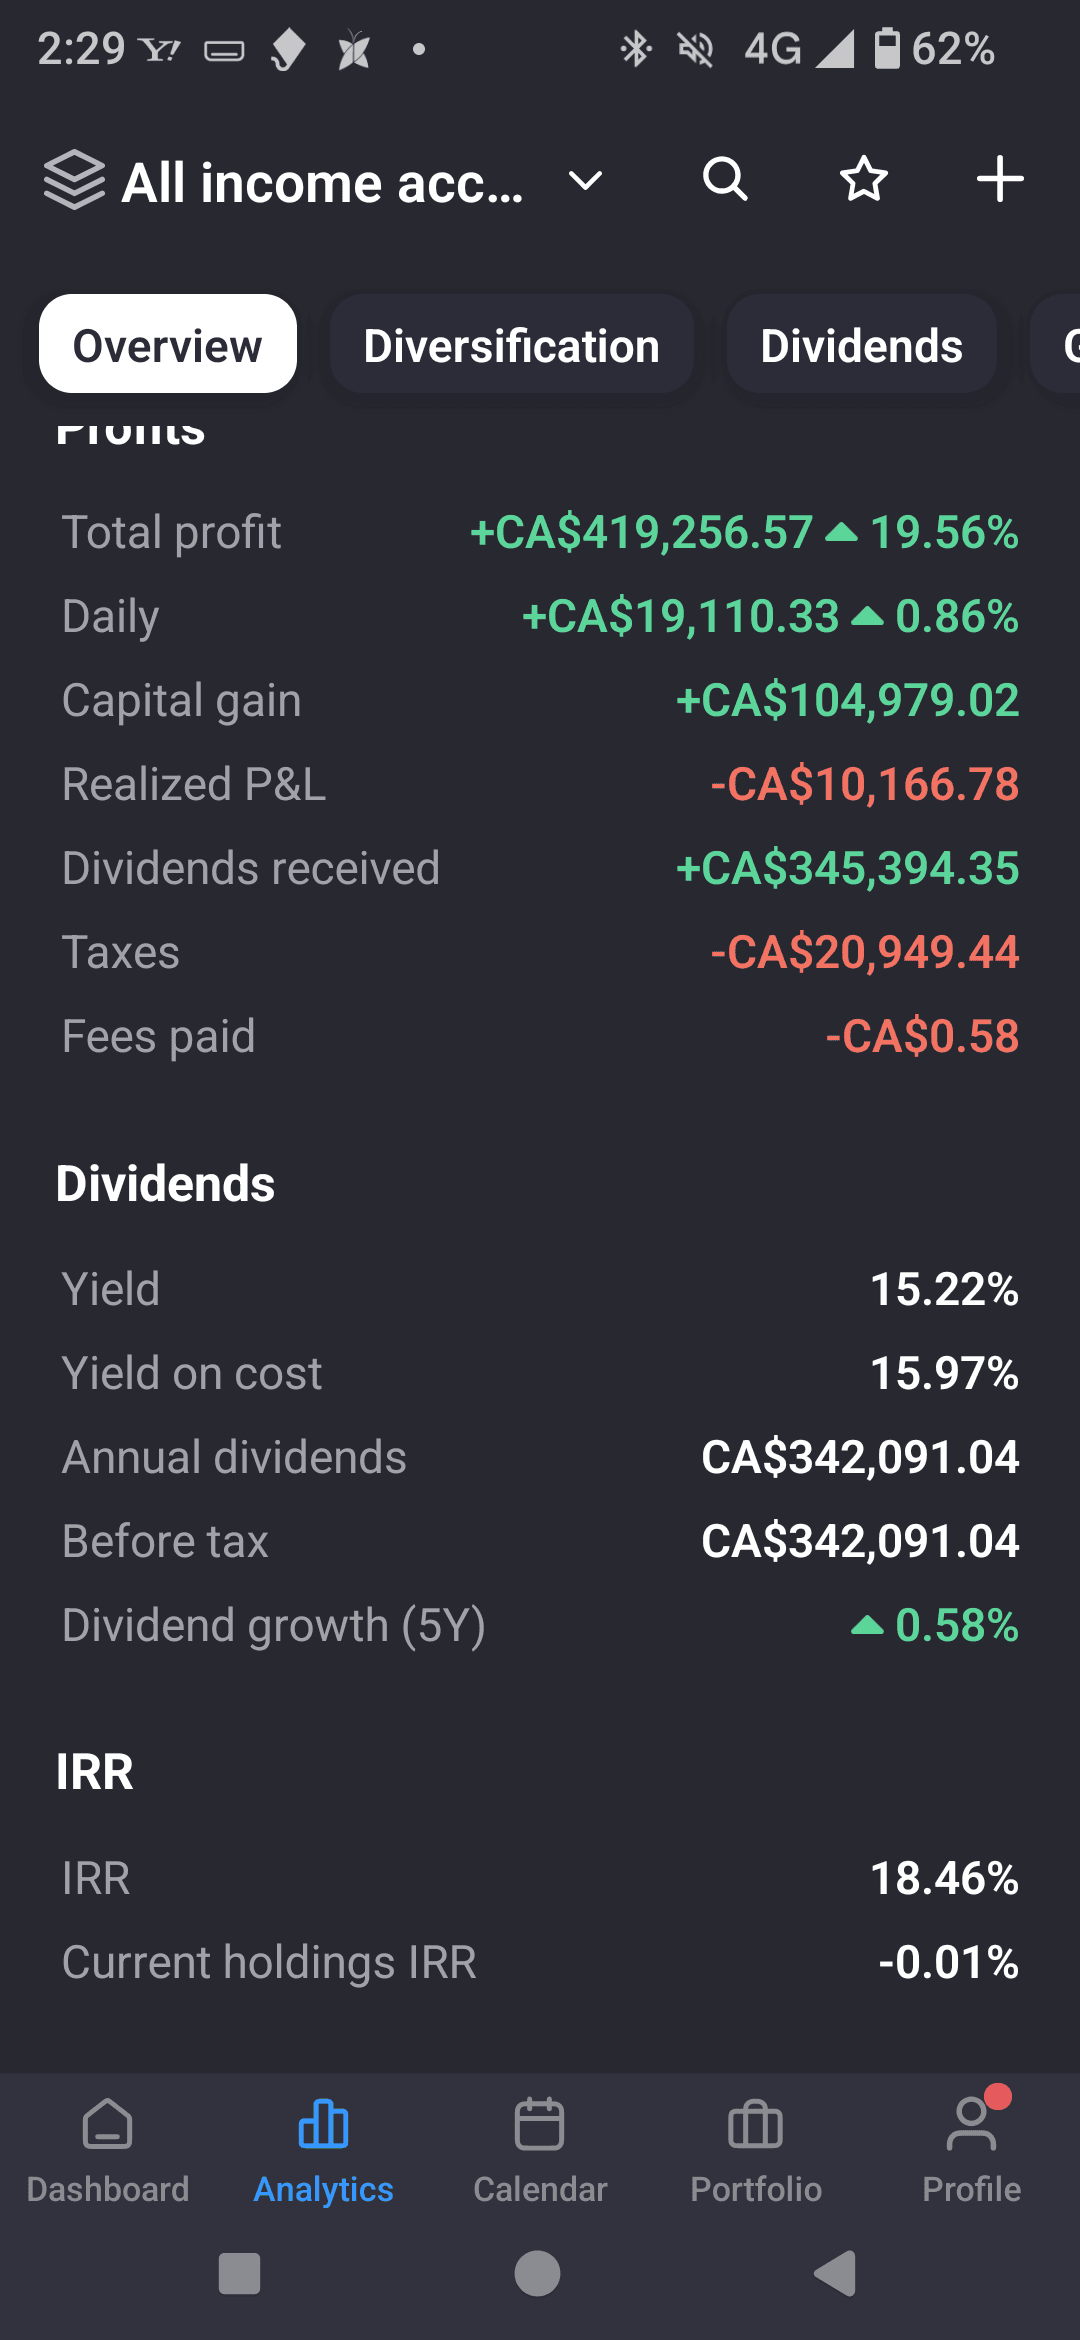
After the $BIGY distribution cut for Sept 2026, @canadianinvestor wrote about imagine some guy dropping $100K at launch? Well, I'm that guy. I picked up 4000 shares @$24.95. It was a leap of faith move when I needed more income. What could go wrong with a $HHIS but with more leverage and option coverage? $bank and $qqqy have been great, right? Crypto winter was just lurking around the corner. Yes, I will have to deal with an unexpected drop of $1000/month. If I zoom out, the drop will only set me back to about May 2026 level. Since I only withdraw ~70% or $20K, this is not the disaster the peanut gallery was hoping for. Short term plan: -Don't panic sell to lock in losses. -Use income from my TFSA if needed. This is advantageous for now as a non-permenant tax resident of Japan. -Spend less. I spend about 40% on non-essential stuff. -Wait until new LIF amount is known in Jan 2027. Squeeze more from RRIF and LIF as per my withdrawal priority stack. Longer term lessons: -Maybe 50% coverage and 33% leverage is outside of my model of total return - yield > 0 -Diversify and always be buying and pruning. Income was increasing before this unexpected drop. -Overall income portfolio is working. $$HYLD$HDIV$QDAY$SDAY$QQQY @etf.go fyi
2,250 views
18 Comments
yield @yield · 14dEdited
Well explained 👏. What some people don't understand is... they just see the price chart... 🤦🏻♂️ TOTAL RETURNS MATTER
Kar Yung Tom@karyungtom · 14d
Always love the transparency Ed.
Robert Guay@stuckincalgary · 14d
Lots of people bought Nike and took a much bigger loss and had no dividends
Canadian Investor@canadianinvestor · 14d
The same thing happens to someone who may have $100k in Telus or someone who bought $100k worth of speculative space stocks. In the run-up to the SpaceX launch, a ton of the space sector ran up. Some of those growth stocks are now down 50–60% from their highs and they pay no distributions and that drop is over 3 months not 11. No one knows what the future will hold. That said, an extremely high distribution rate can mean that even if total return remains positive, you may have to reinvest some, or potentially all, of the distribution if your goal is to maintain your capital over time. Closed-end funds have been around for more than 100 years. Many use derivatives and some have paid extremely high distributions. They also have other mechanisms available to manage their capital and distributions beyond simply writing covered calls but they have a longer history so people can learn from that. There is also a lot of innovation happening in the covered call ETF space. Fund companies are trying to figure out ways to mitigate some of the known risks. Some will successful some wont. Some might go through rough periods and then recover BANK was not doing well launching in 2022 when rates were aggressively being raised and now people conside it to be one of the better funds as the banking sector has been on a monster run. If tech runs again people may say the same thing about HHIS and BIGY the added leverage could push returns higher 🤷♂️
See the full comment section 👀Sign up for the full Blossom experience!