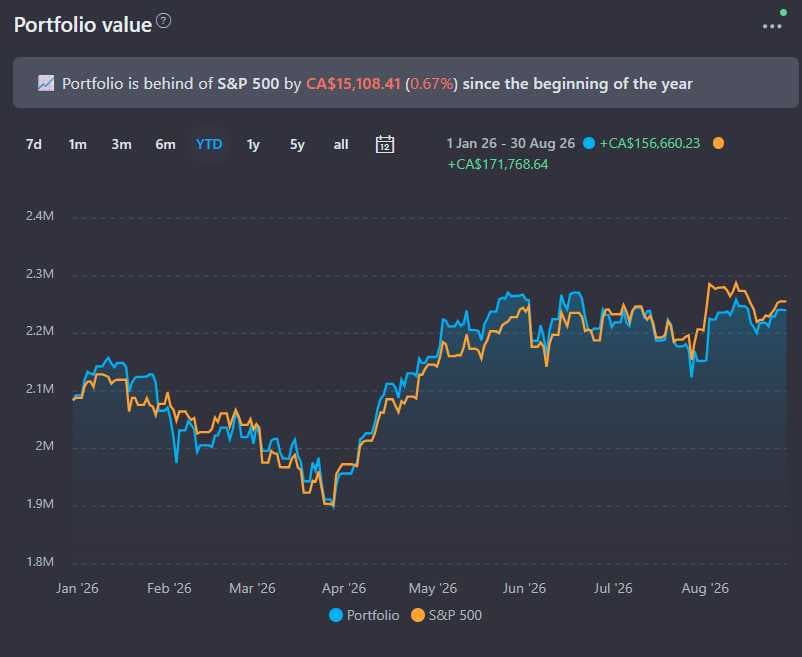
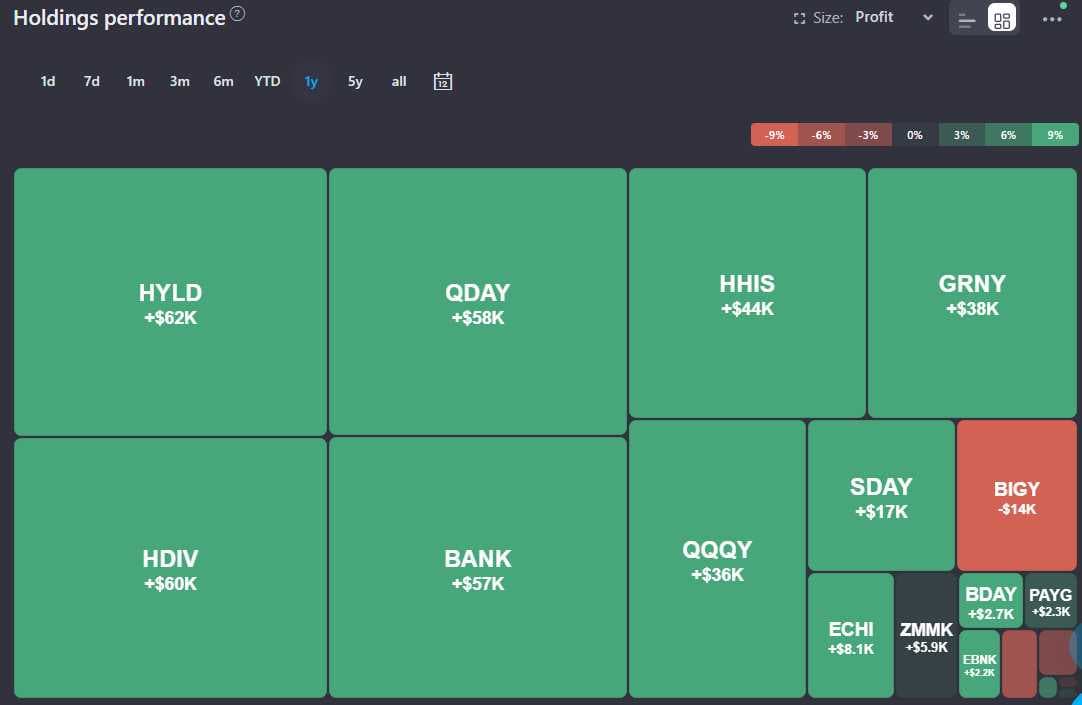
A dogma is defined as a principle or set of principles laid down by an authority as incontrovertibly true. In the retirement space, no dogma is bigger than the 4% safe withdrawal rate. Withdrawal rate I previously posted on how the 4% SWR is obsolete. The macro environment is different now. A sustainable portfolio is not determined by withdrawal rate alone. Investment return must be large enough to cover the cash flow. In Bengen's study, the long-term nominal return of a 50/50 portfolio is 8.3%-8.7%. 4.3+% of your portfolio after withdrawal each year is a lot of money left on the table. Are the low-cost index bros compounding this annual opportunity cost to 30 years from now? 1.043^^30=3.54. You're welcome. The number to monitor is the delta of rates between return and burn. The return comes from your risk appetite. The burn has to cover your needs and wants. You admire a return, but cash flow buys food. As per Snowball, my income portfolio is delivering 18.05% IRR and 16% yield on cost, or 89% monetization efficiency. I use about 70% of the yield. To me, the high MER in cc ETF is worth it. I cannot DIY this result. Life design > "Success" In Bengen's study, success is defined by not running out of money 30 years later. In most simulated runs, a 4% withdrawal will result in portfolios ending up larger. If the money is in an RRIF, how is paying 53% (Ontario) to the CRA a success? Dying with regrets, to me, is an utter failure. In retirement, you are managing two hourglasses: money versus healthy years. It is impossible to predict how a person transitions from go-go to slow-go, and from slow-go to no-go. But you certainly cannot go backwards to slow-go or go-go. There are obvious signs like unaffordable travel insurance or being unable to renew a driver's license. These come suddenly and unexpectedly. Will you be selling shares when you cannot even drive? My definition of success is living a rich life at whatever stage. Right now, it is bucket-list travel with my family. It also includes enabling my son's future in Canada, Japan, or wherever. In the go-go years, my life design requires more than a 4% withdrawal. This is why I invest the way I do. $HYLD$HDIV$QDAY$BANK$HHIS$QQQY$BIGY
5,916 views
55 Comments
Ed @edsam · 12d
Inspired by @piiverse video on Snowball AI, I also ran a test on my portfolio. I blocked out the projected values because they are irrelevant. Even in the P10 scenarios, the portfolio will still return $240K. For those in the peanut gallery betting on me eating cat food, don't waste your money.
Perry's PIIverse@piiverse · 12dEdited
very well said! for 2.5 years I have been retired and 90% of my retirement is funded by my portfolio AND my Income portfolio has been executing a 7-13% annual withdrawal rate from my portfolio... and my portfolio is not only NOT declining... its holding steady even with my portfolio over the last 9 months being hit with major Crypto sector declines which roughly 30% of my portfolio is in some way tied to. The 4% rule to me is bogus.
Kar Yung Tom@karyungtom · 12d
I don't understand this post, Ed. A lot of low-cost index "bros" like myself do not think the 4% rule needs to be literally applied. It's a max-safe historical number that leaves a lot of money on the table in many scenarios. My calculators show the same thing. "As per Snowball, my income portfolio is delivering 18.05% IRR and 16% yield on cost, or 89% monetization efficiency." I've always been consistent about this. Once you make an assumption about your portfolio's expected total return, volatility and future spending, then of course you can draw conclusions specific to those assumptions. You seem to assume we're in a new macro regime where higher liquidity, persistent deficits, and stronger nominal asset growth make historical withdrawal-rate assumptions too conservative. Sure, that can be your personal thesis. But that's very different from saying the people disagreeing with you simply "don't get it." Once again, too much salt. LMAO
Kyle T@kyletfreedom58 · 12dEdited
But what about the capped upside? 😁😉🤣🤣 Full disclosure: I'm being sarcastic 😁
See the full comment section 👀Sign up for the full Blossom experience!