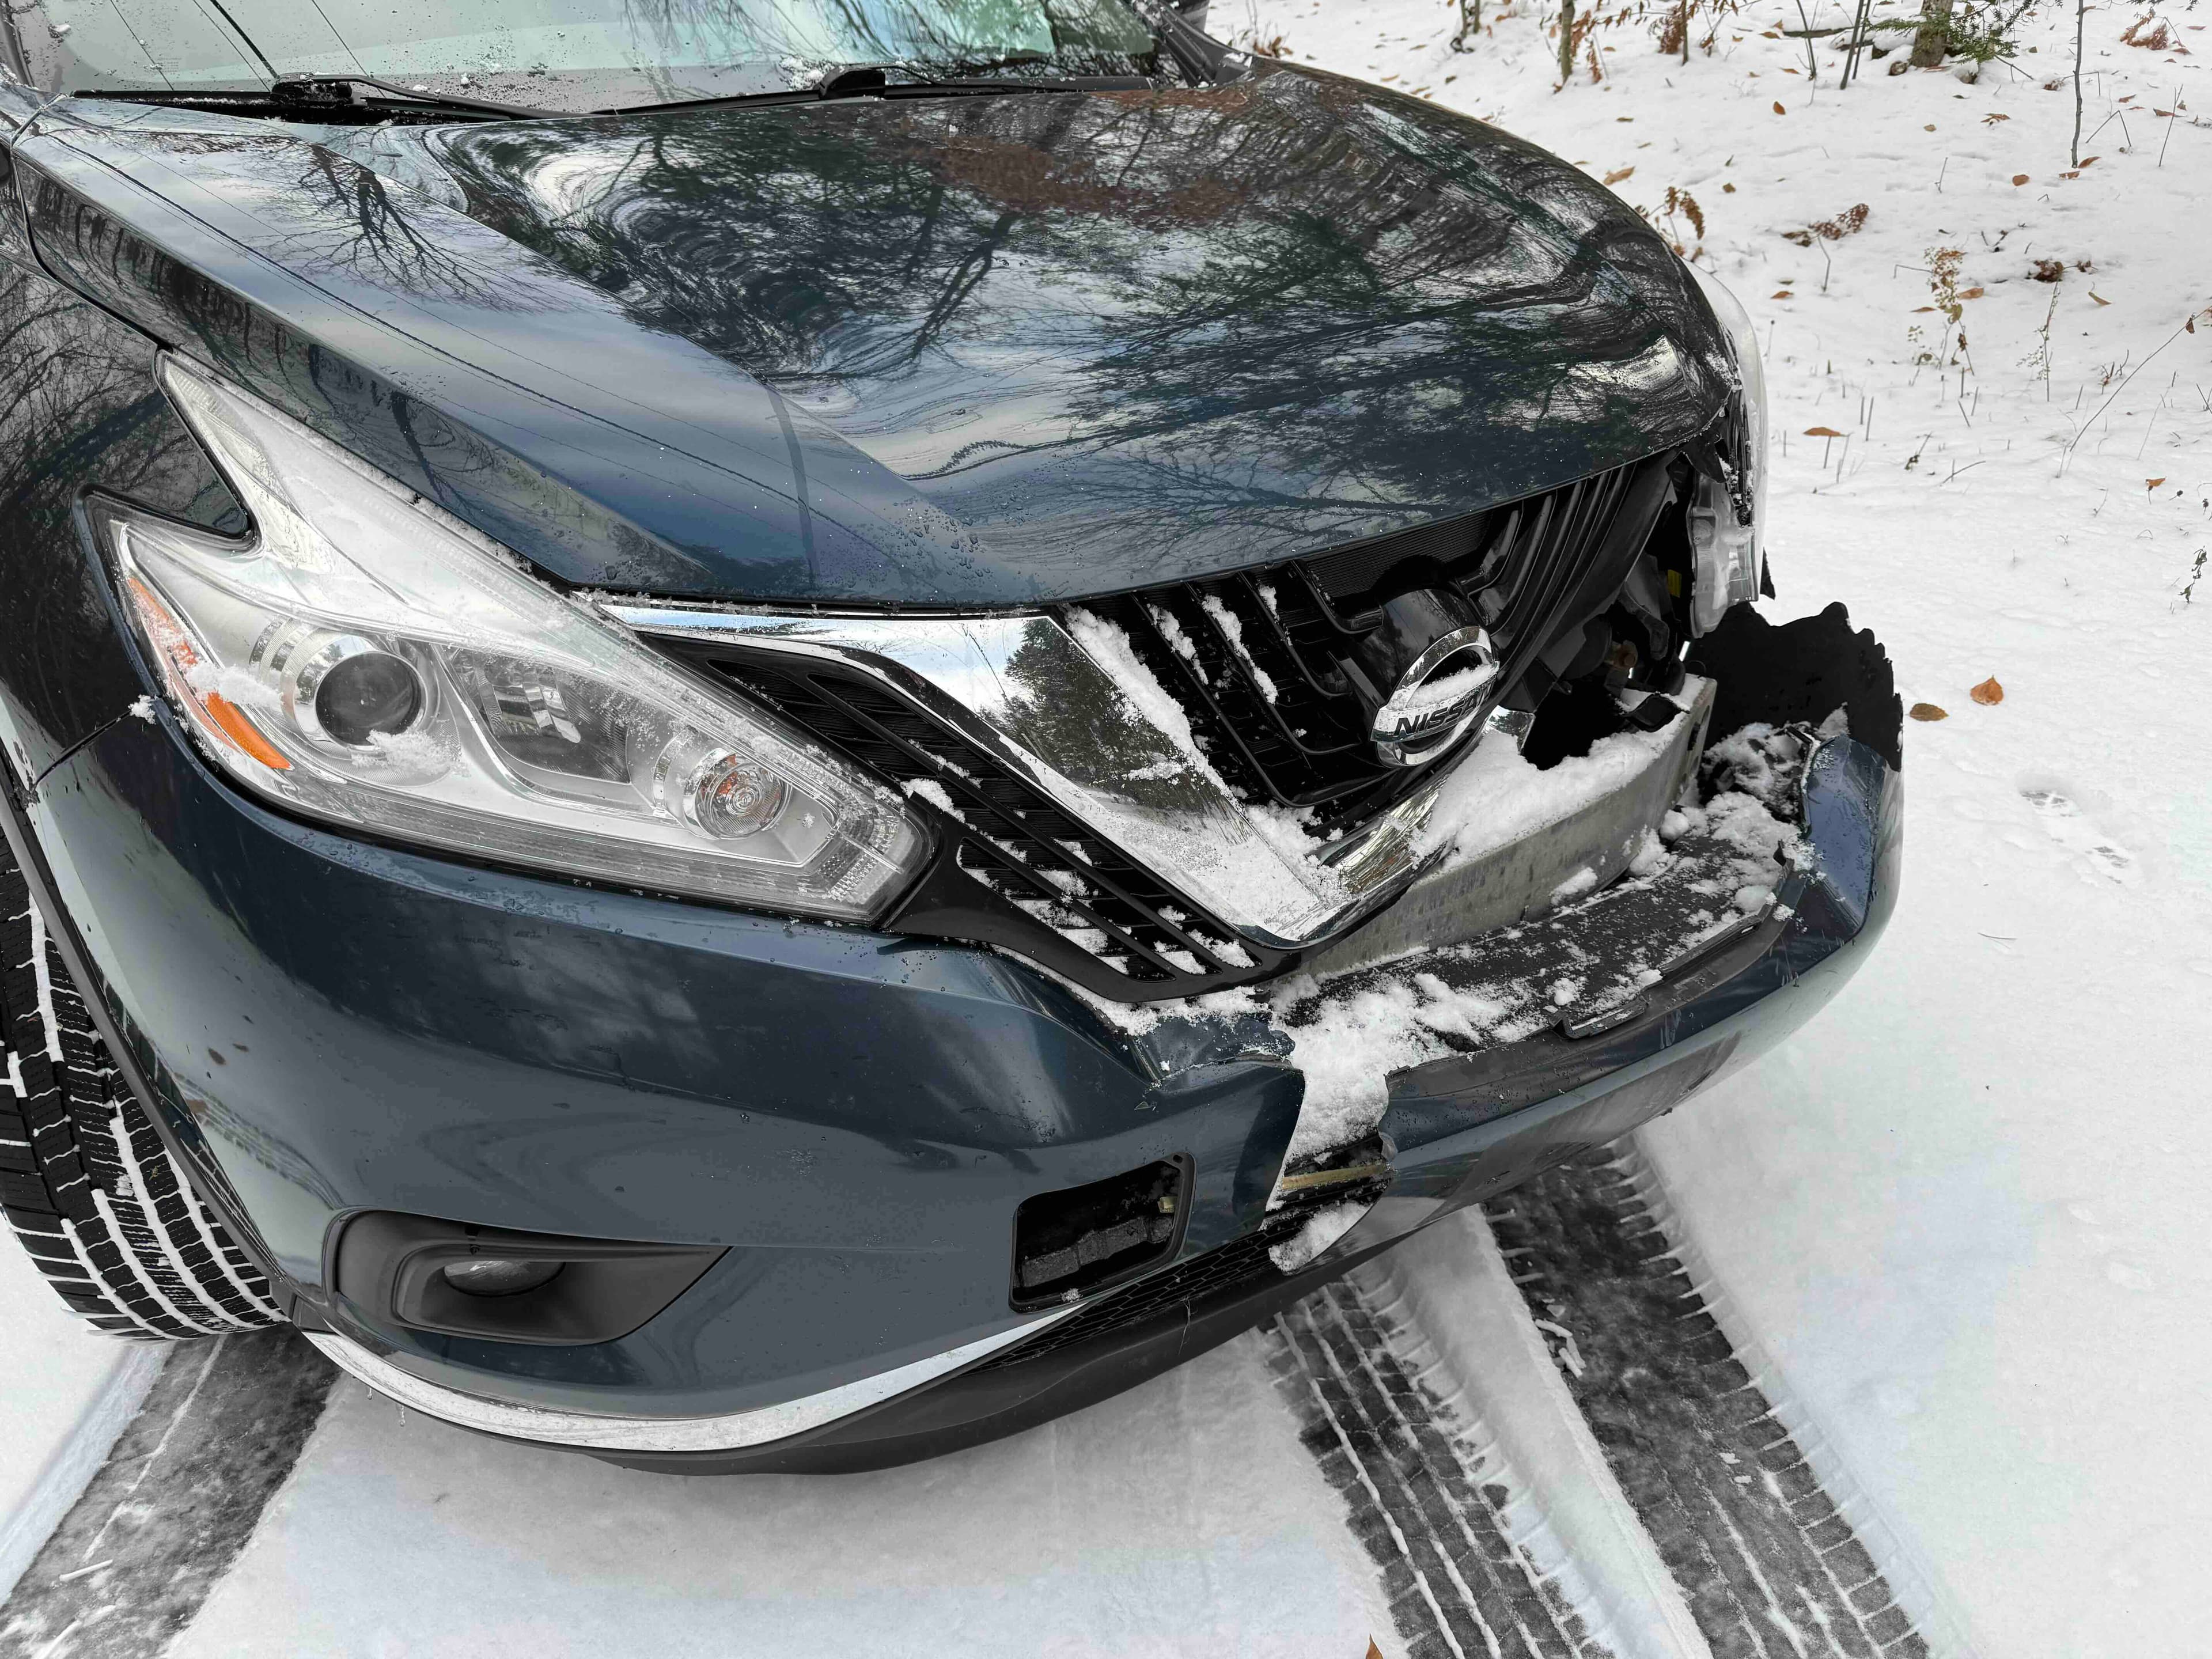
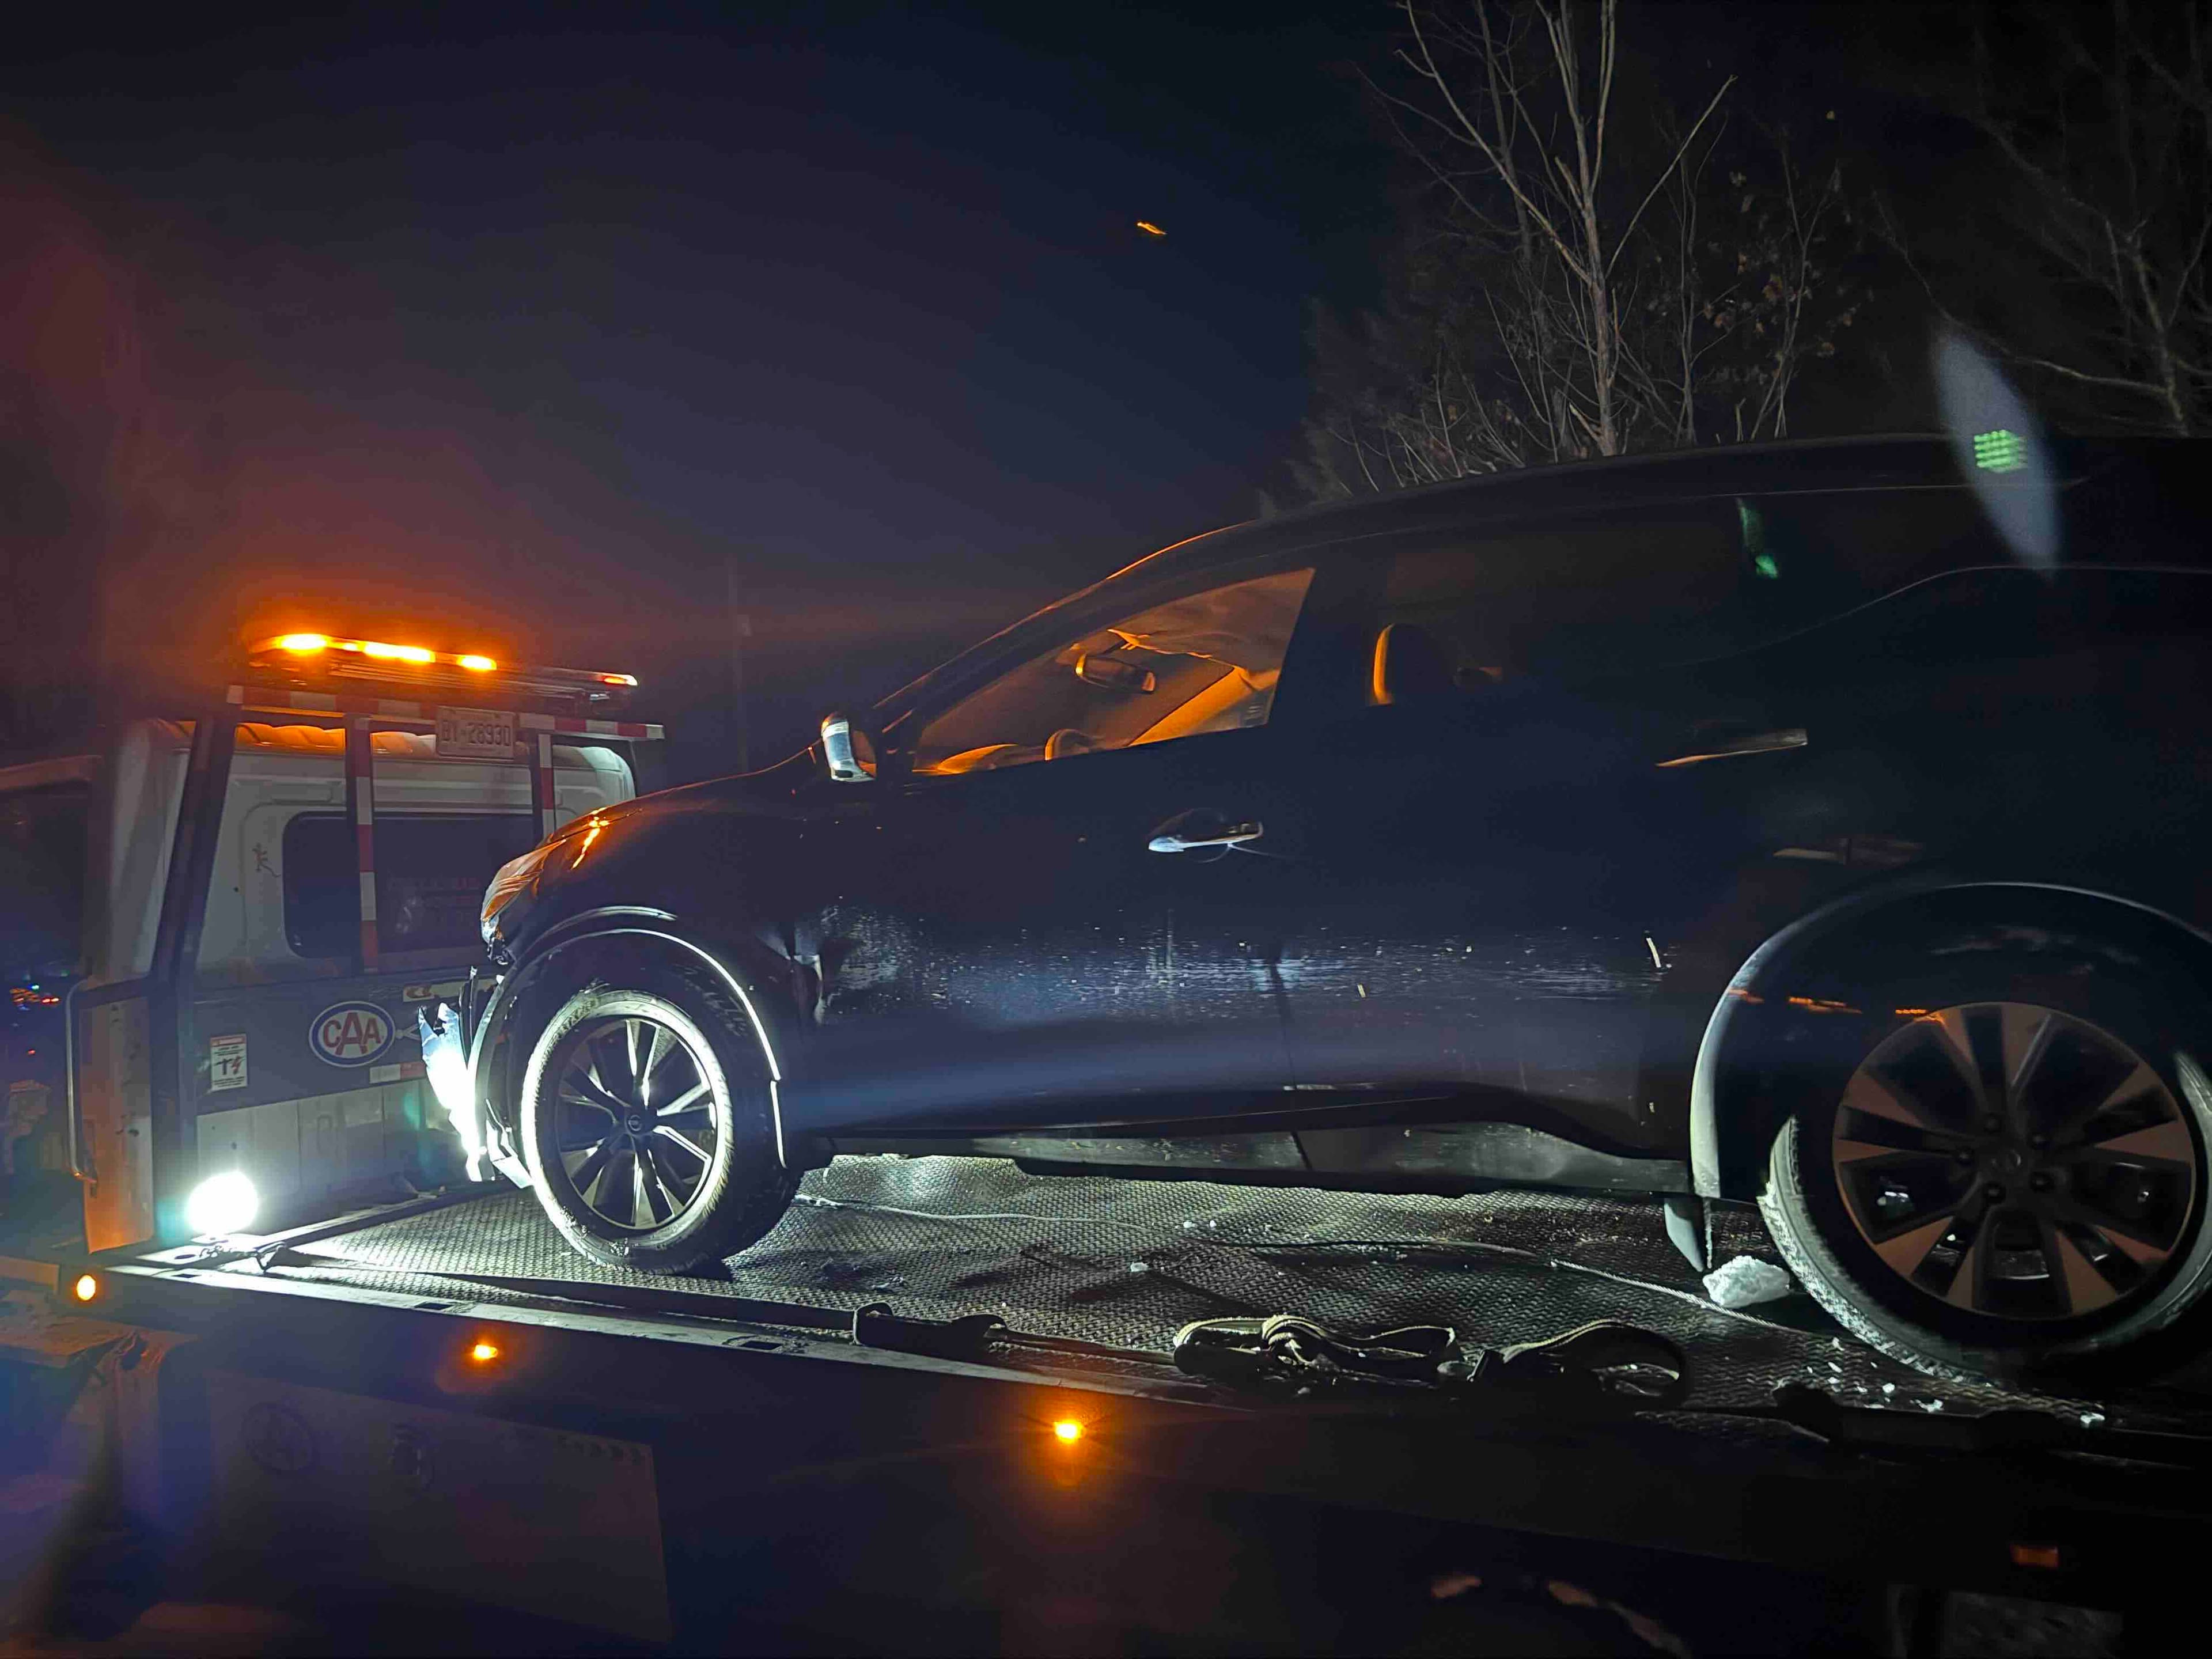
Two weeks ago - after pickleball of course - bad road conditions took my wife off the road with our SUV. 🚙💥👀 She’s fine - but being an older SUV (200k km) insurance effectively deemed it a ‘total loss’ and this week transferred the ‘fair value’ of $14k (not a bad result).🙌 Living in a rural area in winter requires good transportation so we needed to source a new vehicle assp and earlier this week we secured a decent replacement. Actually - I think it’s a pretty good upgrade (Lexus RX 350)! 😁 All of that said having retired just over a year ago these are the kind of ‘unexpected major expenses’ that you worry about. In some corners of blossom (PI) - there seems to be some strange narrative that in retirement it’s ‘hard to sell shares’ or ‘spend money’. I agree spending needs to be monitored based on assets/returns but I’m not sure where ‘selling is hard’ comes from? Usually it seems to be in the justification of high fee yield strategies - but all I can say is our experience was pretty seamless. There was no waiting on distributions. There was no mad rush to ‘panic sell’ right as markets were ‘crashing’ (-3% isn’t a crash). 😂 Our portfolio is naturally built to accommodate spending. In fact - I have specific positions that are ‘earmarked’ for different spending needs: $TCSH = Core Spending $ZST-L = Discretionary Spending $TBCG = Tax / TFSA Contributions $ZCON = Travel/Projects $XCNS = 2027 spend/emergency Even with above laid out - because I take a more tactical approach to my rebalancing - I had actually trimmed a number of positions recently based on volatility so we had ‘extra’ cash reserves which we could easily draw from. So in the end the car payment was just a simple transfer from our investment account to our bank account. 😴 In terms of ‘safe withdrawal rate’ the added amount will definitely put us above our targeted spending level ($120k) 🎯❌ for the year but given strength in markets these past few years we are well ahead of target (+$350k) so can easily accommodate the extra spend. ✅ I’m sharing all of this as another example of how investing/markets/ETFs can ultimately fund your lifestyle with out the need to rely on more expensive gimmicks. There was no need to rely on the dealerships financing options (5%-7%); or HELOC (4.65%); or High Fee High Yield ETFs (MER = 2%) 🤢 Respect the math on saving, compounding, protecting and withdrawing and you’ll likely find yourself in a fairly good situation. Even when crashes happen. 😉👍
26K views
75 Comments
le bib@le_bib · 11mo
It's funny. The same people who think selling shares means you'll go bankrupt because less shares = less wealth are ok with a 10-1 reverse split on cc funds. They see that 90% less shares means nothing to your wealth because the 10% remaining shares are worth 10x. But can't phantom that selling 4% of your shares that are increasing 10% in value annually won't lead to bankruptcy 🤷♂️
Twenty-five And Invested
@25andinvested · 11mo
One time, someone wrote my car off in a parking lot. I got way more than I paid for it..... not all bad days have bad outcomes
Mr Financial
@mr.financial · 11mo
Thankfully no one was hurt. Fire means nothing without health. I also love the lessons you share at the end about saving compounding, protecting and withdrawing. You help give some balanced perspectives for those in or entering a new stage in life.
Regis
@mytranslator · 11mo
The most important, your wife is fine. I love how you build your positions based on your spending needs!
See the full comment section 👀Sign up for the full Blossom experience!