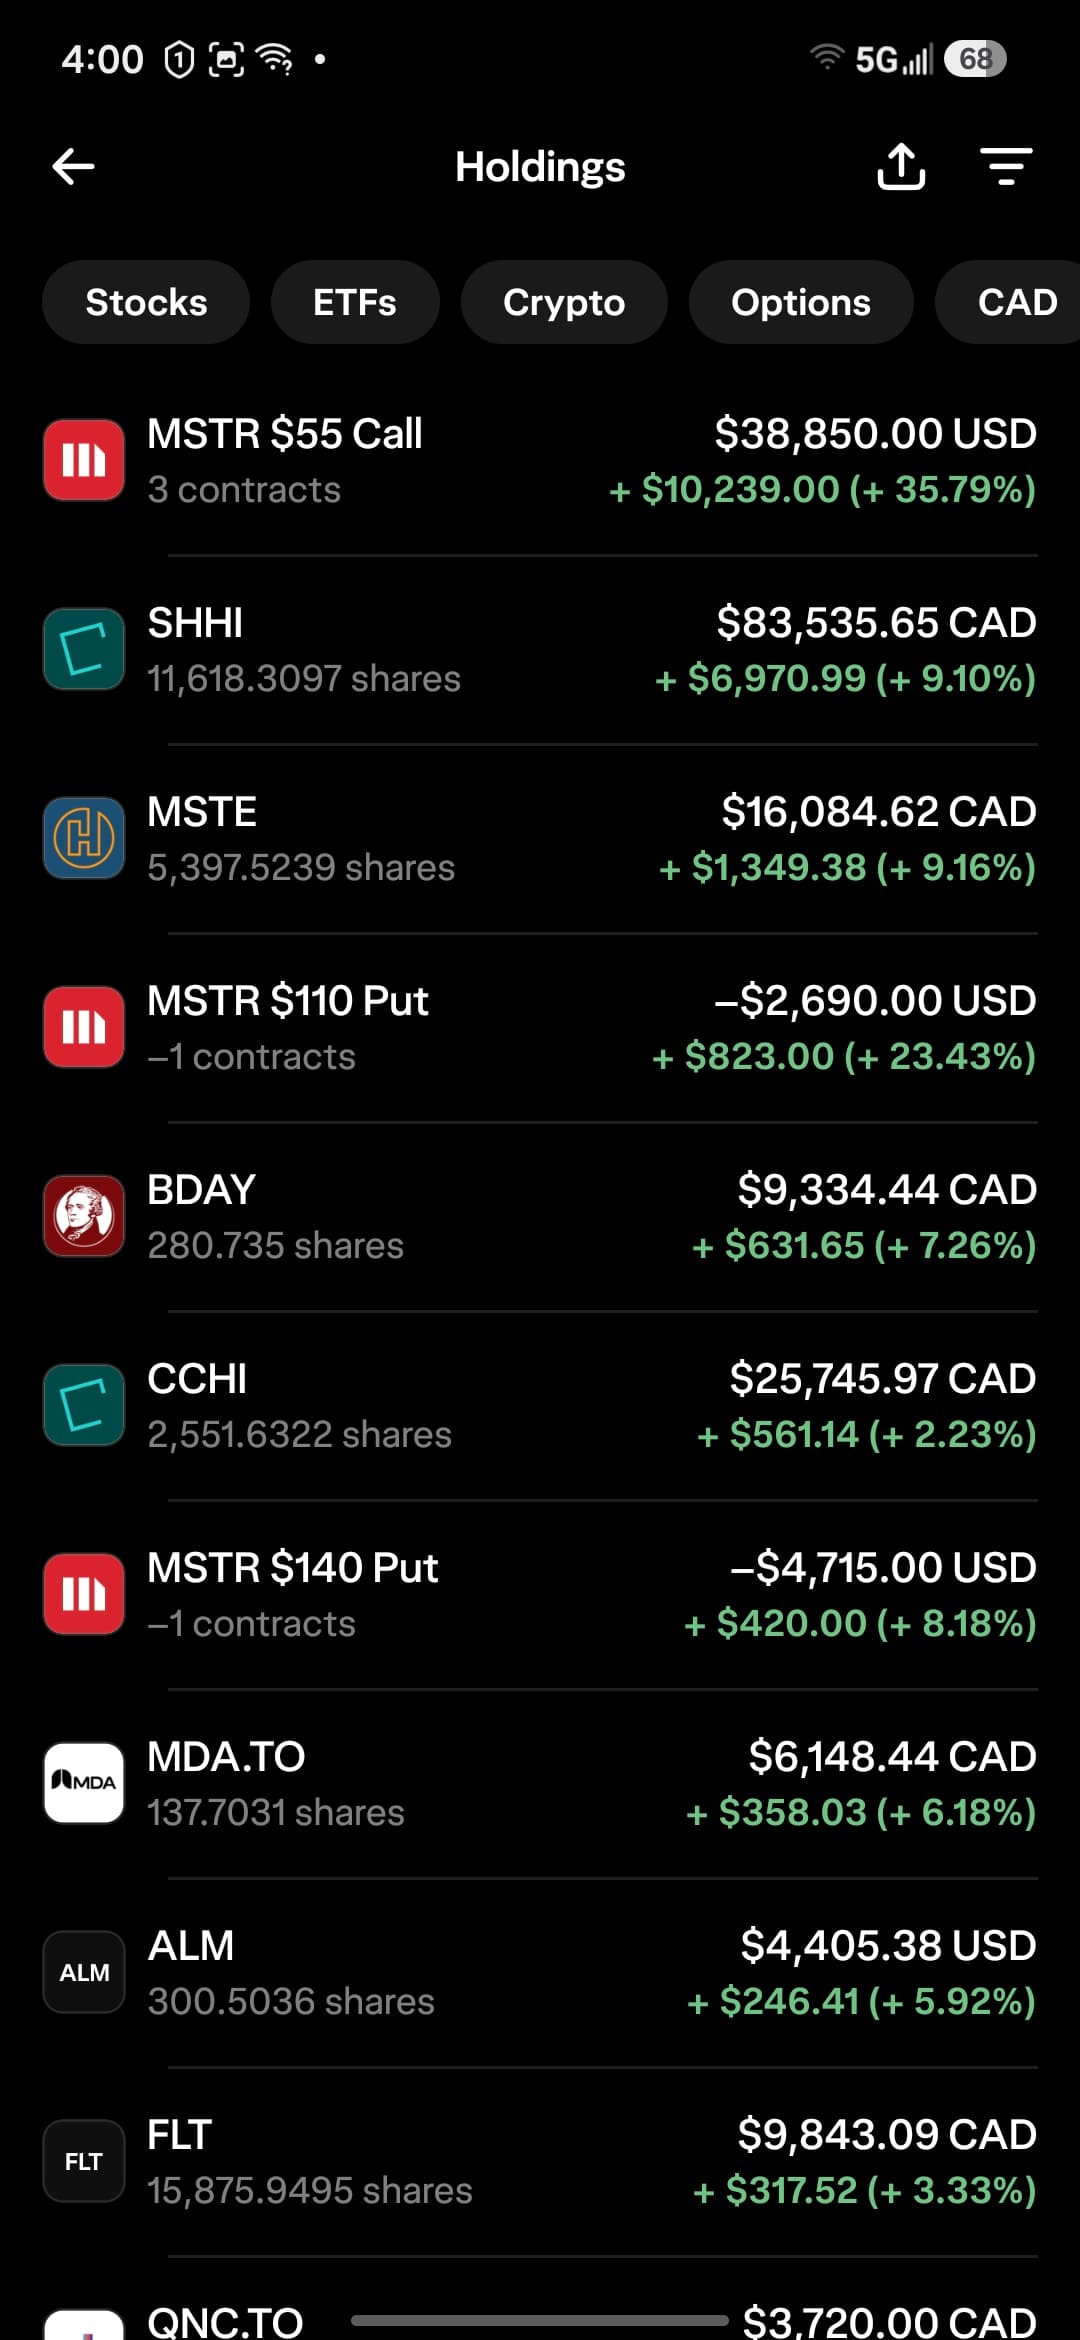
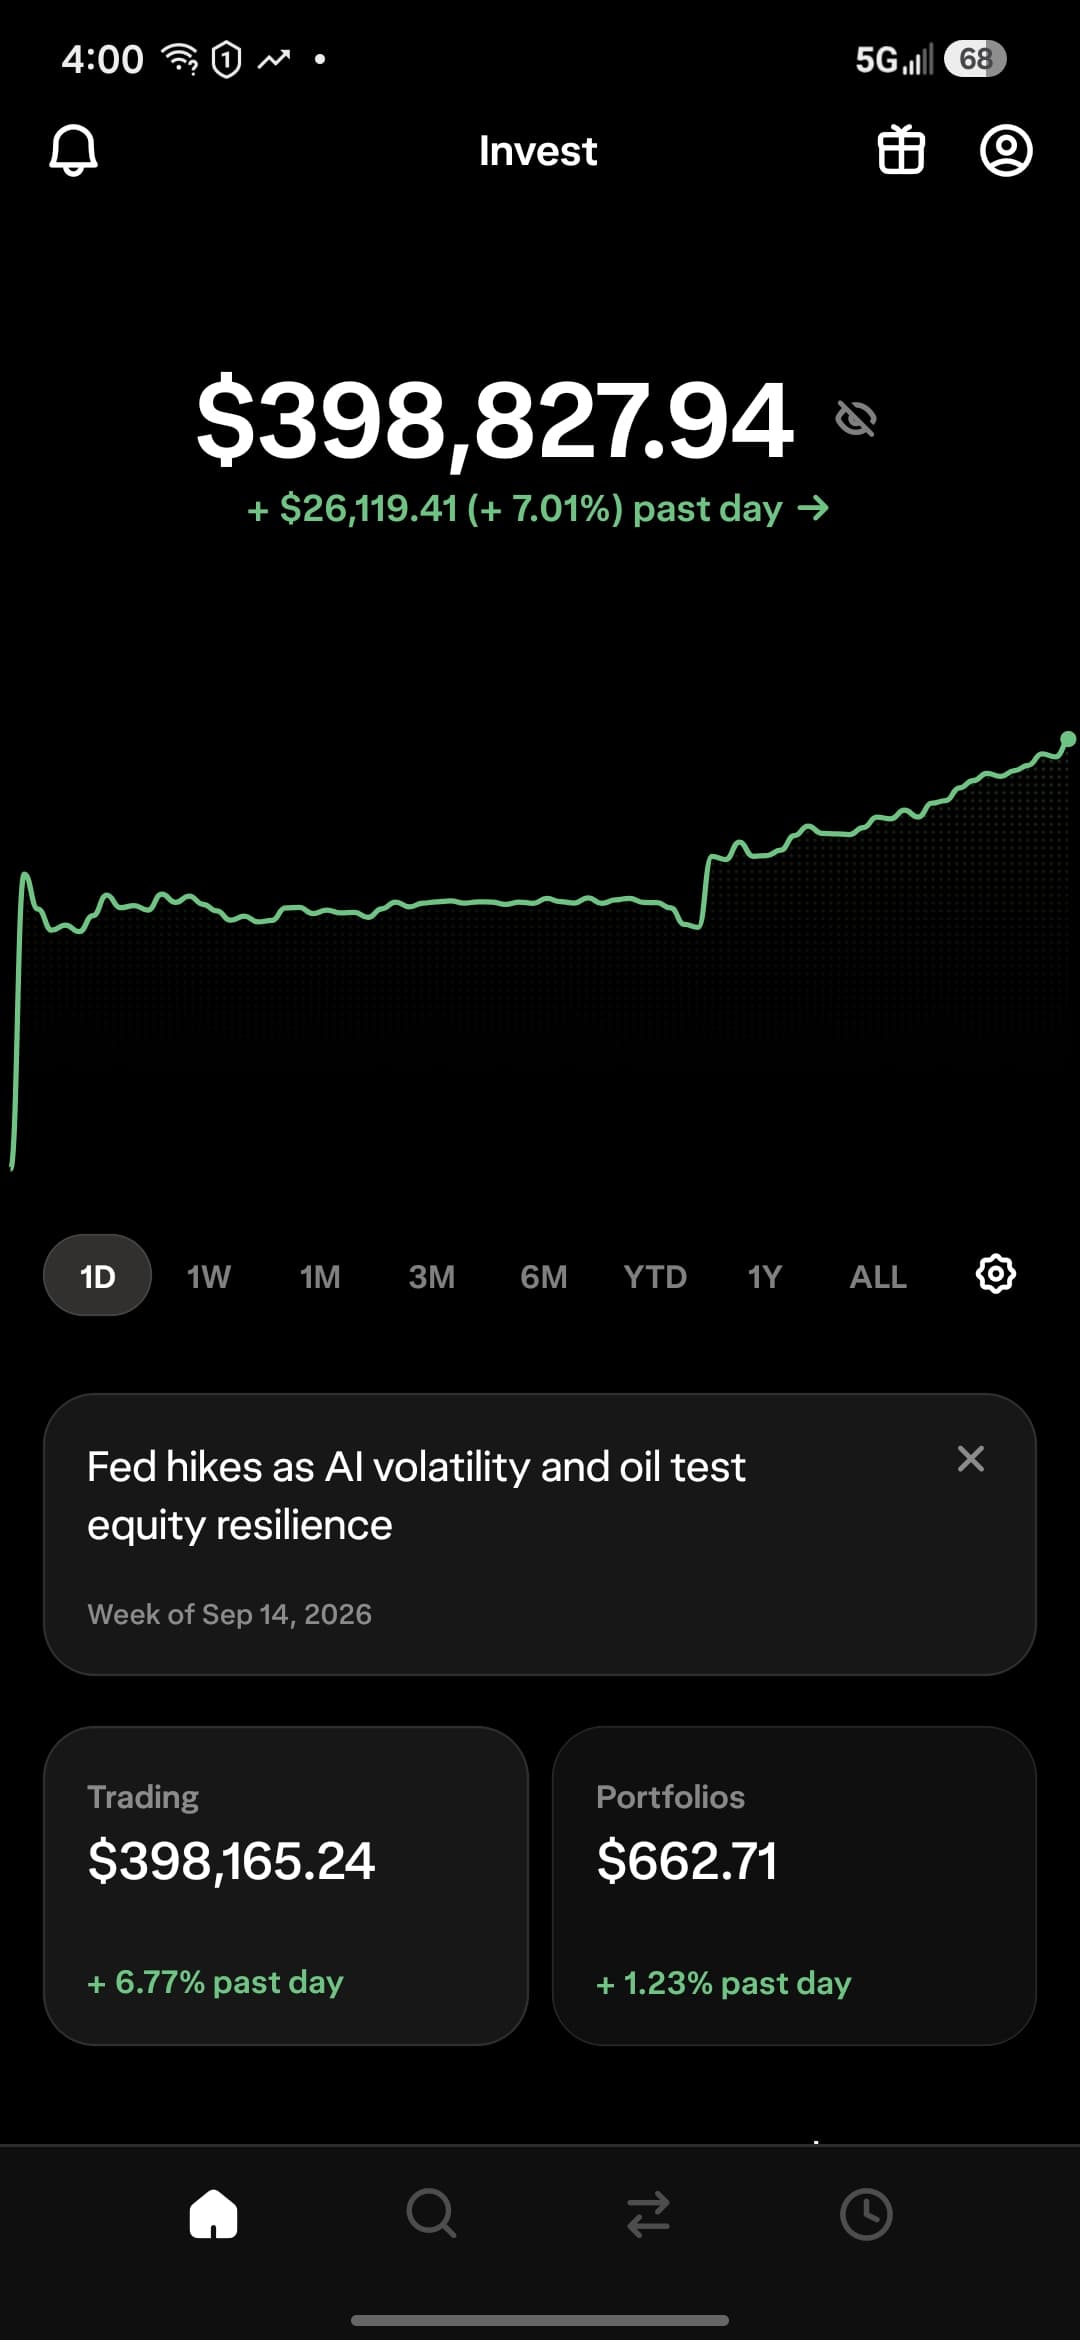
I'm currently 28 and I just did the math and for my FIRE goals I should be able to reach it at the current rate by late 30's to early 40's. How far are YOU from retiring / FIREing now? If you do vote or have an opinion what's your target $ amount before FIRE? $VOO$VFVread more
Another solid session with momentum plays paying. 👇 ☑ TSLA 390C — 0.55 → +125% 🔥 ☑ QQQ 741P — 1.36 → +125% 🔥 ☑ SPX 7750C (0DTE) — 2.35 → 4.20 (+79%) ☑ MSFT 520C (10/2) — 3.50 → 4.30 (trimmed, rest at breakeven) ☑ AMD 575P (10/2) — +10% (trim) OKLO 35p 11/20 @2.63 - still opened Notes: Took profits fast, respected stops, and let the high-momentum setups do the heavy lifting. TSLA and QQQ were the standout winners of the day. 🚀read more
Another solid day of trimming into strength and letting runners work. 👇 ☑ QQQ 735P — +100% (averaged-down position) 🔥 ☑ SPY 765P (4DTE) — 2.84 → 3.99 (+40%) ☑ AMD 575P — +30% (trimmed, stop moved to entry) ☑ OKLO 35P — 2.63 → 2.92 (+11%) • ➖ QQQ 738C — 1.53 → Scratch (closed early after failing to push 20%) ⏳ Still Holding - SPCX 10/16 Iron Condor (130/120 & 175/185) — Entry: 1.15 Notes: QQQ puts were the standout play after averaging down, while SPY kept paying through multiple trims before runners hit the lows. Stayed disciplined by cutting the QQQ calls when momentum stalled instead of forcing the trade. 🎯read more
Many investors assume they need to hit a magic $1,000,000 portfolio before they can retire or achieve FIRE (Financial Independence, Retire Early). But focusing solely on a single net-worth milestone can be misleading, retirement success is really about total cash flow. Did You Know? 🧐 The average new CPP retirement payout sits around $877 per month, far below the maximum limit of over $1,500. That gap is precisely why self-directed investment accounts (TFSA, RRSP, and taxable accounts) serve as the true engine behind achieving early financial freedom or maintaining a comfortable lifestyle in retirement. Recent data shows the median after-tax income for Canadian senior families sits around $83,200, with average CPP and OAS providing a baseline floor of roughly $19,500 per year for an individual. Instead of stressing over an arbitrary $1M target, the goal is generating enough reliable investment income to bridge your specific shortfall. Market Outlook With interest rate shifts and ongoing inflation, relying strictly on fixed income or holding large cash balances creates a real risk of losing purchasing power over time. For both pre-retirees and FIRE investors, market positioning is pivoting toward high-quality dividend growth, covered-call yield strategies, and total-return broad-market index funds. A disciplined withdrawal plan, backed by funds that raise cash distributions faster than inflation, helps preserve capital while ensuring steady cash flow during volatile markets. Key Funds & Tickers to Watch For (CAD) Investors 🇨🇦: * Dividend & High Yield: $VDY (Vanguard FTSE Canadian High Dividend Yield ETF) or $ENB (Enbridge Inc.) * Covered Call / Income: $TXF (CI Tech Giants Covered Call ETF) or $HYLD (Hamilton Enhanced U.S. Covered Call ETF) * Broad Market & Growth: $XEQT (iShares Core Equity ETF Portfolio) or $VFV (Vanguard S&P 500 Index ETF) For (USD) Investors 🇺🇸: * Dividend Growth & Yield: $SCHD (Schwab U.S. Dividend Equity ETF) or $JEPI (JPMorgan Equity Premium Income ETF) * Established Dividend Payers: $PG (Procter & Gamble Co.) or $O (Realty Income Corp.) * Broad Market & Growth: $VOO (Vanguard S&P 500 ETF) or $QQQ (Invesco QQQ Trust) How are you structuring your portfolio for retirement cash flow? Are you aiming for a specific net worth like $1M, or focusing on monthly income through dividend growth and ETF yield? — This is for educational and informational purposes only and does not constitute financial, legal, or investment advice. read more
On BNN, portfolio manager Stan Wong highlights a major risk many retirees overlook: Longevity risk, or outliving your money. When planning for retirement, shifting everything into cash or low-yielding guaranteed products like GICs might eliminate short-term market swings, but it leaves you vulnerable to inflation destroying your purchasing power over 25 to 30 years. To protect your lifestyle, keeping a portion of your portfolio in growth-oriented, high-quality equities is essential for long-term purchasing power. Did You Know? 🧐 At just a modest 2% annual inflation rate, a lifestyle costing $100,000 today will require about $181,000 per year in 30 years just to maintain the exact same standard of living! That's why keeping a growth engine in your portfolio is crucial. Here are ways CAD and USD investors can maintain that vital balance of growth, income, and stability: For US 🇺🇸 Dollar Investors (USD) * Broad Growth & Inflation Defense: $VOO (Vanguard S&P 500 ETF) or $SCHD (Schwab U.S. Dividend Equity ETF) provide growth and rising cash flow through top dividend-paying companies like Microsoft ($MSFT) and PepsiCo ($PEP). * Capital Preservation & Income: $BND (Vanguard Total Bond Market ETF), $SGOV, or short-term U.S. Treasury Bills to manage short-term liquidity without risking long-term compounding. For Canadian 🇨🇦 Dollar Investors (CAD) * Broad Growth & Equity Exposure: $VFV (Vanguard S&P 500 Index ETF) or all-in-one equity portfolios like $XEQT and $VEQT ensure your nest egg keeps compounding. * Dividend Growth & Defensive Income: $VDY (Vanguard FTSE Canadian High Dividend Yield Index ETF) for reliable blue-chip income from stalwarts like Royal Bank ($RY) and Enbridge ($ENB). — This is for educational and informational purposes only and does not constitute financial or investment advice. read more
🎣 Why is it so difficult to consistently outperform the stock market? Kar explains his “fishing hole” analogy and why competition in the market can naturally limit how much excess return an investor can capture. In Episode 21 of Financial KarMoe, @karyungtom and Moe dive into a wide-ranging audience Q&A covering some of the biggest questions investors face along their journey. We also revisit the debate around growth vs. income investing and why those labels often don't tell the full story. Instead of stopping at a label, Kar explains why it's important to look deeper at what someone actually owns and how they invest. 💸 We discuss milestone rewards and guilt-free spending. Should investors celebrate every major net-worth milestone, or is the psychological benefit of enjoying your money along the way more important than sticking rigidly to a savings plan? Moe shares how travel, family experiences, and creating memories have become meaningful ways to enjoy the journey. 🤝 One of the biggest “investments” discussed isn't a stock or ETF at all: relationships and networking. Kar talks about how building connections throughout his career—from Magic: The Gathering to investing and online communities—has created knowledge, friendships, and opportunities that money alone can't buy. 🔥 We then get into the idea of a personal “magic number” for financial independence. Moe discusses why age 50 is currently an important target for him, while Kar explains why having the freedom to spend more time with family could ultimately matter more than reaching a particular age or portfolio size. 📈 The conversation also gets into indexing, $XEQT, $CAGE , home bias, value investing, Bitcoin, MSTR, and individual stocks. Kar explains why having conviction in a simple, diversified strategy can make it easier to stay invested when the latest hot fund or asset starts outperforming. We also discuss what it actually means to consider active investing—and why having a reason to believe you know something the market doesn't may be an important starting point. 🍕 And, because this is Financial KarMoe, we couldn't finish without answering the important question: Do we like pizza? 😂 This episode is ultimately about much more than investing. It's about building wealth while still enjoying your life, understanding your own priorities, staying disciplined through uncertainty, and recognizing that financial independence is a means to create more choice—not simply a number on a spreadsheet. 💬 We'd love to hear from you: What's the one financial milestone—or life milestone—you'd genuinely celebrate along your journey? https://youtu.be/-XINF7P21Tcread more
As our economy goes through shifting interest rate cycles and structural transitions, keeping your long-term portfolio returns steady without taking on wild risks is the name of the game. Building a resilient strategy isn't about guessing the next market top, it's about staying disciplined and keeping your investment costs low. Did You Know?🧐 The "Rule of 72" is a quick mental shortcut to estimate how fast your money doubles! Simply divide 72 by your expected rate of return. For example, if your portfolio earns an 8% annual return, your money will double in roughly 9 years (72 \div 8 = 9). Plus, shaving just 1% off your annual investment fees can add years of growth to your retirement nest egg over a multi-decade horizon! Market Outlook Without high inflation, broad market baseline targets generally sit around 4% to 6% real annual returns over the long haul. However, with sticky living costs and ongoing economic adjustments, holding pure cash or low-yield fixed income risks losing buying power over time. To keep compounding strong through changing market conditions, focus on broad-based asset allocation, dividend growth equities that keep pace with inflation, and low-cost index funds that minimize fee drag. Key Funds & Tickers to Watch For Canadian 🇨🇦 (CAD) Investors: * All-in-One Growth: $XEQT (iShares Core Equity ETF Portfolio) or $VEQT (Vanguard All-Equity ETF Portfolio) * Dividend & Income: $VDY (Vanguard FTSE Canadian High Dividend Yield ETF) or $ENB (Enbridge Inc.) * Tax-Efficient Core: $VFV (Vanguard S&P 500 Index ETF) For U.S. 🇺🇸 (USD) Investors: * Core Market Index: $VOO (Vanguard S&P 500 ETF) or $QQQ (Invesco QQQ Trust) * Dividend Growth: $SCHD (Schwab U.S. Dividend Equity ETF) * Income & Value: $JEPI (JPMorgan Equity Premium Income ETF) or $O (Realty Income Corp.) How are you keeping your portfolio steady right now? Are you sticking with core index ETFs like $XEQT and $VOO, or leaning into dividend growers like $VDY and $SCHD to combat inflation? — This is for educational and informational purposes only and does not constitute financial, legal, or investment advice. read more
Currently sitting at $357,475 CAD, up 7.63% YTD. I’ve been investing since I was 18, and the biggest thing I’ve learned is how boring investing becomes when you actually start taking it seriously 😂 Most of it is just holding, consistently adding money, and trying not to make stupid decisions when the market gets volatile. Still have a long way to go. $400K is the next milestone, then eventually $1M. For anyone around the $300K–$400K range: did you notice compounding start becoming way more noticeable here?
Now with blossom we can post reels (bloom) this is going to be awesome ! I’ve been wondering for months now if this would be a reality and now it’s here ! I think with this feature blossom will get much more screen time and content creators can really get subscribers more easily. Now I’m wondering if creators will get paid through blossom ?? 🤔🤔🤔
Keeping an eye on $MTRN after a sharp two-session selloff despite record recent results, rising margins, strong cash flow and a raised full-year outlook. The fundamentals still look strong, but the stock’s big prior run and elevated valuation remain meaningful risks. There may still be details the market is pricing in that I haven’t caught yet; this is a watch, not a verdict.
Paychex ($PAYX), Airbnb ($ABNB), Frontdoor ($FTDR), and Scorpio Tankers ($STNG) are sitting below every earlier level on the board this afternoon, in that order.
Canada became our home in Sep’21. Below visual until Sep’26 is self explanatory. Thanks Almighty. The journey of learning continues. I am still making mistakes, I am still getting greedy, I still have a FOMO many a times, but community like #Blossom and education from various channels @adrian_pii@garygill@passiveincomagnet@moementumfinance@mountainfinance@marcb@oldfish@jessicamoorehouse and many others continue to help me learn and unlearn and relearn. 🙏. I only have gratitude. #time #invest #learn #fail #repeat
I’m new to DIY investing and the Blossom community. I’m currently working towards financial independence and actively investing in my RRSP and TFSA accounts. At the moment I have 100% of my RRSPs invested in $XEQT and plan to continue to invest exclusively in $XEQT for my RRSP account for the next few years. I have questions about my TFSA investments and have been thinking of either keeping things simple and also investing in $XEQT for my TFSA or if I should try something different. I’m considering investing a portion of my TFSA to either be (1) the big six banks, (2) $VDY , (3) consider a little exposure to something like gold or $BTC , or (4) keep it really simple and also just purchase $XEQT. Any thoughts, comments or experience others have would be appreciated. Thanks!
🏆 Top Win 🚀 META 690C — +91% (1.90 → +91%) ⚡ QQQ 707C — High-risk momentum setup with stops emphasized. 💎 META delivered the clean move of the day, while disciplined risk management stayed the priority.
I'm 35 and planning to leave Canada permanently in five to seven years, at which point I'd withdraw the entire TFSA before becoming a non-resident. Over that horizon I'm targeting roughly 8–10% annualized returns. My current portfolio is close to the mix below, with 5–10% in individual stocks and the rest in broad index funds. Before I lock this in, is there anything you'd change?