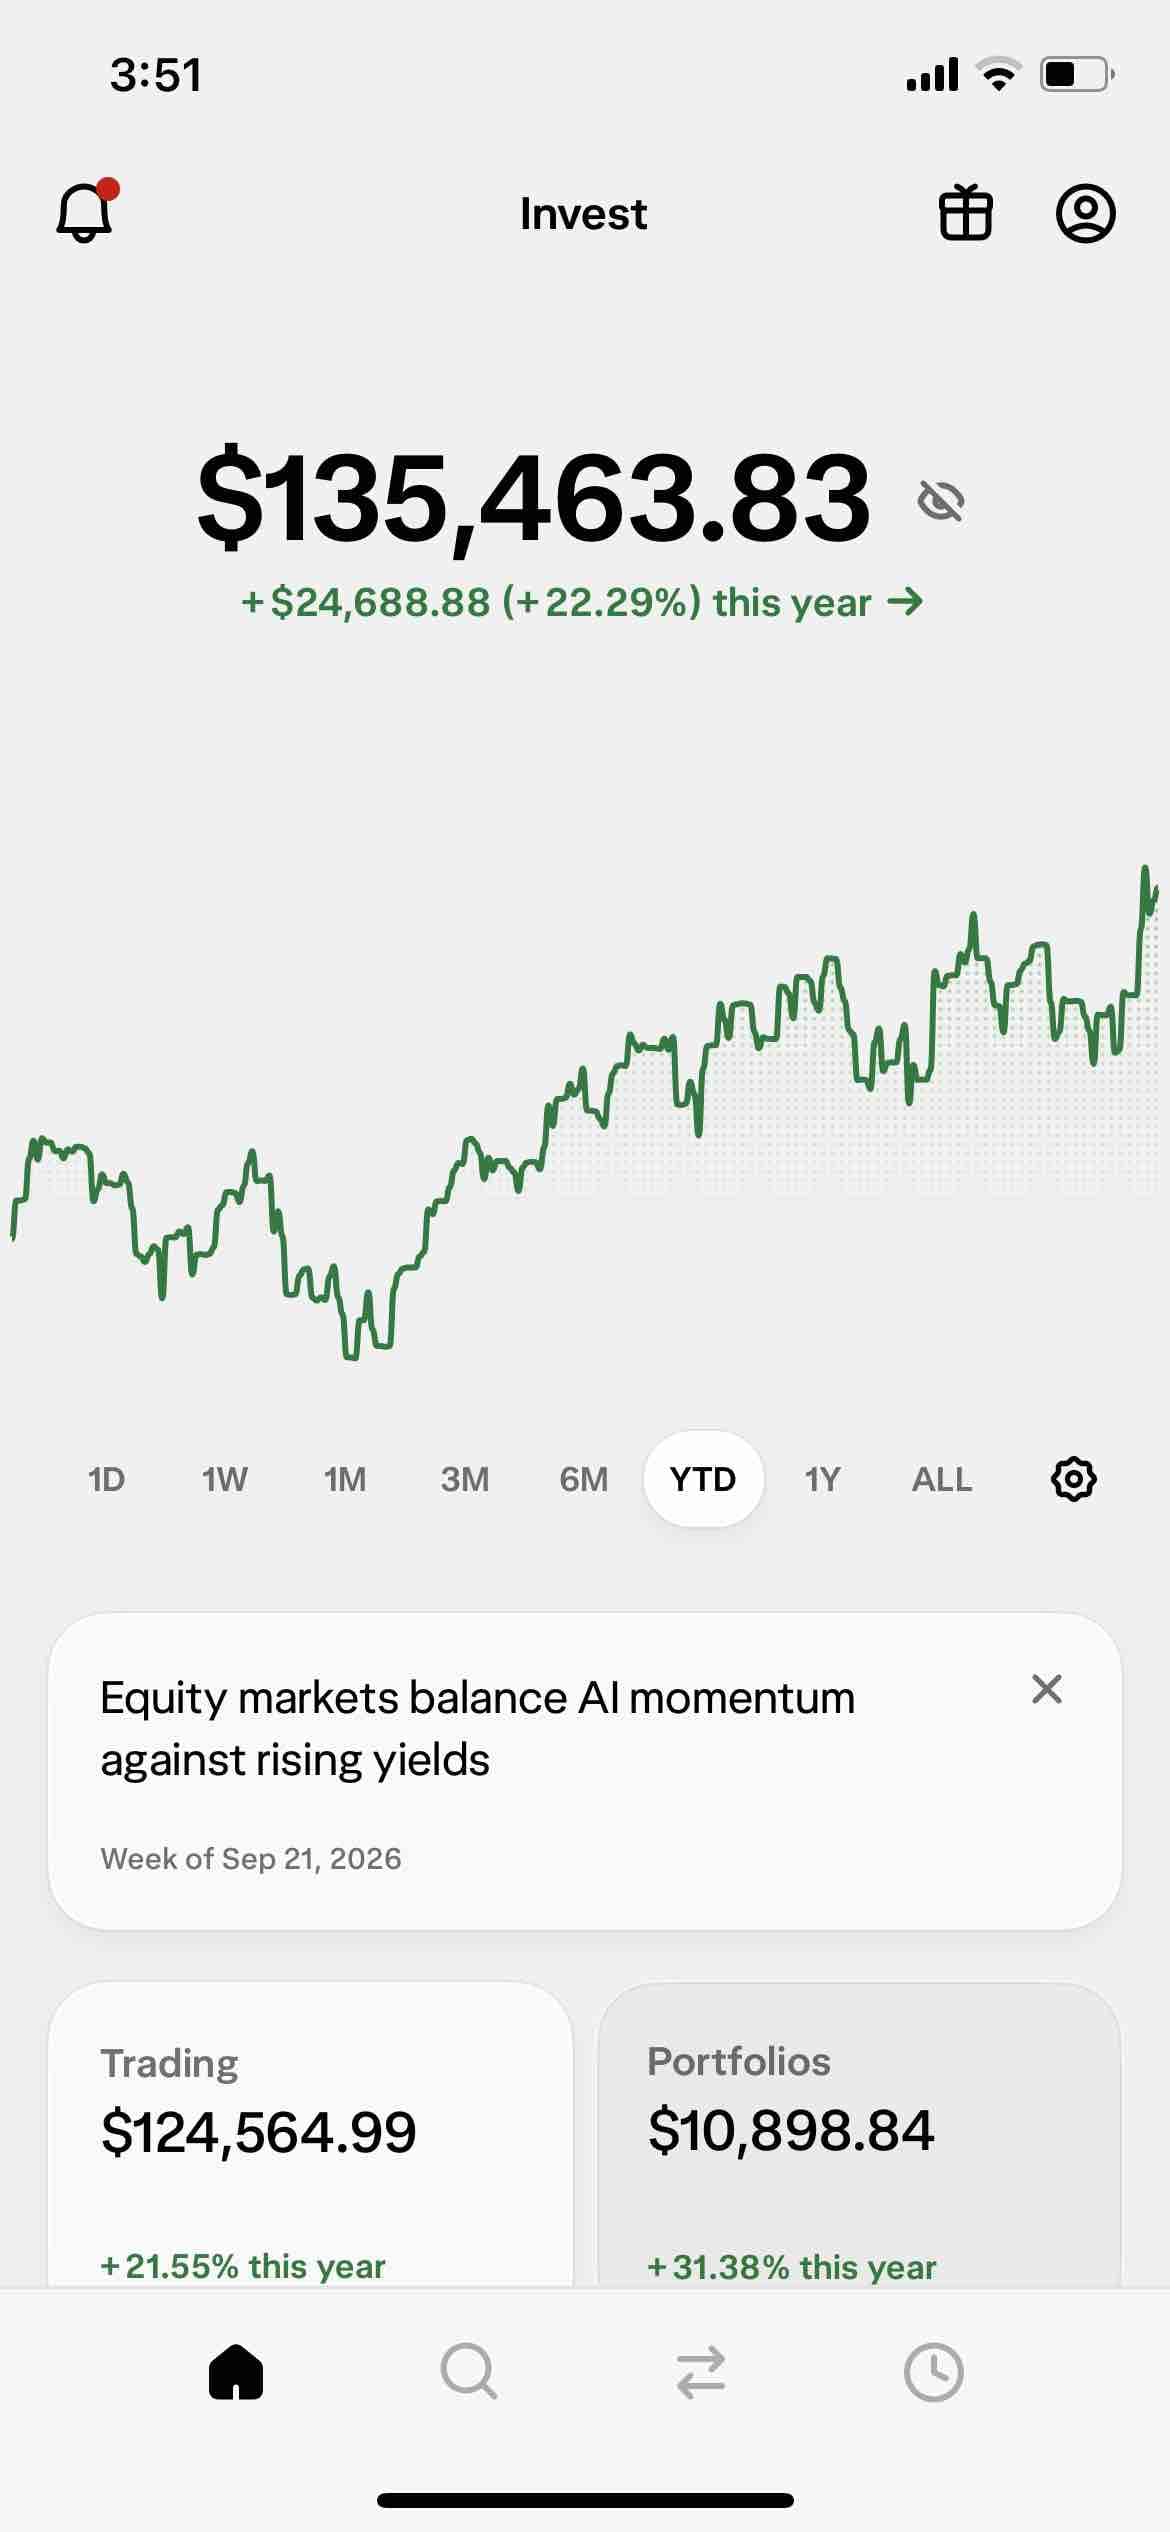
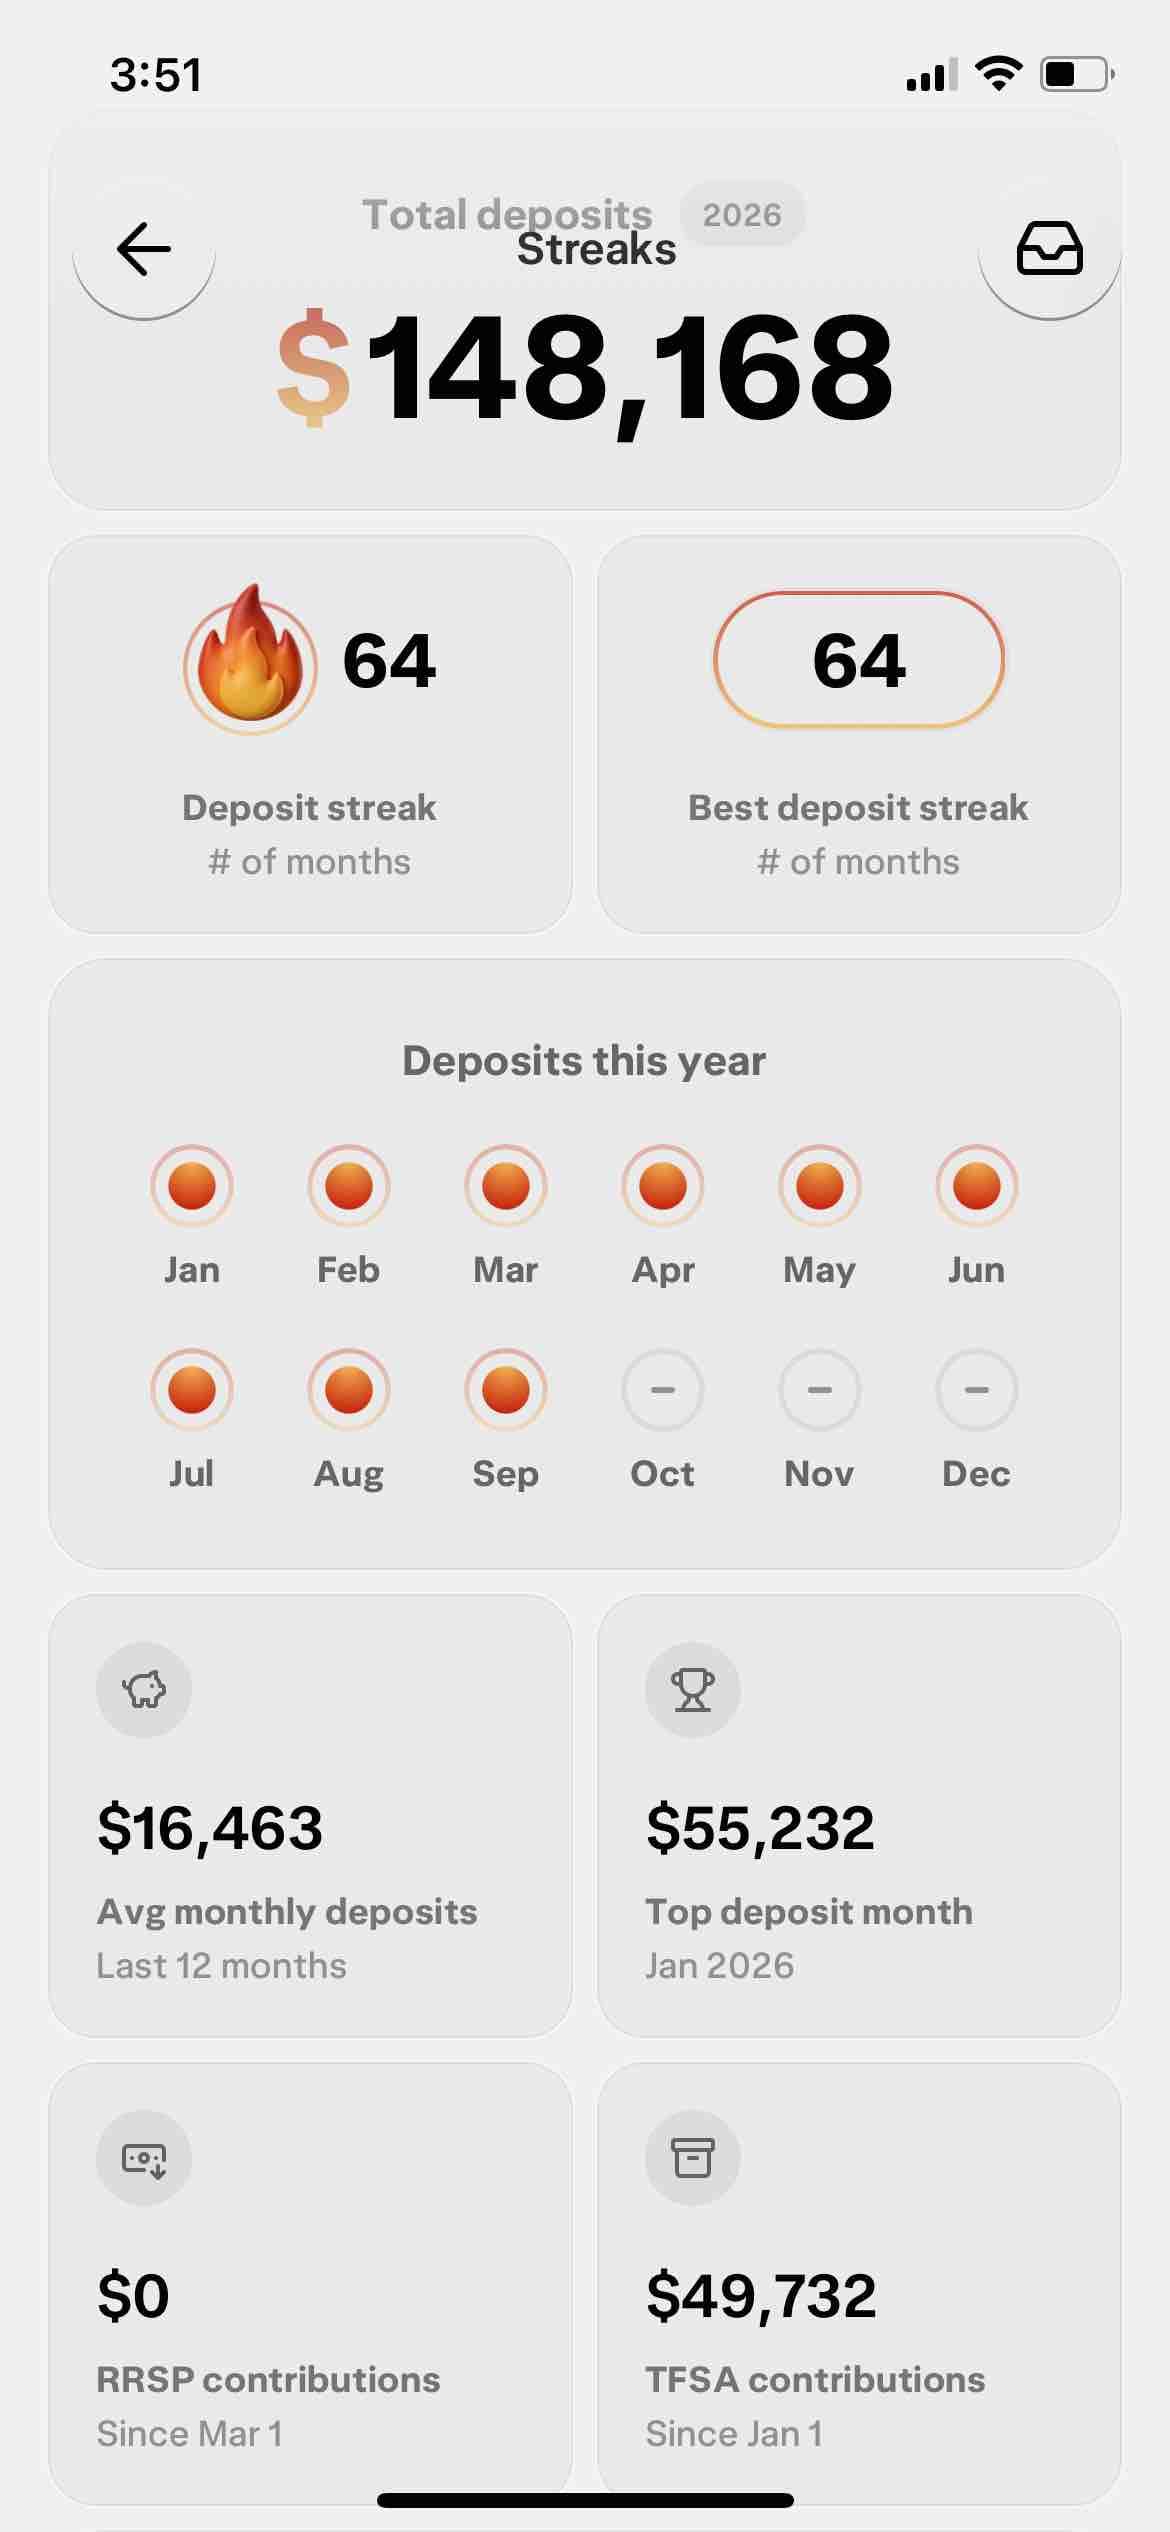
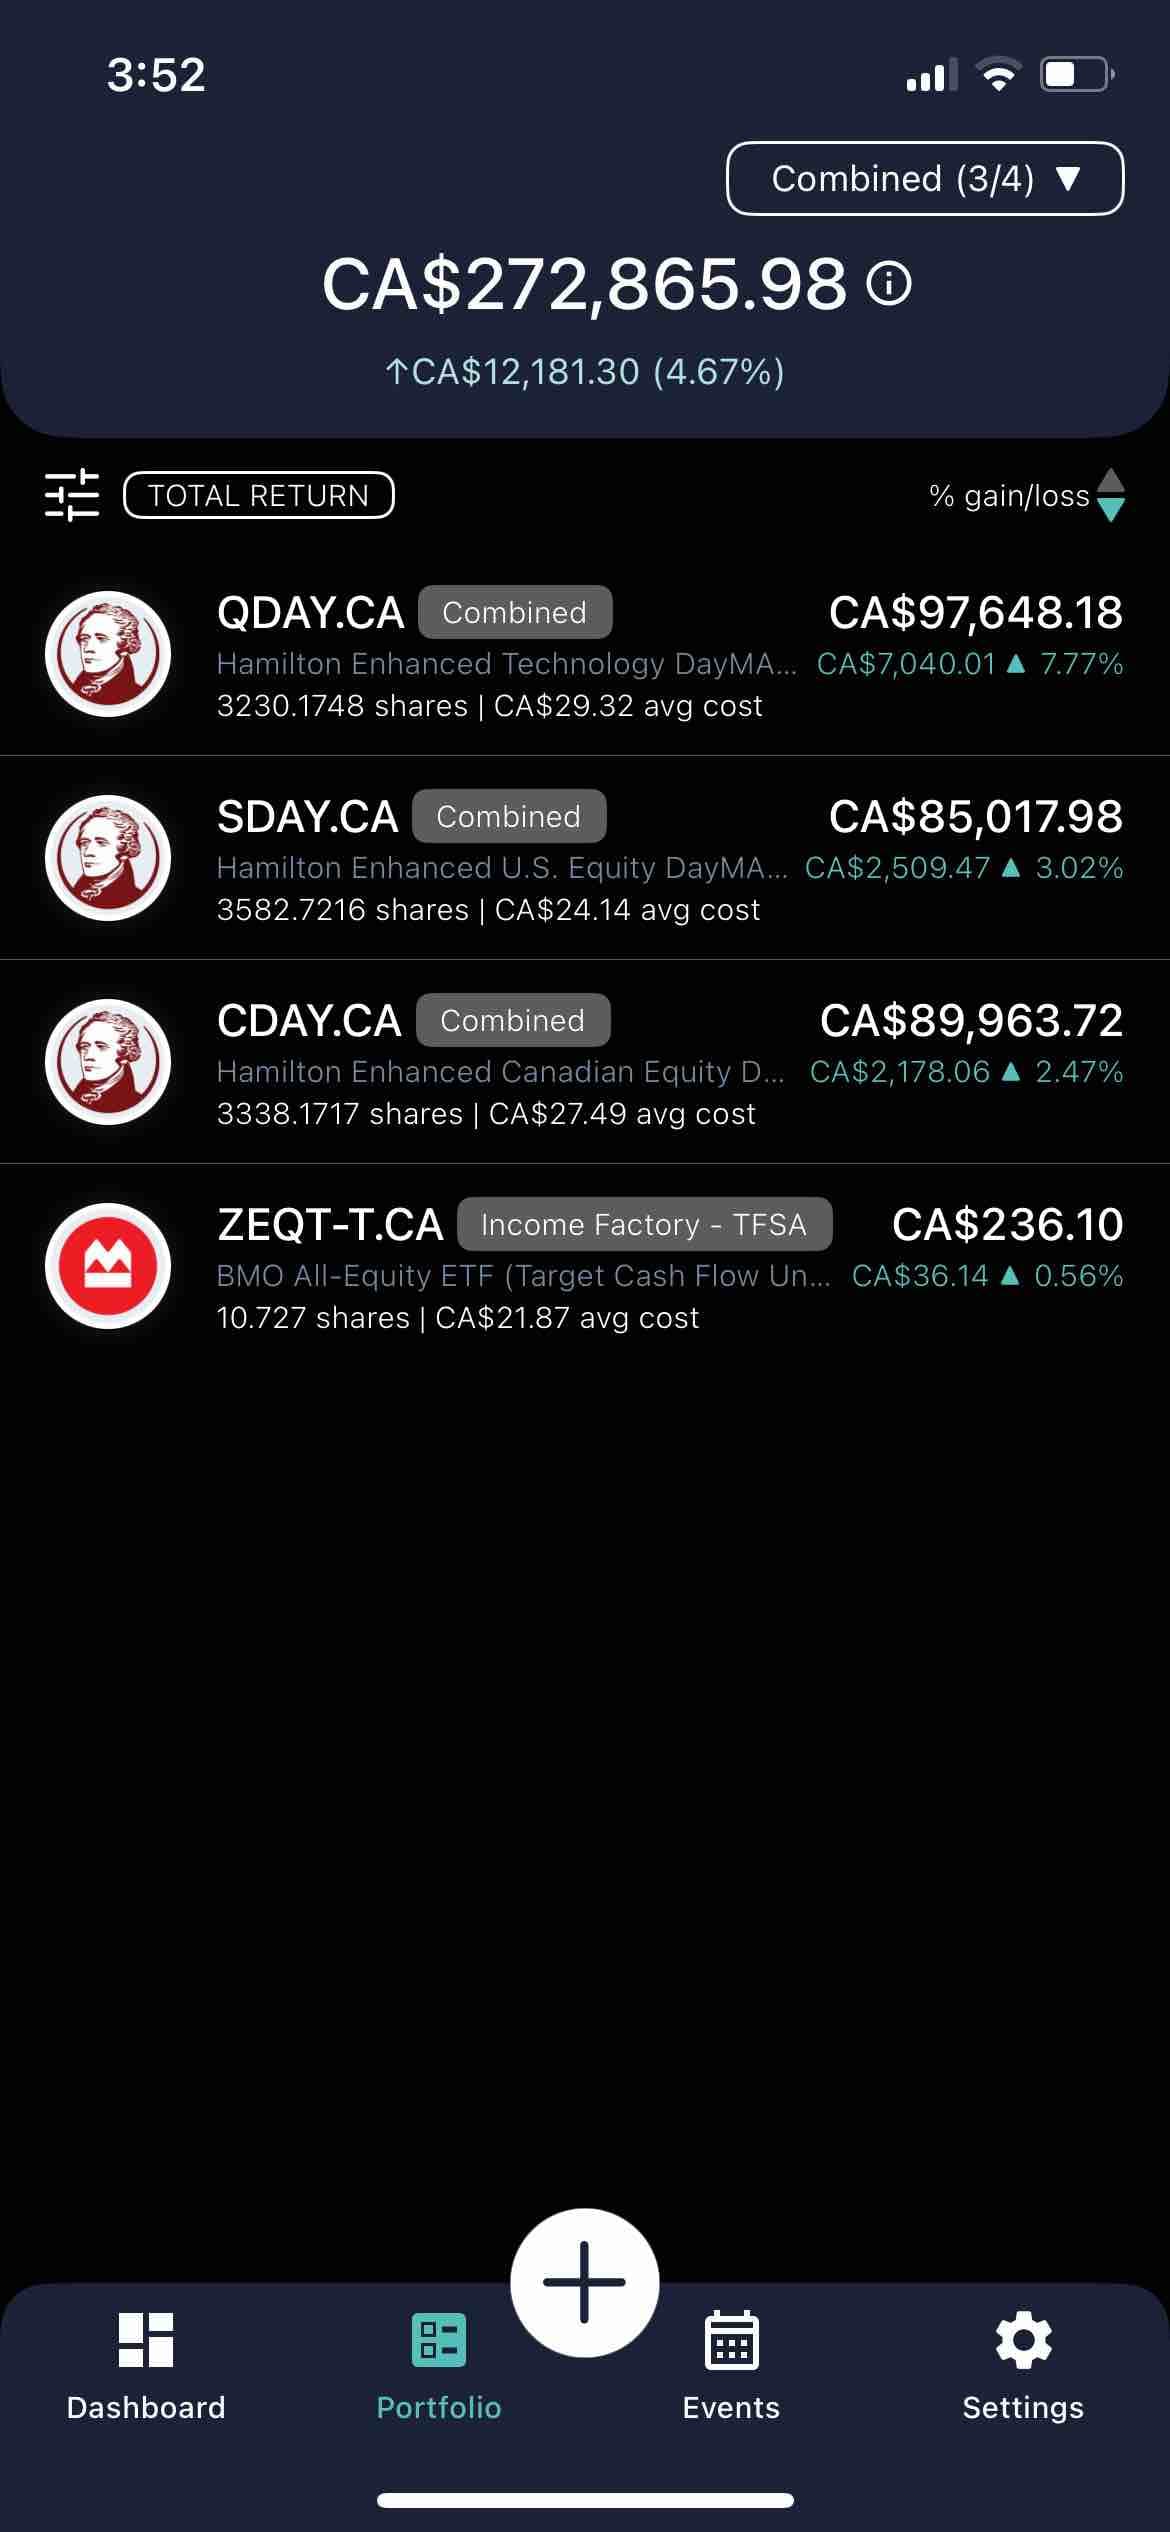
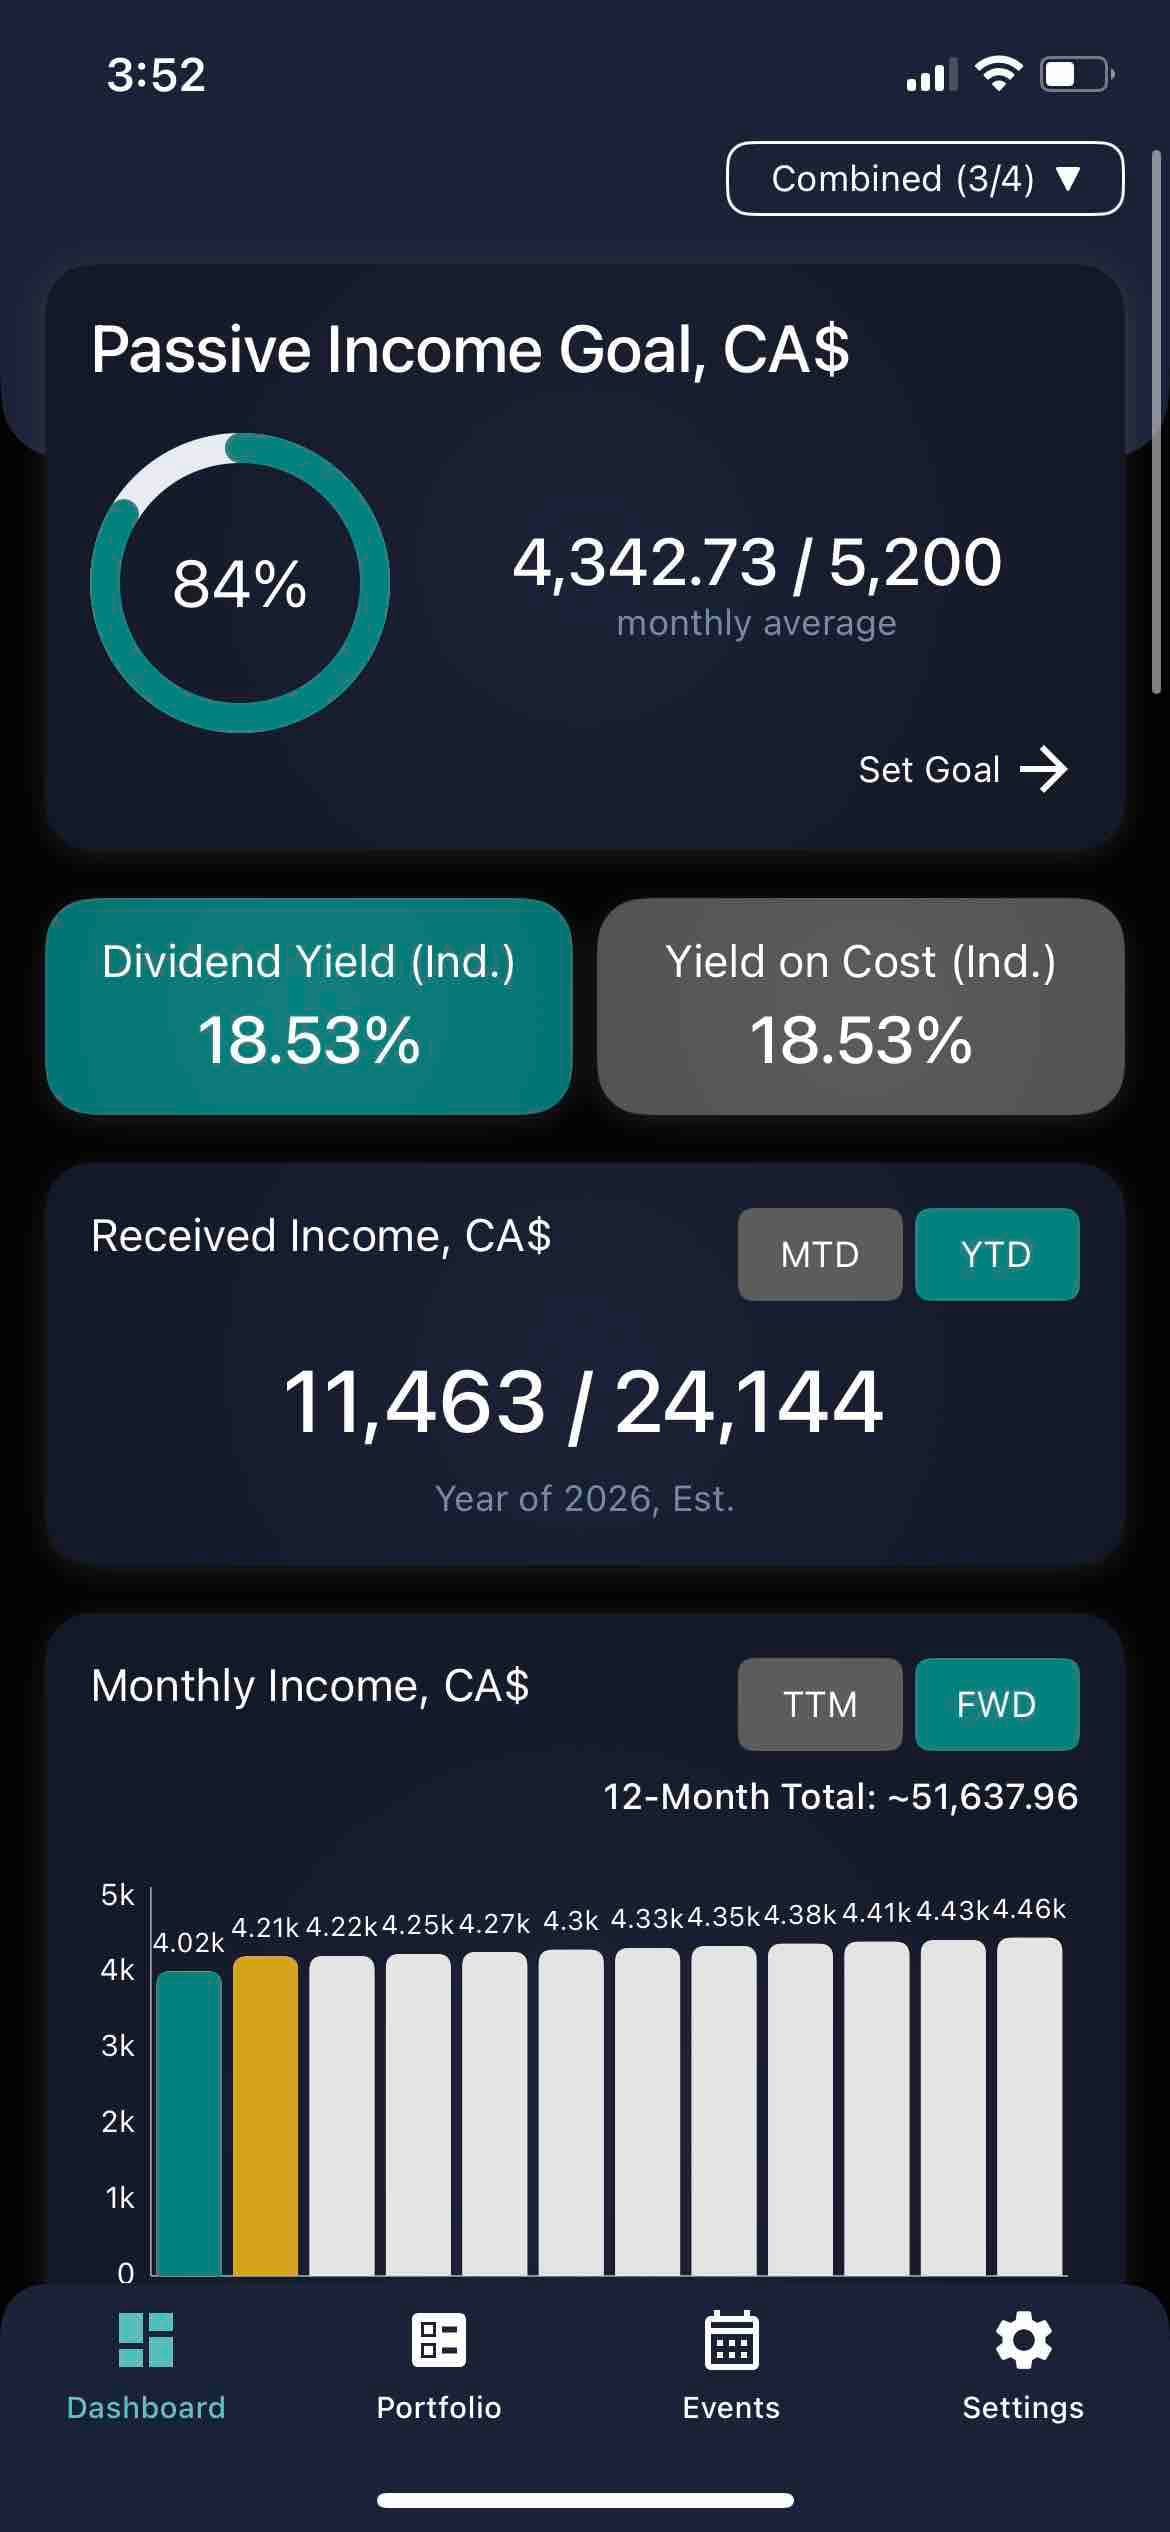
Well it’s been about 14 months now since I made the monumental decision of running the paycheck to portfolio strategy, and what can I say it’s been the best experience so far. I’m currently on my 3rd integration of figuring out how to make this thing work and so far I’m pleased with the results. I started off with yieldmax and equivalent funds in summer of 2025 because well that’s all this yield chasing ass held at the time. Started paycheck 2 portfolio June 2025. In December 2025 I decided that the erosion was too much to make the strategy effective. In January 2026 I swore off any and all CC ETFs and went “ALL IN” on $XEQT however since the paycheck to portfolio is a “DEBT ACCUMULATION” strategy I was uncomfortable holding all that debt without my portfolio being monetized. Originally I had the thought when DayMax ETFs were launched that they had potential to be the main drivers of the system. At 50% margin requirements they didn’t leave me enough room to borrow since expenses are already tighter than a ducks butthole. I then got scared of my margin debt and wound it down quite substantially. Once the requirements for DayMax changed to 30%. Bruce Buffer screamed in my ear “Ladies and Gentleman It’s Time” and I swapped all my XEQT to equal allocations of $CDAY$SDAY$QDAY in June 2026. Last week or the week before I was margin called for the first time. No big deal. I know why it happened and was ready for it. I had decided to pay off a 0% balance transfer from a credit card that I frequently use to front load my account using margin instead of selling the shares and using the proceeds, then I was hit with ex-day, followed by 3 red days in a row. I also used margin in the summer time for a sentimental purchase. So the breakdown if you read this far is. I literally invest every single dollar earned from everywhere plus opportunistic 0% balance transfers, personal loans, credit lines, or whatever plus some margin for investments. I get paid weekly. Money is invested same week regardless of what the market is doing. All of my bills are paid from margin loan. And I mean literally everything. Groceries, gas, insurance, dental bills, property tax, car loan, mortgage literally everything. Here are the results so far. Hope you enjoy my degeneracy in its fullest. To note. Before I started this process I could barely scrape together $500 per month after expenses so between January to Now is like what $4500 and so far YTD I’ve invested $148k so far and I’m not stopping. The reason why I’m so comfortable with it is simple all this money I’m investing would have otherwise been spent and do nothing for future me ever again so if I have to give some back every once in a while it’s not going to break my heart. Inspired by @fully.invested.fi Because you’ve been interested since day one @canadianinvestor
8,550 views
72 Comments
Ty @tylercanuck · 13d
I couldn’t imagine living like this. I can’t even carry a balance on my credit card. 🫣
Canadian Investor@canadianinvestor · 13d
Cash flow lets you work on the equity side, but liquidity is what lets you survive. People fear margin calls because they can turn short term market movements into permeant losses. If you are going to play with leverage make sure you have the liquidity side locked down. I like your post and I'm wishing you nothing but the best !
Trace Adkins@traciadkins · 13d
Interesting strategy. The part that really caught my attention is using margin for everyday expenses while putting your income into the portfolio. The returns look good, but I’d be most curious to see how it holds up during a big drawdown or when borrowing costs rise. That’s where things could get interesting.
Not Financial Advice @anpc86 · 9d
What does this do to your credit score ? Somehow I feel if you ran this as business or corporation , there’s potential for more optimization but I’m not sure… it’s funny , all these people say they could never , but this is how the companies often operate that we invest in
See the full comment section 👀Sign up for the full Blossom experience!