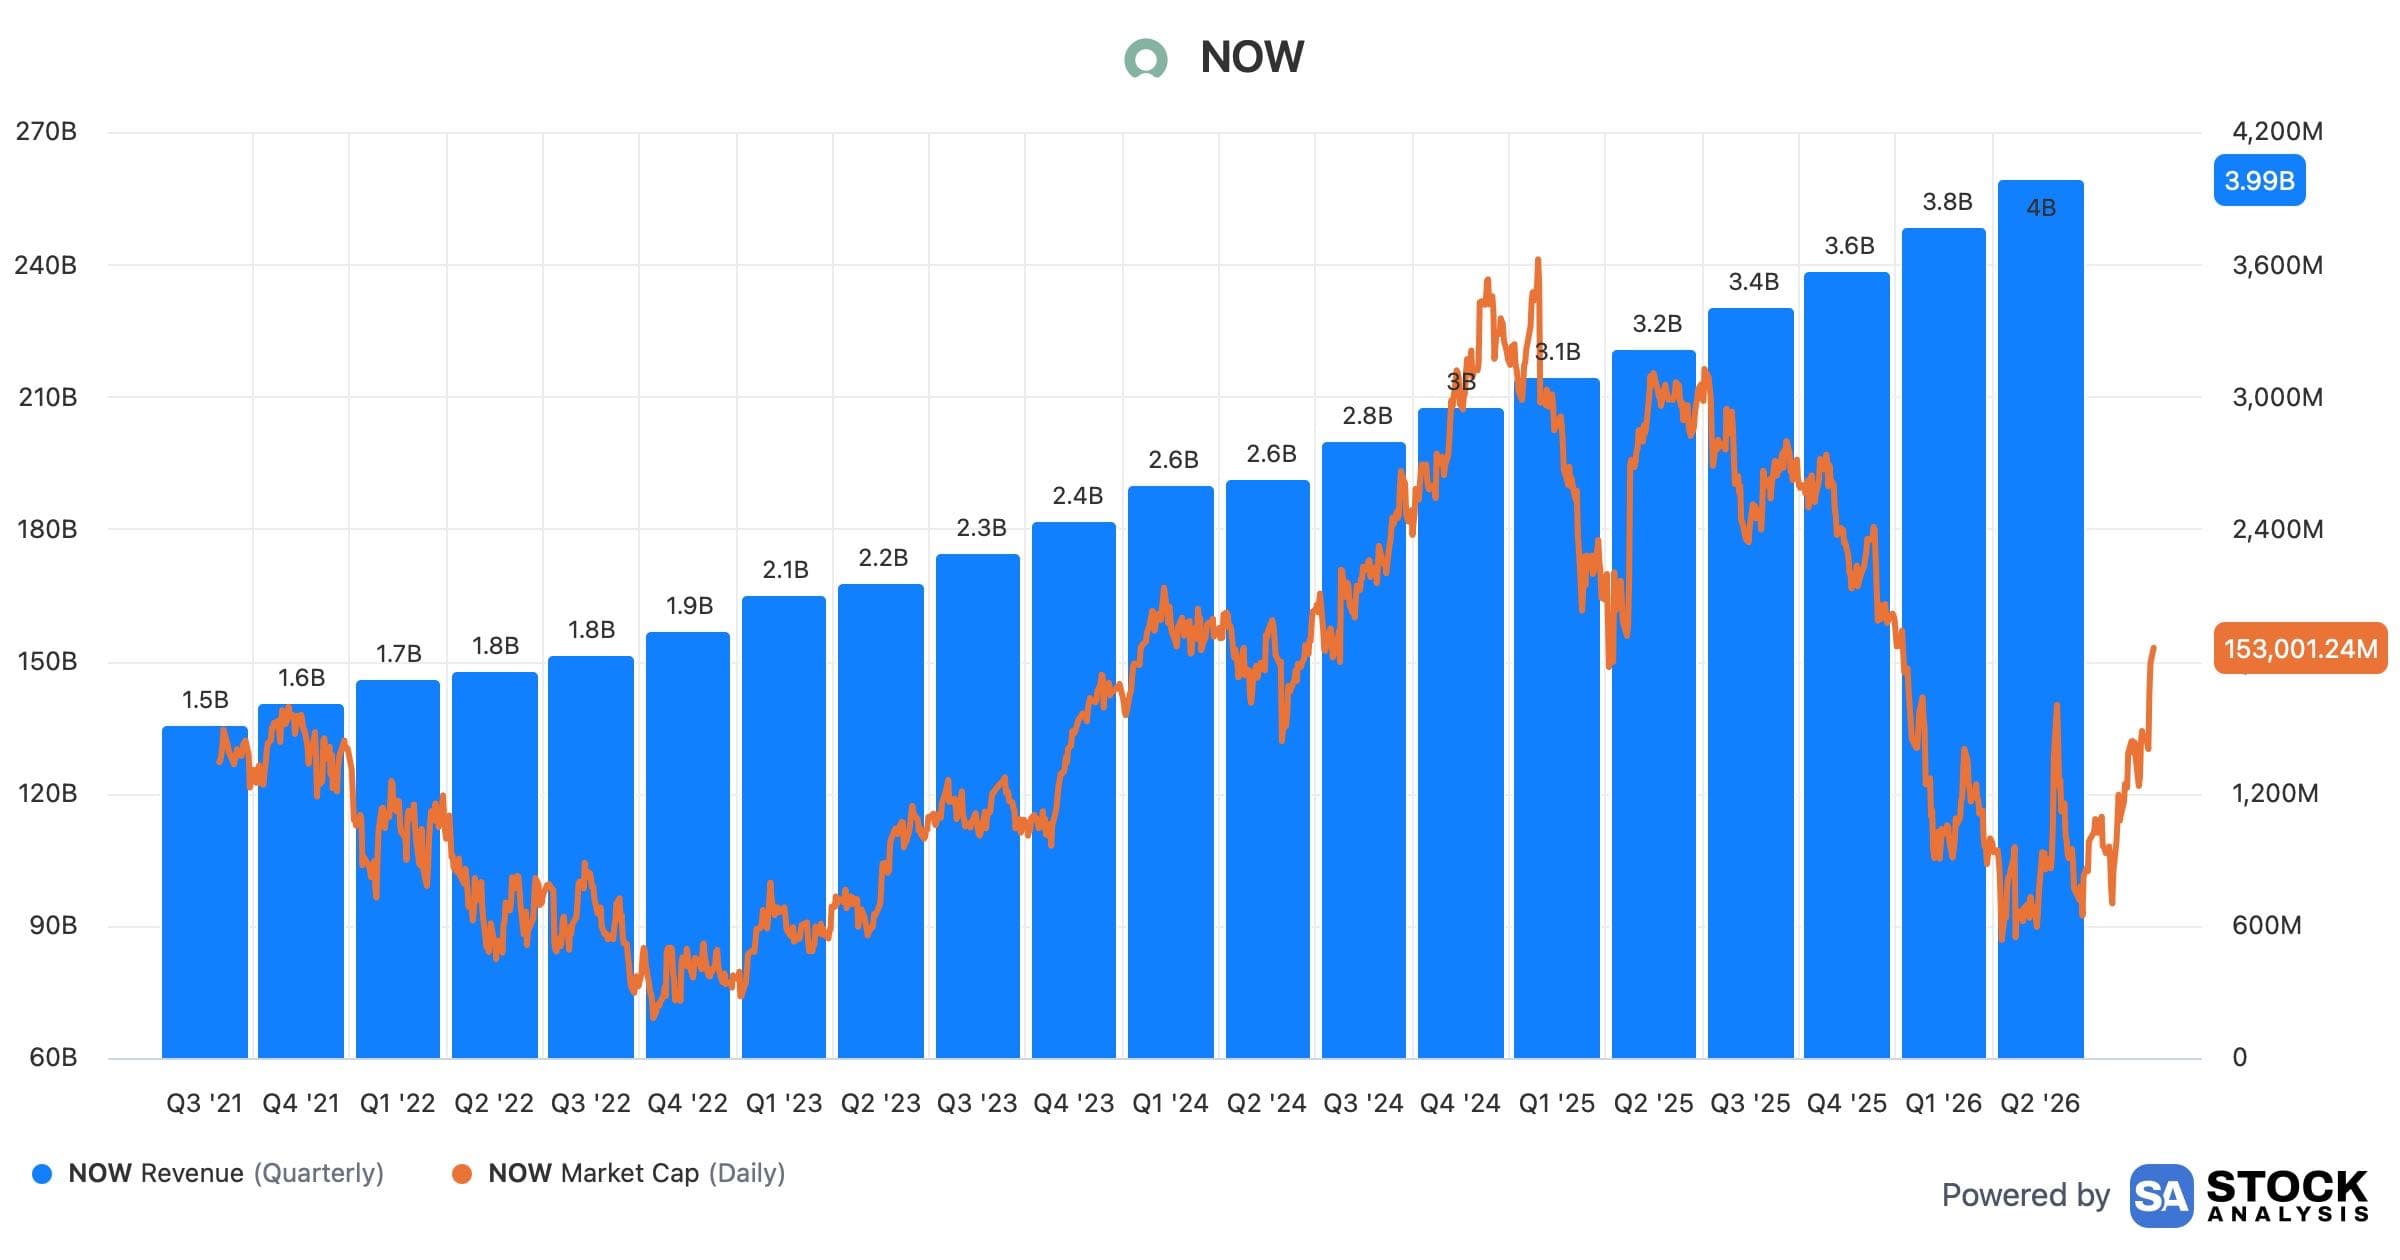
$NOW still looks cheap to me. What I think the market is missing is that ServiceNow is reaccelerating at scale. Total revenue growth went from 20.5% in Q4 2025 to 22% in Q1 2026 to 24% in Q2 2026. Subscription revenue growth reached 24.5% last quarter, while the business is now doing nearly $4B of quarterly revenue. Meanwhile, $NOW is trading around: 32.7x forward earnings 33.4x free cash flow 8.7x forward sales For a company reaccelerating revenue growth into the mid-20% range, with strong free cash flow margins and consensus still expecting around 20% growth over the next few years, I think that valuation is very reasonable. And that’s before giving much credit to what AI could become for ServiceNow. My thesis is still that $NOW can become one of the control layers for enterprise AI, connecting workflows, data, automation and agents across an organization. If revenue keeps compounding around 20%+ while margins remain strong, I still think $NOW looks cheap around $148 per share.
926 views
2 Comments
REMAINS @remains · 10d
Hehe me buying at 100$ 🤪
See the full comment section 👀Sign up for the full Blossom experience!