The 4% Rule Might Be Overkill for Retirement😬
The FIRE community treats the 4% rule like gospel:
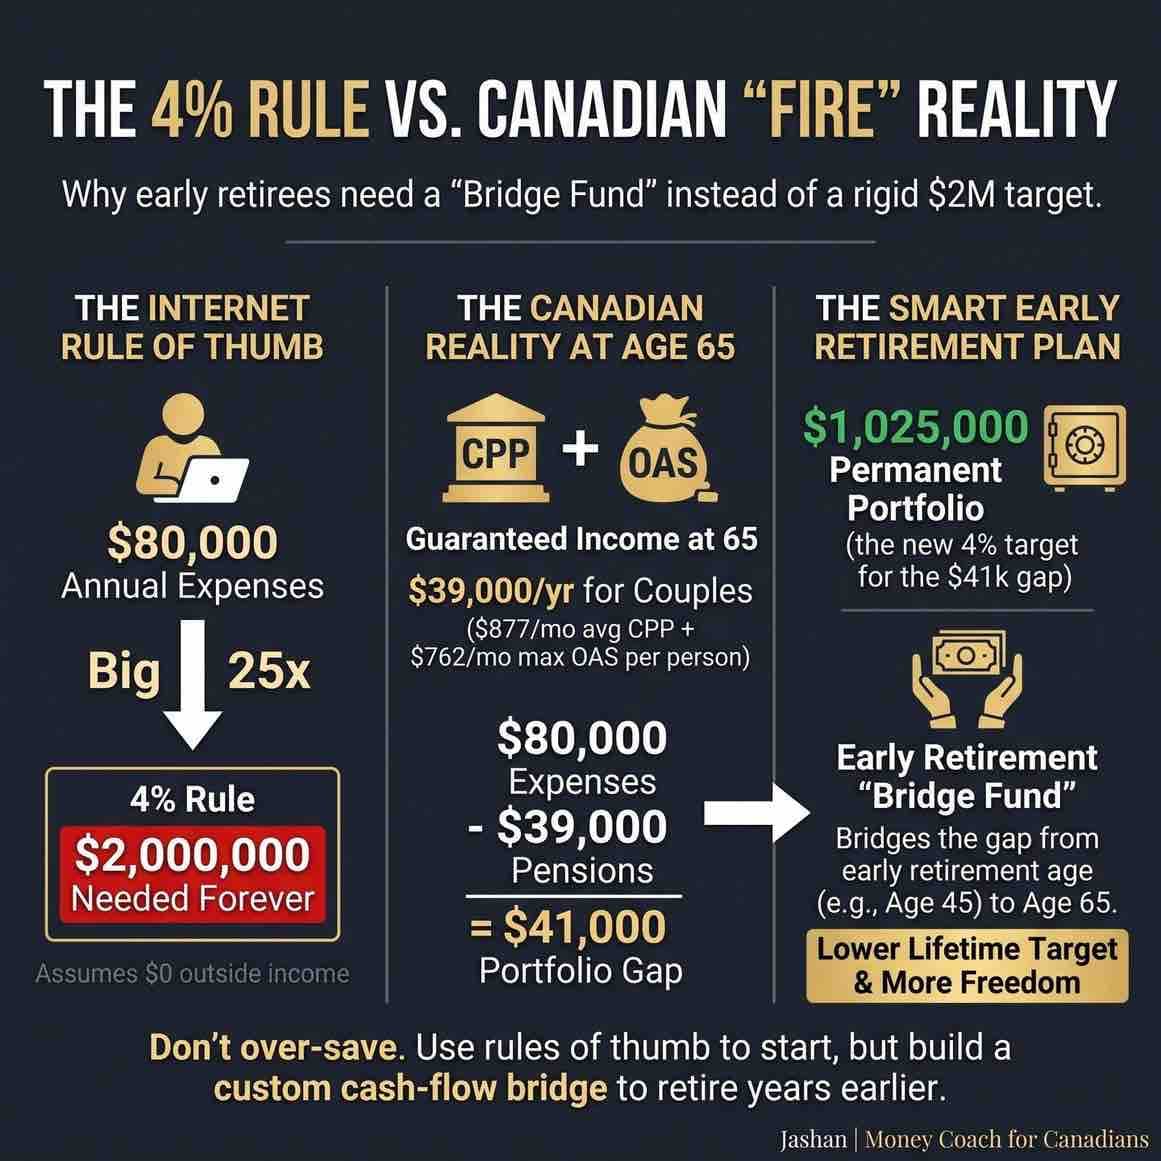
Multiply your annual spending by 25 and walk away.
Want an $80k lifestyle?
The rule says you need $2,000,000.
For Canadians, that rigid formula can trap you at work for 5 extra years.
🚨 The $445,000 Blind Spot
The standard 4% rule assumes your portfolio must fund 100% of your life forever.
It completely ignores guaranteed income.
Early retirees often brush off government pensions because age 65 feels too far away.
That is a massive planning error.
🇨🇦 The Canadian Reality at Age 65
Between CPP and OAS, a retired couple can conservatively expect ~$39k/year in combined, inflation-indexed income.
Even retiring at 45 with zero earnings for 20 years, maxing contributions in your 20s and 30s still secures a significant baseline.
That changes the math completely:
$80,000 desired lifestyle
− $39,000 CPP & OAS
= $41,000 net portfolio gap
Apply the 4% rule to that remaining gap:
$41,000 × 25 = $1,025,000 needed at age 65.
Not $2,000,000.
🌉 The 20-Year Bridge (Retiring at 45)
You do not need $2M on day one.
Your portfolio only needs to do two things:
* Fund $80,000/year for 20 years.
* Arrive at age 65 with ~$1,025,000 left.
At a conservative 4% real (after-inflation) return:
You only need $1,555,000 at age 45.
• Years 45 to 65: Portfolio draws down to cover the bridge.
• Age 65 onward: CPP and OAS turn on, withdrawals drop to $41k, and the remaining $1.025M lasts indefinitely.
⏳ The Real Cost: Your Time
$2,000,000 vs. $1,555,000 is a difference of $445,000.
Grinding for that extra $445k often means 4 to 6 unnecessary years at a job you're ready to leave.
The 4% rule is an easy benchmark for your 20s and 30s.
A dynamic cash-flow plan gives you your freedom years sooner.
When you get serious about pulling the trigger, run the actual numbers with a fee-only CFP to find your real finish line.
💬 Are you factoring CPP and OAS into your early retirement number, or planning to fund 100% solo?