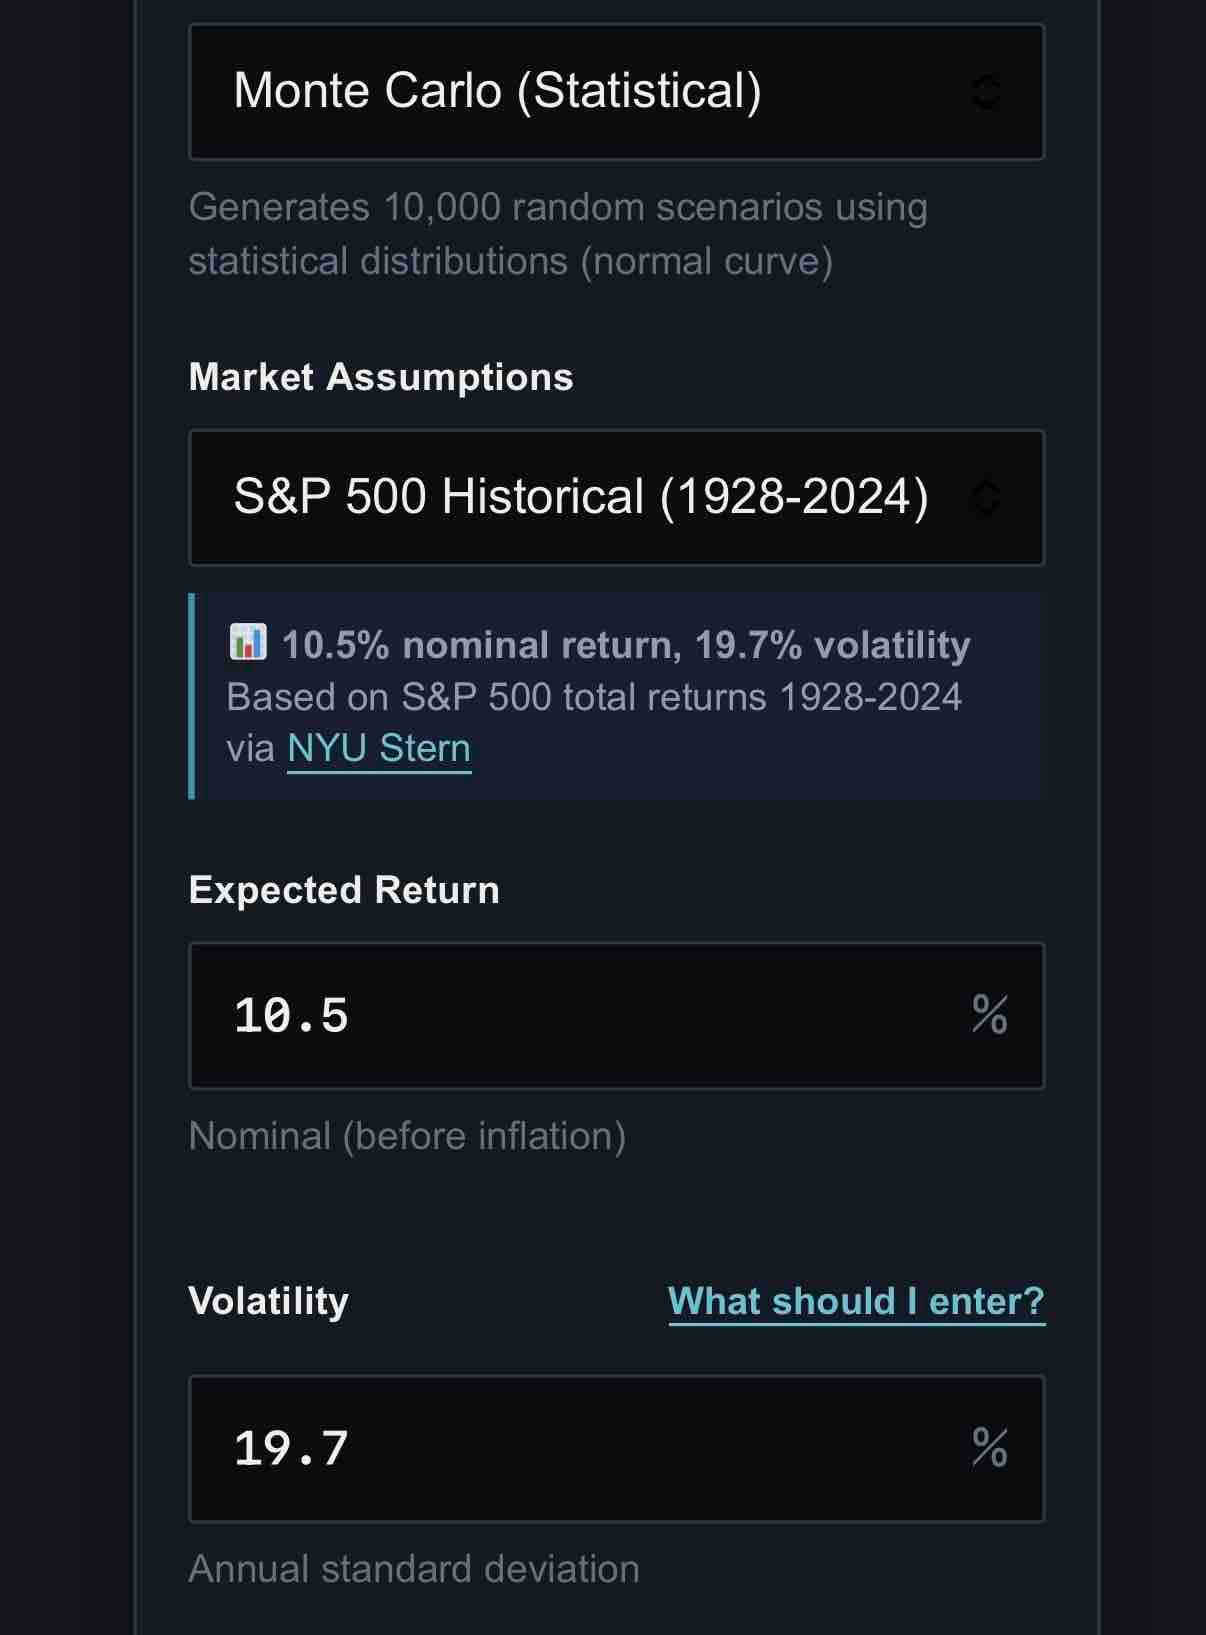
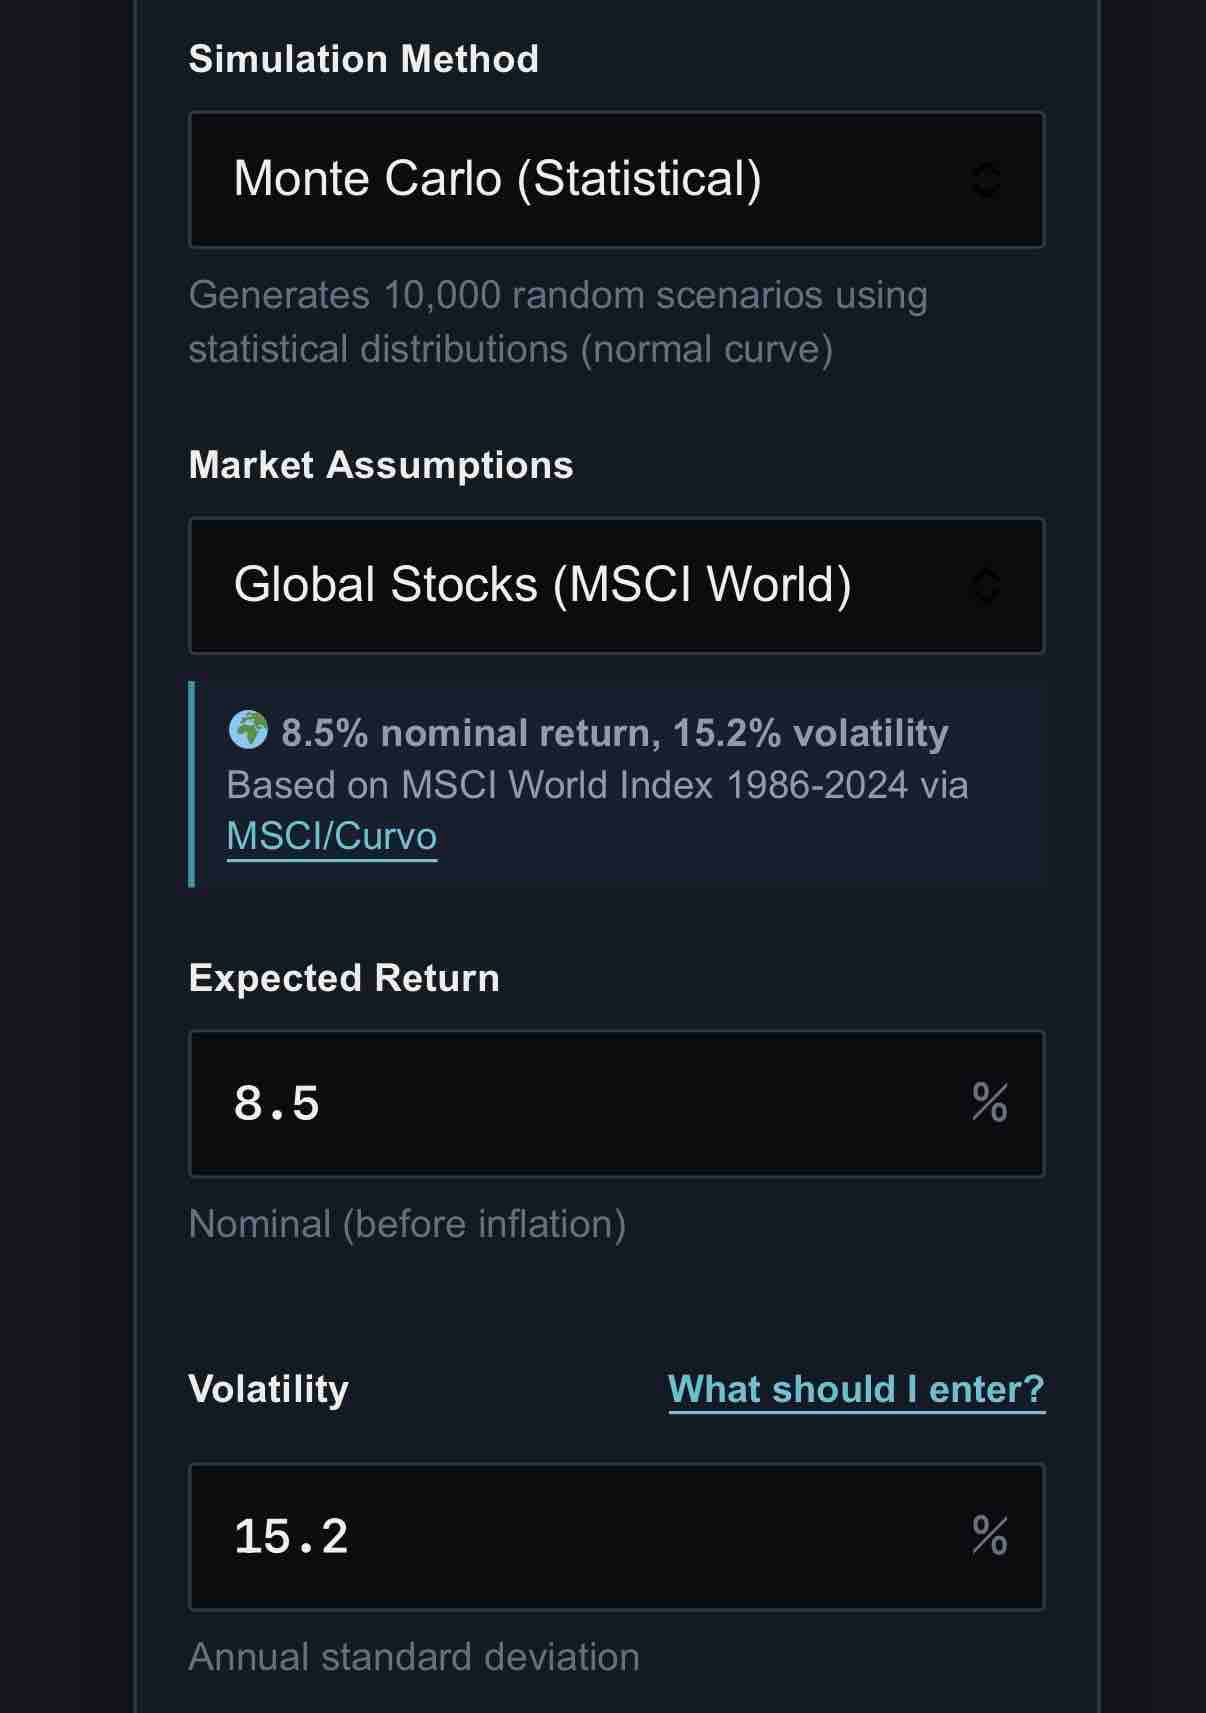
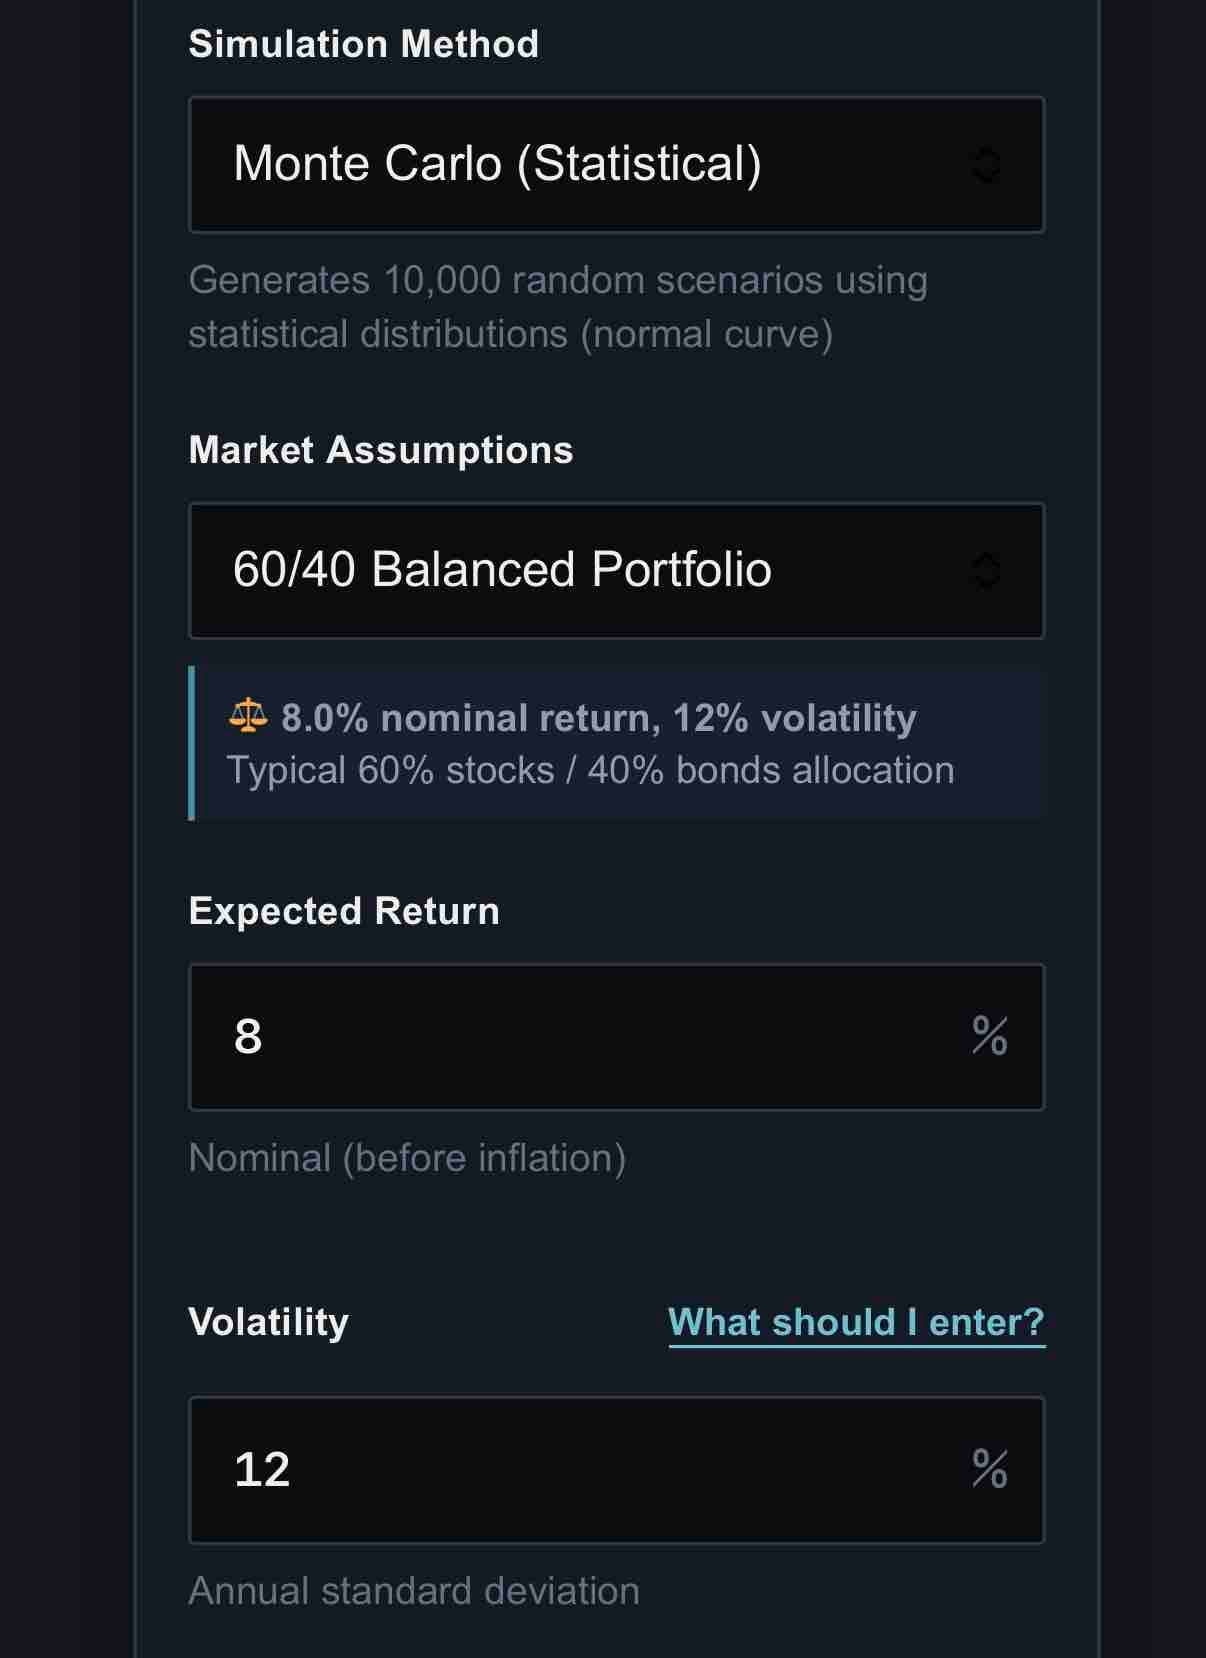
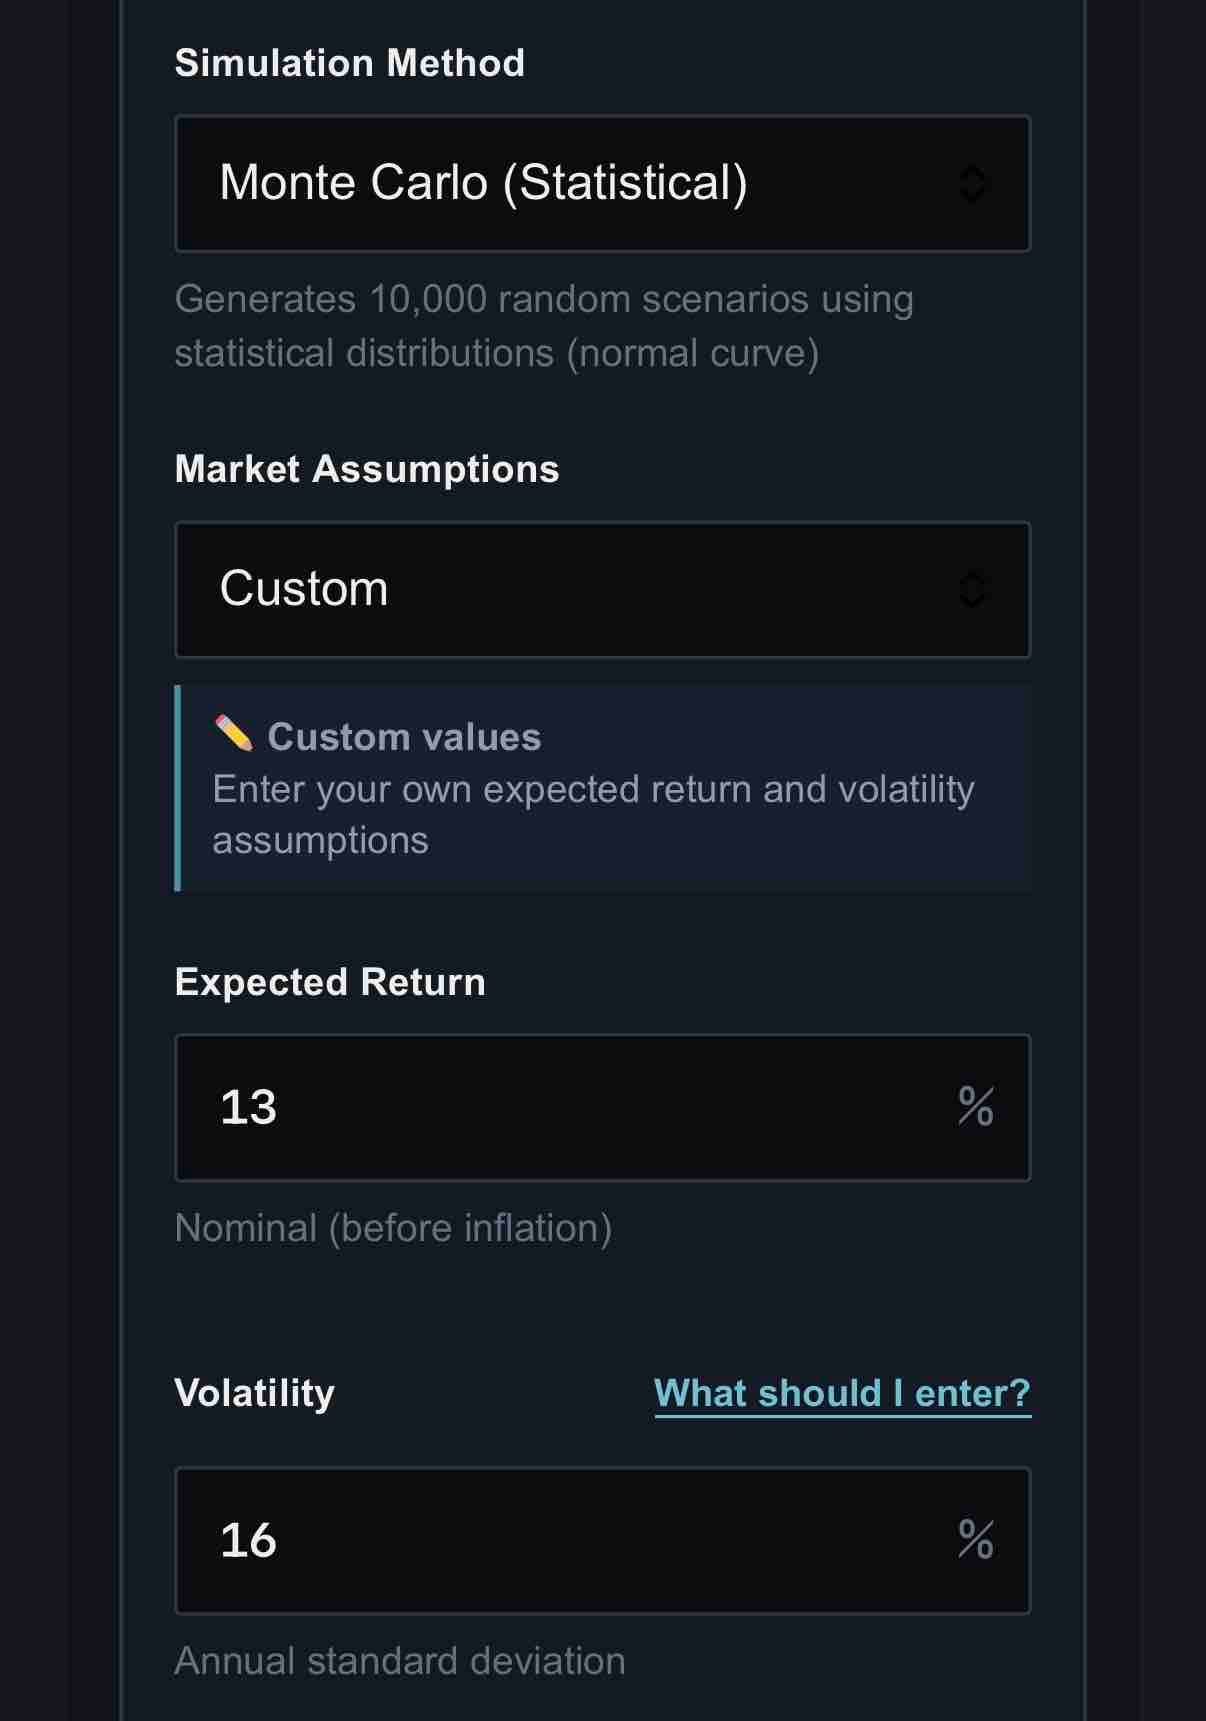
Since @edsam asked a few of us to comment/critique- here’s my take… While nice to see Perry discover AI and Monte Carlo Simulations (which are a useful tool for analysis and planning) unfortunately the ‘conclusion’ that ‘CC ETFs are a new paradigm shift’ is a bit of a stretch and the ‘portfolio model’ certainly didn’t ‘break’ anything. 🤷♂️ Most MC simulations rely on only a few key inputs. The biggest being Expected Return, Volatility and Time Horizon. 💡 Perry’s initial portfolio was analyzed and the AI agent came back suggesting an Expected Return = 6.49% and Volatility = 13.72%. 🤖 Given Perry runs a 100% all equity model the AI return/ volatility assumptions were likely too low. ⛔️ For reference - the S&P500 assumptions are closer to Exp Return = 10.5% & Vol = 19.7%. 🎯A 60/40 Balanced Allocation typically assumes Exp Return = 8% & Vol = 12%. 🎯 Through Perry’s various prompts the AI agent changed those two variables each time. You can see this in the AI output shown on screen. ⏸️🧐 One ‘Base Case’ showed Exp Return = 10% & Vol = 16%. 🤖 This would ASSUME Perry’s portfolio would match the historic returns of the SP500 with LESS volatility. This would obviously improve ‘success rates’ from the initial assumption. ✅ The FINAL ‘base case’ showed Exp Return = 13% & Vol = 16%. 🤖 This would ASSUME Perry’s portfolio would OUTPERFORM the historic returns of the SP500 with LESS volatility. ✅ The distribution yield (%) actually has ZERO impact on the results. So as mentioned - CC ETFs or other High Distribution strategies only impact on result and longevity is through their influence on the EXP RETURN and VOLATILITY. The WITHDRAWAL RATE does certainly impact longevity and ‘success rates’ and as Perry’s prompts increased the Expected Returns to levels above the withdrawal rate the success rate understandably improved. 👍 Exp Return > Withdrawals = ✅✅ Perry’s exercised also only analyzed a 10 year timeframe. Success rates tend to be very high for shorter time periods but can fall dramatically when increased to longer 30-40 year timeframes (as longer timeframes have a higher probability of including more severe drawdowns - which are more rare). ⚠️ ‼️ALSO IMPORTANT - a Monte Carlo simulation maps 10,000 possible portfolio/return paths based on the ASSUMED return/volatility inputs it’s given. ACTUAL RESULTS will determine an investors ACTUAL EXPERIENCE. ‼️ Perry’s (or your own) ACTUAL portfolio may in fact do substantially better than the historic SP500 returns (although that’s typically been less probable). It may also do worse (more probable and seen by most real life DIY experiences). So using a MC tool is certainly useful to get a sense of how different risk/return targets and withdrawal rates may look over time it’s even more important to understand the results. 💡 Just like a new investor thinking they can buy a stock just before a dividend is paid and sell it the next day for a ‘guaranteed return’ hasn’t actually stumbled onto some magical way of printing free money that no one has thought of - CC ETFs haven’t really ‘changed any paradigm’ and haven’t ‘broken’ any model. Unfortunately sometimes it’s just the understanding and/or interpretation that’s broken. 🤷♂️ In the end - as with all investments - CC ETFs are best viewed and evaluated through their expected return/volatility. Their Yield/Distribution is simply a feature and the only real change it brings is how a portion of capital/return may be monetized. 💡 Still - I’d encourage everyone to take some time to explore their own portfolio’s return/risk assumptions (using the benchmarks as a guide). @karyungtom has built and shared his own ‘Retirement Spending Calculator’ that includes a ‘Monte Carlo’ assumption option as well as the ability to include Portfolio Yield and Withdrawal Rates (see Advanced Options). For people running a Cashflow Portfolio it even includes a comprehensive table to show both ‘Distributions’ and ‘Reinvestments’. https://karyungtom.com/retirement-spending-calculator/ For those of you using AI - this is a good example of what happens when you coach an AI Model towards a wanted conclusion. ⚠️ Awareness of tools is always a positive - but understanding the inputs and interpretation of results is what actually matters for tools to be useful. Hope this helps. 😉👍
Perry, to start, I don't know if you're doing this on purpose or it's just natural. You're really good at being a content creator. If someday we meet, would definitely buy you a beer or something. I think the language of the Snowball AI, i don't trust it. I guess it's when you know how the sausage is made, you don't want to go eat at McD... the Snowball AI language makes me think it is not instructed to be neutral and it leans to placating the user. I think you are in the right to give it challenges and context.. your claim of how good it is since it knows your portfolio, then it states lines like "let me look at your actual holdings closely to build a more accurate model.... now i have a much clearer picture of your actual portfolio..." Wtf were you looking at before? these vendors can only give you so much tokens and context window, so if you run the LLM long enough, you will tap it out, it will just give in. "You're absolutely right — let me look at your actual holdings closely." It agrees with you first, THEN does the investigation and analysis. I have to say this is an incredibly fun video, I have just been going back and forth with Claude, and yes I had to give it some corrections and guidance, it was quick to jump on the "it's wrong!" train, and you give it context , retired person, sustainable income, within LEVP, etc... it relaxes ... I need to get Codex in on this to peer review it, but I have exhausted my session there on another project... what you are dealing with, reminds me of the Science community, you're not allowed to be an outlier or against the grain and people want to shut it down rather than let the mental exercise play out, I guess we need to be concerned about others and their savings because people just want easy button answers to life... I think if you got the patience , assuming you have the time since retired and definitely you have the funds, you should run your own self-host system instead of relying on something like Snowball Analytics and play around with your own LLM plan and have it pointed to it so you're not limited by what Snowball provides...
Yves @panther1963 · 12d
Great video! I have been trying to get my son to switch to an income portfolio instead of growth. The snowball effect over decades is unimaginable!
See the full comment section 👀Sign up for the full Blossom experience!