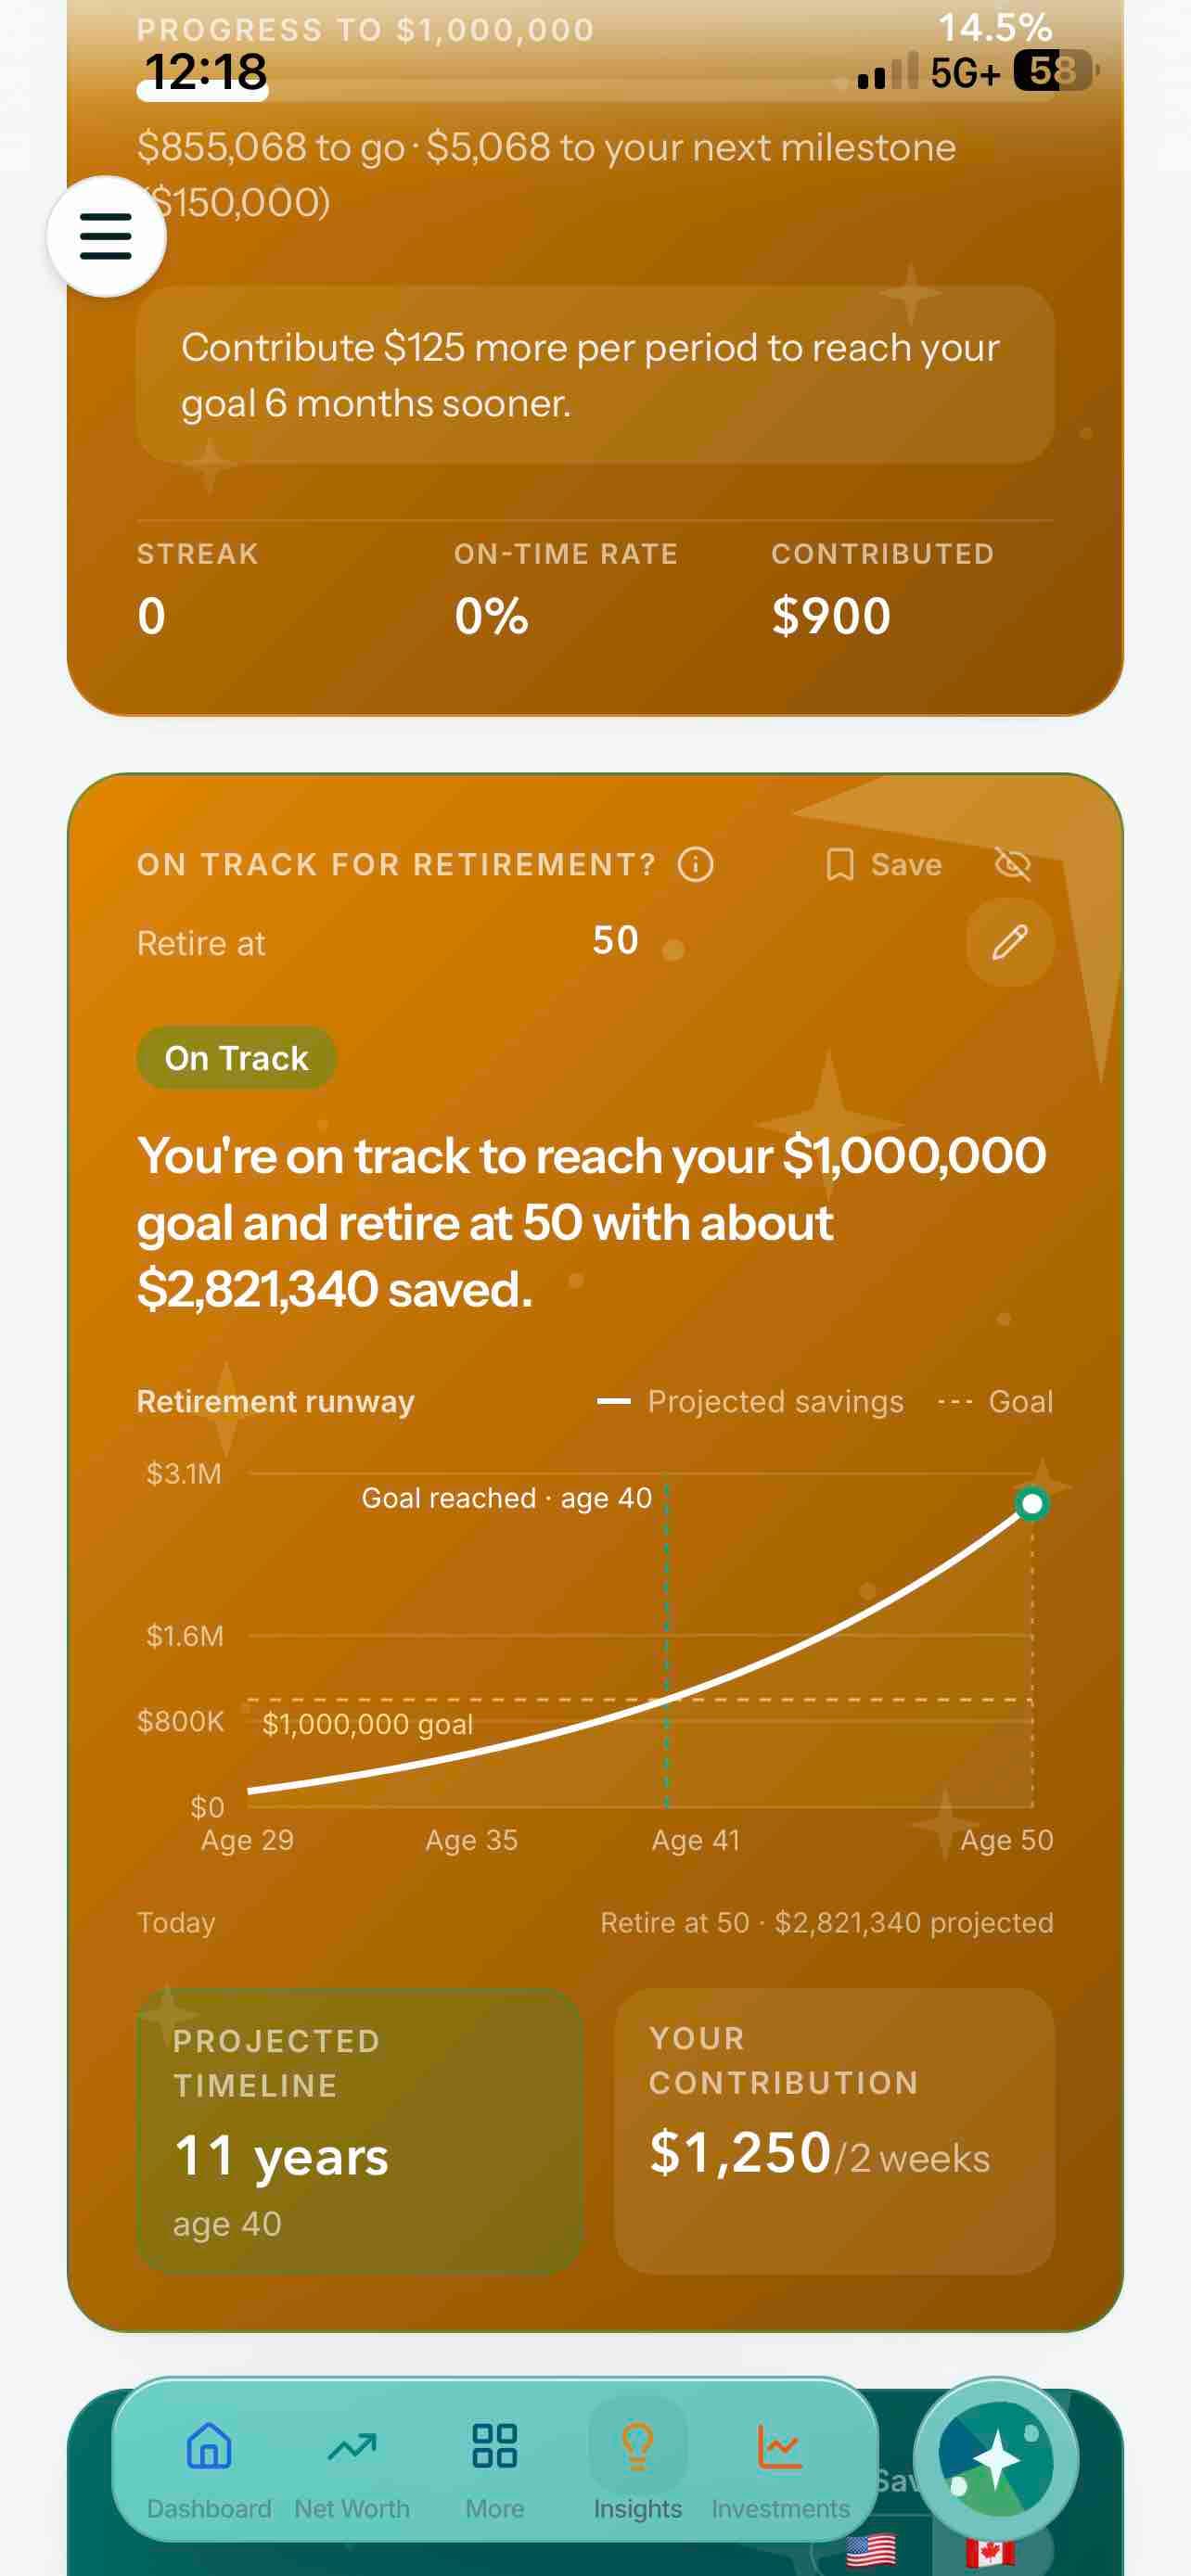
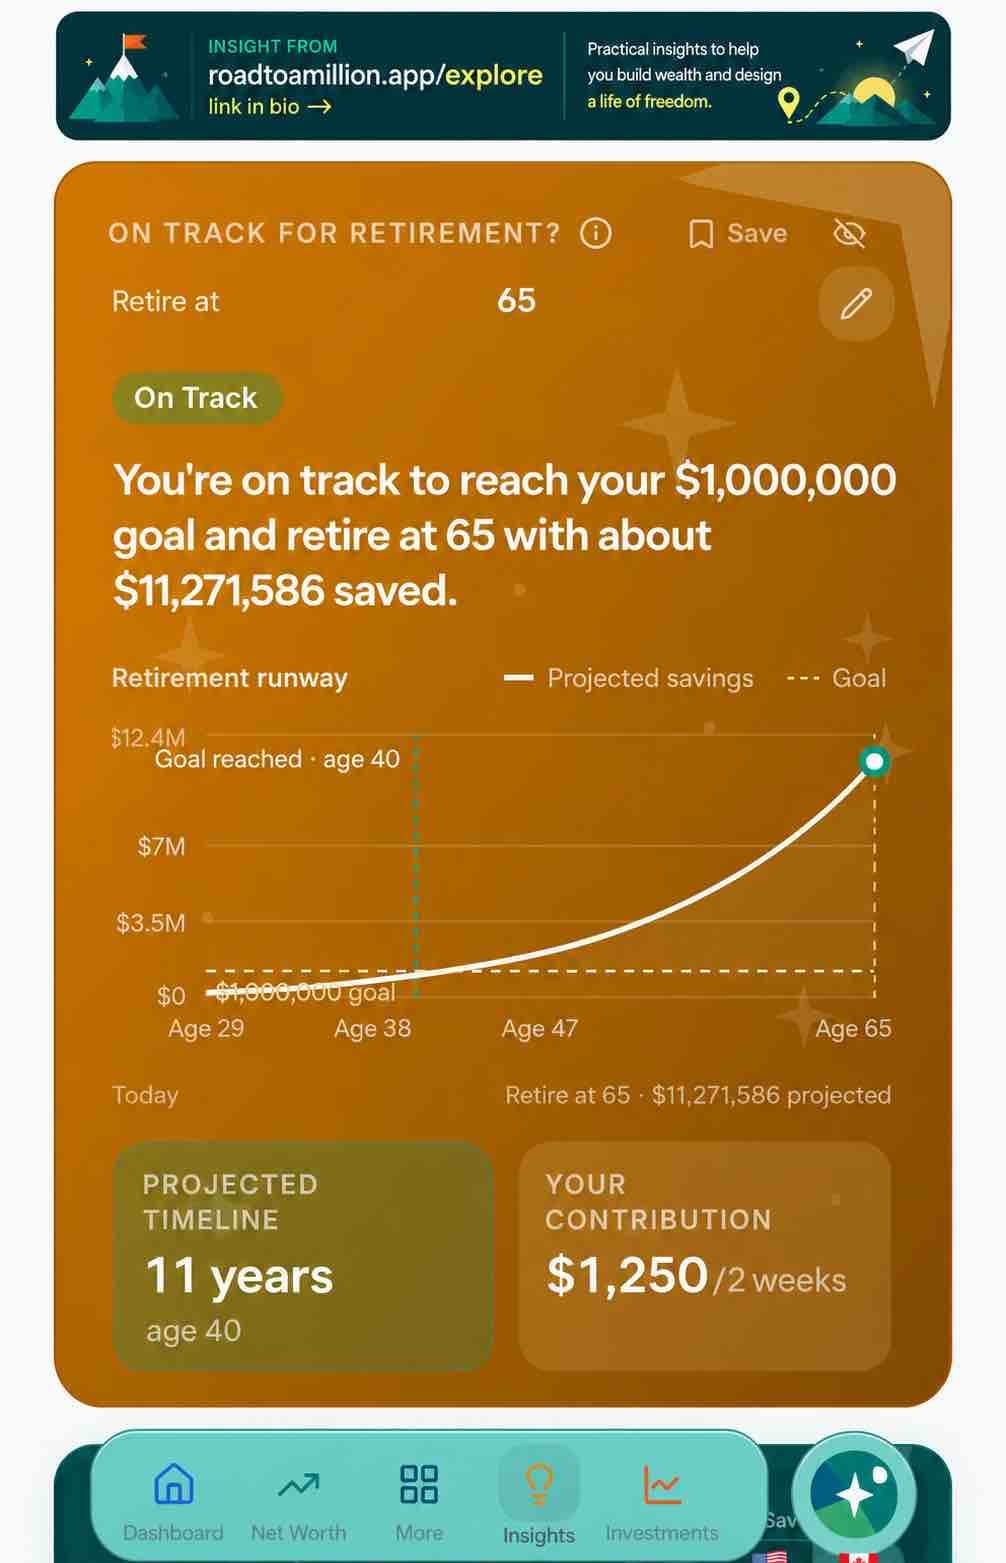
I’m currently 29 and I have an aggressive goal to reach $1M invested by the time I’m 40. I currently have about 140K invested and this goal assumes I contribute $1,250 bi-weekly and an annual return of 9% (including the compounding from the regular contributions). At my current pace, Im also looking to retire at 50 with about $3M. And with about $11M if you consider the typical retirement age. Going from 3M to 11M is kinda crazy and may encourage me to retire later lol Of course, 9% is not guaranteed but this is what I have in my plan. For now, I’ll keep buying $XEQT (and some smaller ETFs) every paycheque and stay consistent. If you were in my shoes, would you consider retire with the 3M or wait for me to retire at 65 with the $11M?
3,182 views
14 Comments
JC @icedragon · 14d
Setting a age date is good goal to have. Where you are today with net 140k, goal to have 1M net at 40. It still would all depends on how you going to tap into that 1M or 5M ( the strategy of living off the principle - erode the principle and/or live off the dividends it generates) and your cost of living/lifestyle you want. I retired in my 40's living off dividends (monthly dividend strategy) with ~1M principle, turned 50 should have ~2M EOY. I post my monthly distribution and yearly outcomes and goals. A lot can change 10-15 years from now. I got a few friends to change their investment strategy to sort of a hybrid. Primary is what they are doing, contribute a small amount or what they were saving for emergency fund to to monthly distribution to DRIP. Change it to manual re-investment when you need the money. A lot of people bypass the power of bi-weekly, weekly, monthly compounding and thinking quarterly is sufficient. Test the water, being outside the circle and making option and assumptions vs being inside a circle as different perspectives that only comes with experience.
Sunil Lalwani
@sunil1985 · 14d
I’d probably look at it as financial freedom rather than retirement. If I reached $3M by 50–55, I’d want work to become optional—not necessarily stop completely. If I still enjoy working, I’d keep going; if not, I’d focus more on myself, travel, family and life. Going from $3M to $11M is amazing, but I wouldn’t chase the extra $8M just for the number. For me, the real goal would be: “I don’t have to work anymore, but I can if I want to.”
Carlos L@retirement_rants · 14d
My advice… Go when your investments comfortably make more than your salary. Don’t forget that your investments can still grow in retirement. That’s the key!
Eddie
@mokeylock · 13d
I'm on the other end of the age spectrum... different perspective. You can accumulate wealth to extend your lifestyle. You can't accumulate time to extend your life. You simply spend it. In your "JOURNEY" take time occasionally to reflect on both your time and wealth and find your happy balance between the two.
See the full comment section 👀Sign up for the full Blossom experience!