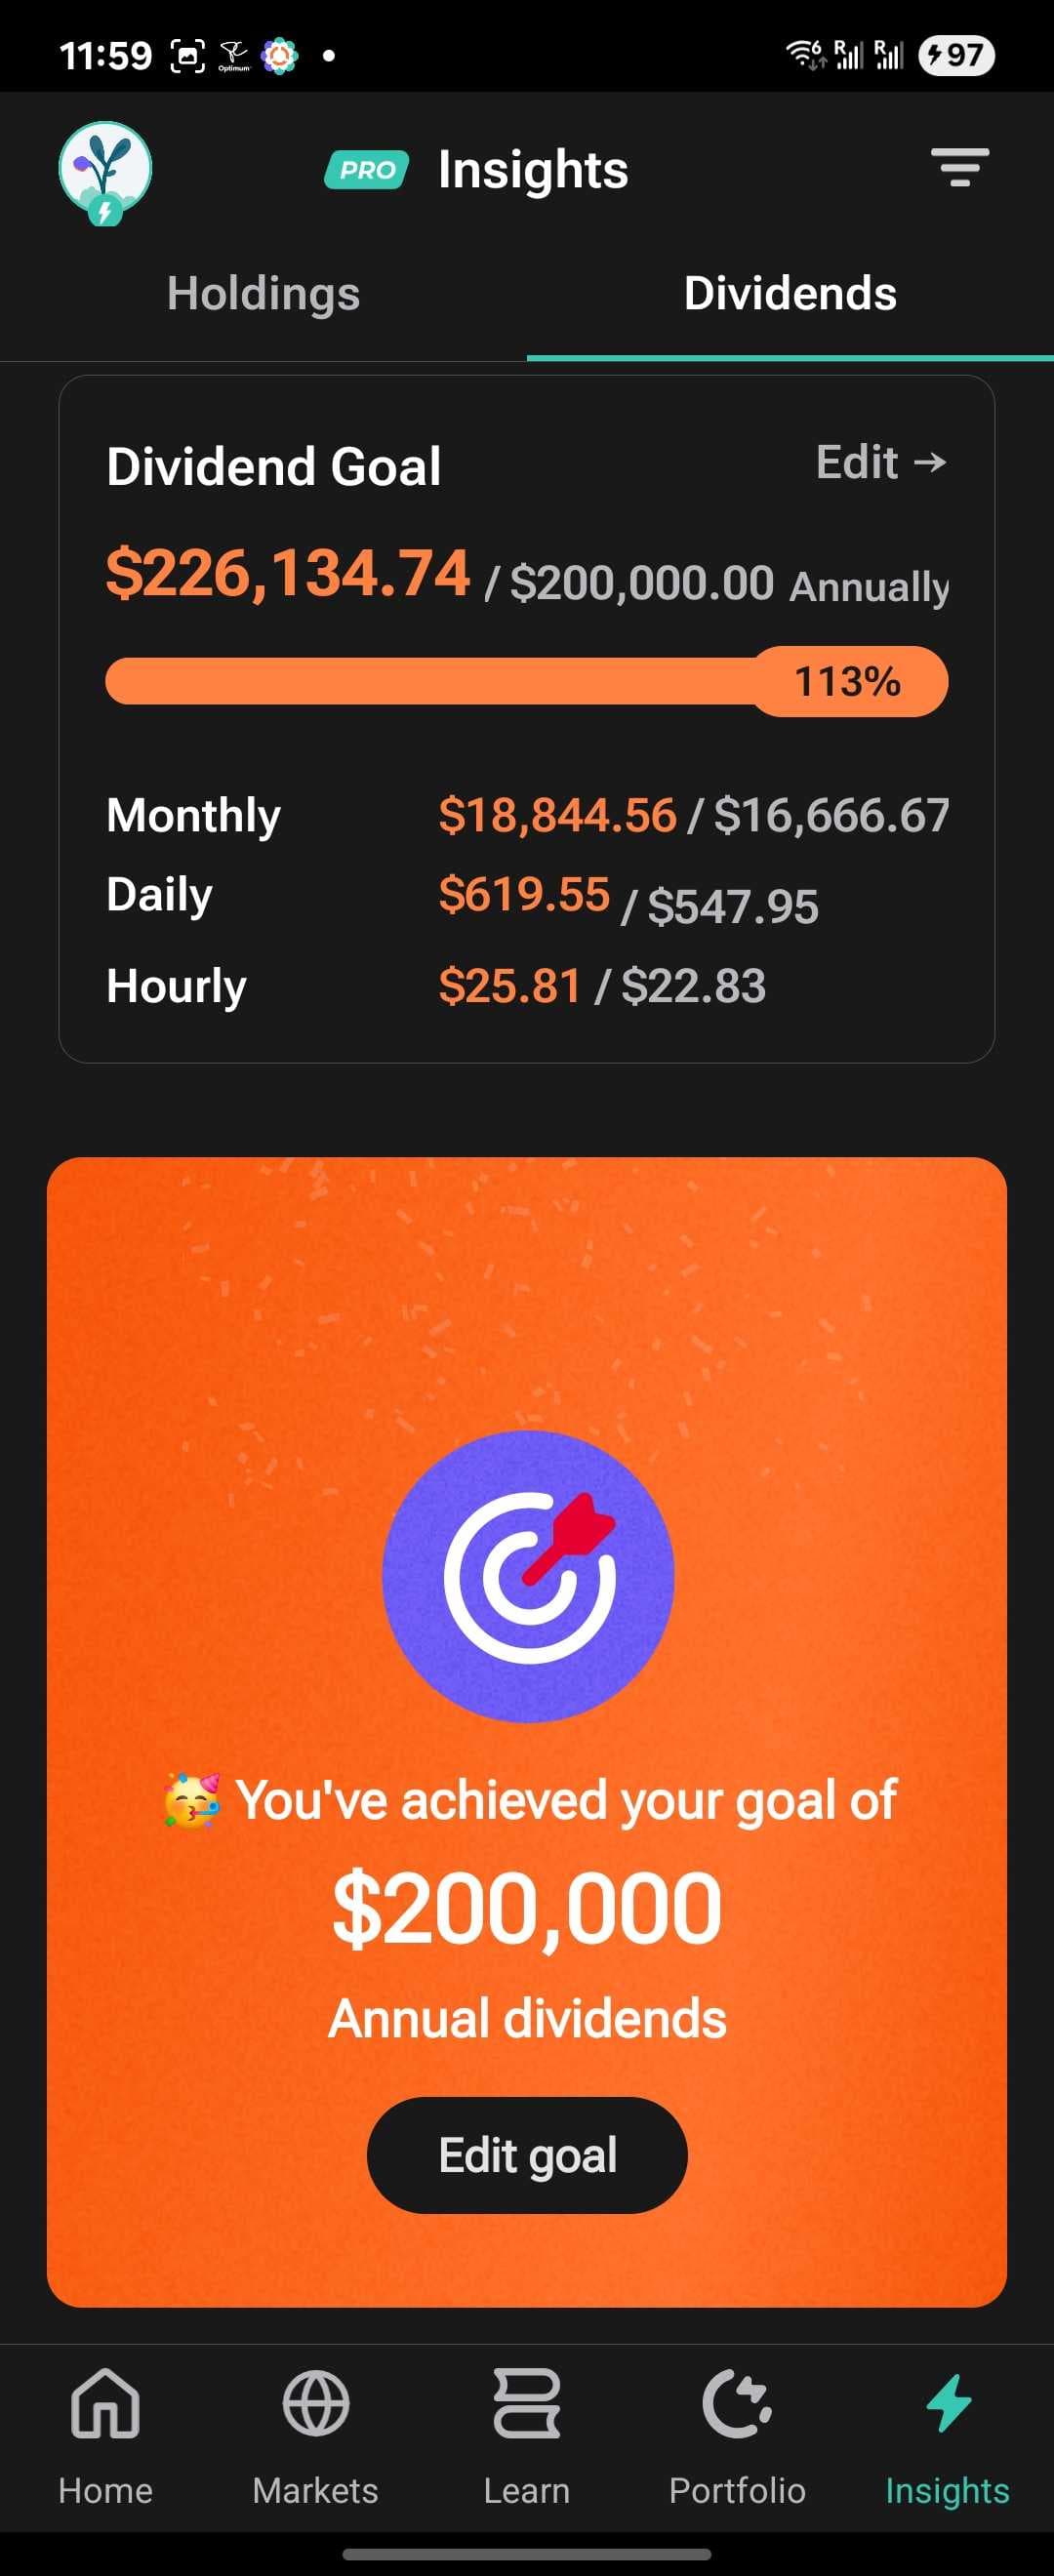
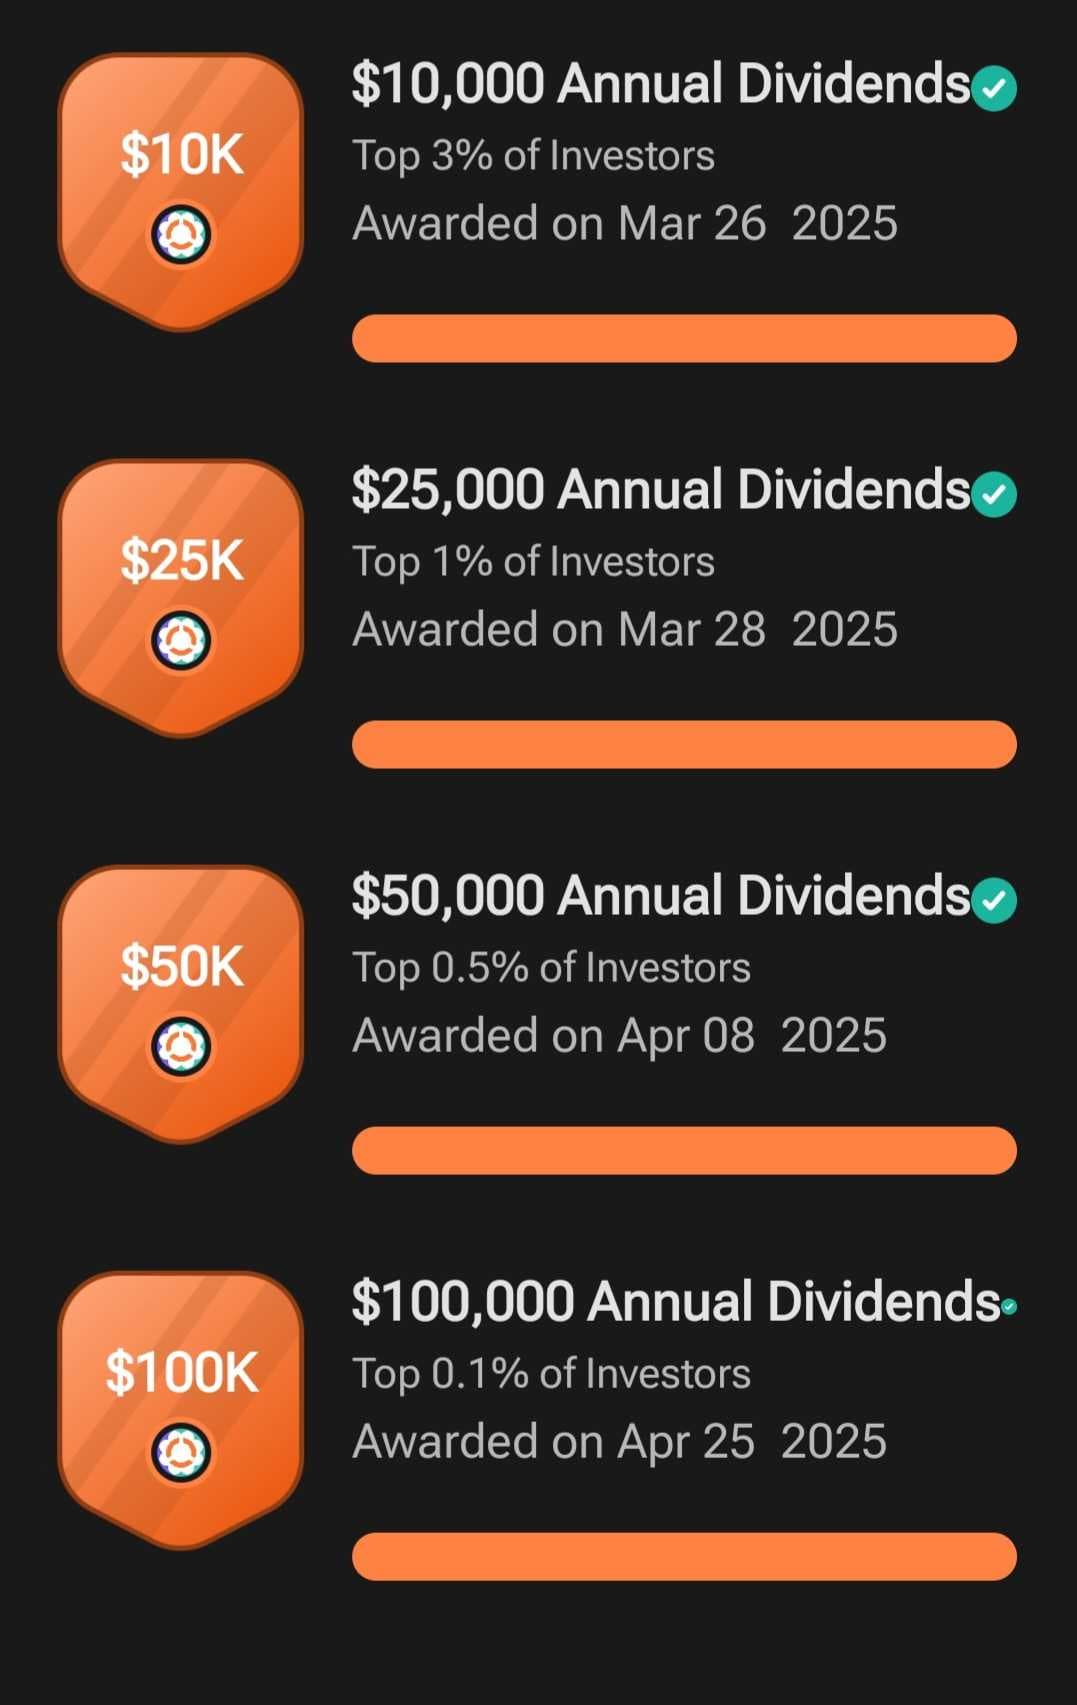
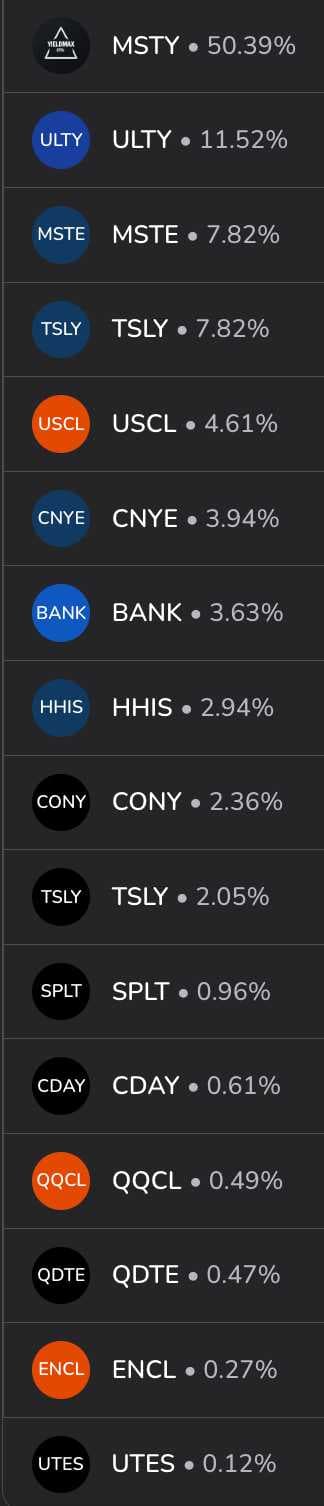
🚀 $25K to $225K Annual Income in Just 5 Months! I set a $200K annual income goal, but I honestly didn’t expect to reach (and surpass) it this quickly. It’s forward-looking, of course, and I know distributions can get cut depending on market conditions—but it’s still a milestone worth sharing openly. I’m posting this a week late since work has kept me a bit tied up. Back on March 28, 2025, my income run rate hit $25K/year. By my June 2025 update, I had already jumped from $2.4K/month to $9K/month within just three months after a major strategy shift (Liberation Day). 👉 https://www.blossomsocial.com/posts/June-2025-Distribution-Update-and-Income-Growth__POST-1751865798703-MG4aX3Kd_4eq0X8gvkvUnr6Yj At the time, I wrote that I was working toward a $200K annual income goal—but never imagined I’d hit it this soon! 🎯 Original Plan Goal: $200K income → then switch new contributions back to growth ETFs. Reason: I treat this income stream as an all-purpose emergency fund. Reality: I don’t need $200K+ income. But distributions are volatile—if they dropped 50%, I’d still be covered. That’s why I aimed high. 🤔 Next Steps Now that I’ve reached the target much earlier than expected (was thinking early 2026), I won’t rush decisions. I’ll continue with income investing until Apr 2026, completing one full year of data since the strategy shift. At that point, I’ll re-evaluate. I definitely plan to shift some new contributions toward growth ETFs. Currently holding: Growth: $HULC , $ZID Hedge: $SGOL Watchlist: $SPMO , $AOTG , $USSL (Open to suggestions for better total return growth ETFs—not VOO/VFV, but pure growth beyond SPMO). 📊 Current Income Forecast (rounded) $MSTY – 50% (Yieldmax) $ULTY – 12% $TSLY – 7% (Yieldmax) $MSTE – 7% $USCL – 5% $CNYE – 4% $BANK – 4% $HHIS – 3% $CONY – 2% (Yieldmax) $TSLY – 2% Others ($SPLT , $CDAY , $QQCL , $QDAY , $SDAY , $QDTE , $ENCL , $UTES ) – <1% each 🔄 Rebalancing Plan Remove duplicates over time. Slowly phase out MSTY, TSLY, ULTY, CONY (YieldMax ETFs) and retain Harvest equivalents. Reason: I avoid USD funds outside RRSP due to foreign income tax and also contribution room currently limits my ability to add during dips. My margin account instead gives more flexibility and CAD funds mainly distribute ROC and Capital Gain which are tax efficient. Challenge: Since a big chunk of my income comes from MSTY, reducing dependency will take time. Plan is to increase allocation to the <1% ETFs mentioned above. 🙏 Thank you all for following along. This journey has moved faster than I thought, but I’ll stay disciplined as much possible and keep sharing updates transparently.
5,668 views
50 Comments
Golden Pancake@free2068 · 1yr
That’s some insane growth in just 5 months 👏 congrats on smashing through your goal that fast! Quick question though—how much extra capital did you have to deploy along the way to make that jump possible, or was most of it from reallocating into the higher-yield plays?
Nimesh Virani@nimeshvira · 1yrEdited
Congratulations! Great jump and thanks for sharing the progress. I have a question, what do you mean by "not VOO/VFV but pure growth beyond SPMO"?
Kotoula
@kotoula · 1yr
Hi @prem82 I'm really inspired by your posts. My portfolio is only 96k, what steps should I take to get on this road you're on? Just try to copy your trades or your % of allocations in each position? Do you have any beginner friendly advice?
szncor @szncor · 1yr
Hey @prem82 How did you get to $200K with only a $600K portfolio? I must be doing somethjng wrong. My portfolio (RRSP, cash and TFSA) is $800K and I only get $8K month. Your ETFs are not all CC ETFs. How did you get to that amount?
See the full comment section 👀Sign up for the full Blossom experience!