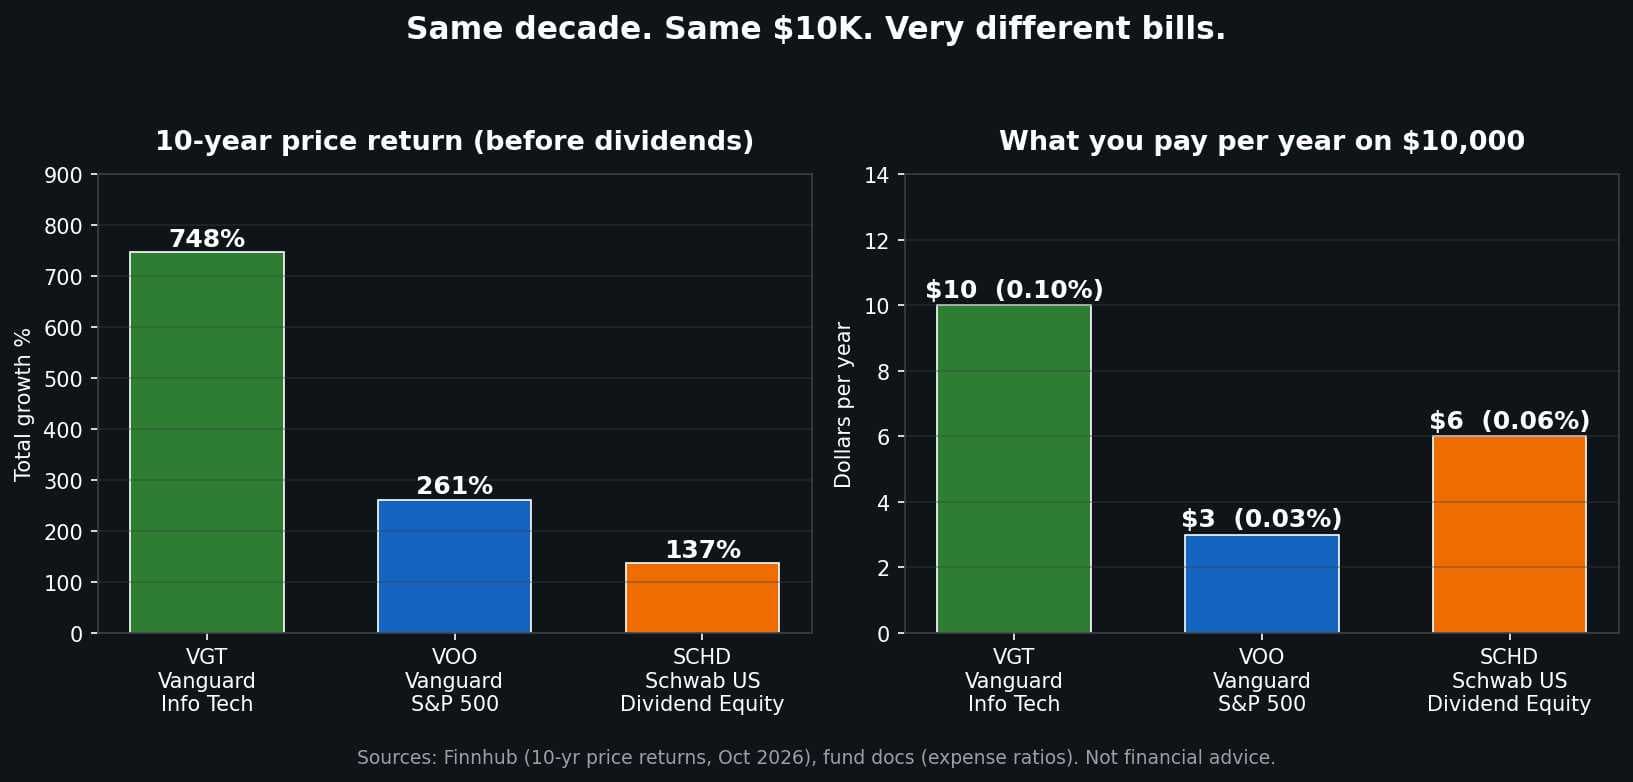
SCHD holders brag about the dividend. VOO holders brag about the growth. 10 years, dividends reinvested: $VOO : 316.5% $SCHD : 244.5% That's a 72 point gap. On $300K that's about $216K left on the table. SCHD's answer: a 3.2% yield vs about 1% for VOO. Cash in hand every quarter. In a rough year, that dividend check feels GOOD. My stance: I'm a growth guy. I want the compounding, not the coupon. Long-term buy & hold for me, I'll take the extra 72 points. But dividends aren't nothing. A payout that shows up rain or shine is real money. Which side are you on? The 3.2% yield now or 72 points of growth over 10 years? Where do you stand? 👀
1,576 views
11 Comments
Andrew Whiteside
@dumbmoneyrewired · 22h
IF you have 30 years to compound the dividends on SCHD then it’s worth it. Your yield on cost would be massive upon retirement time. Anyone starting with less than a 30 year time horizon is leaving money on the table it it’s better to go with growth. However I agree with @mruby14 SCHD is better for those that want to say “I’m investing” but don’t want to deal with as much volatility or risk of loss of capital. It’s a glorified savings account with a compounding yield.
Matthew Ruby
@mruby14 · 1d
Love this breakdown. Personally I think $SCHD is better for people who are more emotional as it provides the downside risk protection over the s&p, and also gives that stable dividend. For advanced investors who know the market and can stomach drops and buying the dip further, $VOO is clearly the winner. While you will obviously make better returns even with drip in VOO, I think there are some metrics that don’t show up on paper that SCHD outperforms in.
Mike L
@noviceadvisor · 7h
I'd rather hold SCHD as VOO is being propped up by 10 or so companies. Those 10 companies tank? Voo is in the toilet
Marcus
@11marcus · 4hEdited
SCHD is really just another ETF that pays dividends from inside the fund. It’s no different from a making a withdrawal from your growth portfolio. People like the dividends due to psychological comfort. Unfortunately people don’t realize that on the ex-dividend date tthe price adjustment decreases EQUATING to the fund withdrawal process. It’s the same as making a withdrawal from your growth portfolio. Your portfolio drops in the same manner. Thus, you begin to realize the argument of holding on to your shares for the sake of receiving dividends is really just an illusion 😅 If people truly understand the mechanics of dividends paying assets, I don’t think these funds would have as many investors as they do now 🤷🏽♂️
See the full comment section 👀Sign up for the full Blossom experience!