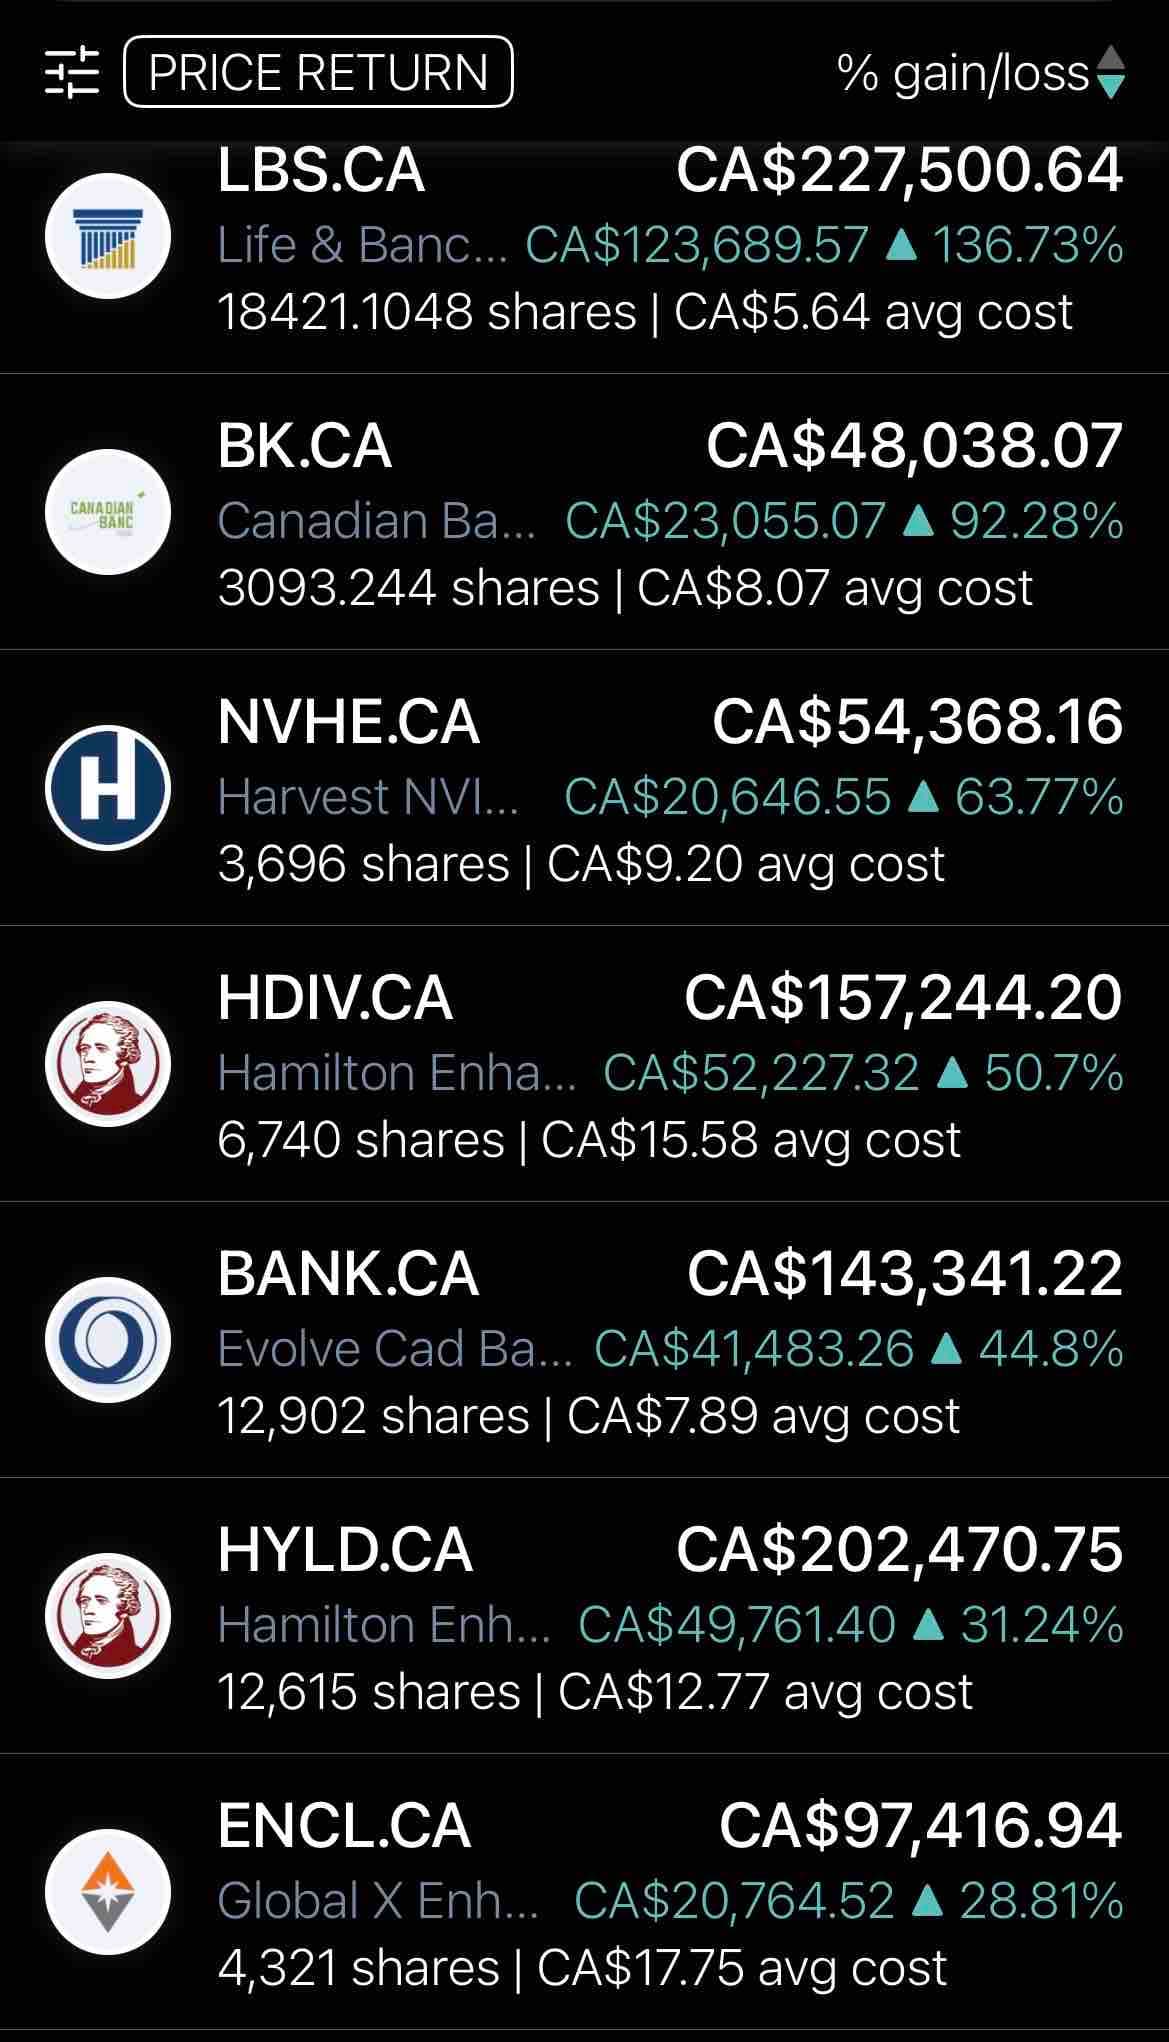
Hello everyone, I am not asking for advice, I just wanted an opinion if what I am doing is right or if I leave things as they are. I started my TFSA with Wealthsimple from scratch in July 2019. I contributed around 60k to date and now it's standing @ 92k From outside, the portfolio looks like it did a good job in 7 years but when you see the details it performed below average because the portfolio was build literally 1 share at a time and since Wealthsimple introduced fraction shares, I started doing that as well and every time I have excess money I dump it in there. The problem now is that I have 55 holdings (mixture of individual Stocks + Various ETFs) Some positions are very big and some are very small. Some performed well and some tanked. As of last week, I did a review of my portfolio and decided the following: Consolidate all my holdings from 55 positions down to 5 ETFs from the same issuer. I selected iShares and my plan is to build a portfolio that is (XEQT 60% - XBB 20% - XEI 10% - XQQ 5%- XEF 5%) I already own XEQT in my current portfolio. The plan is to keep this allocation as is for at least 5 years and rebalancing it to (XEQT 45% - XBB 35% - XEI 10% - XQQ 5%- XEF 5%) for another 5 years. The goal is to grow my portfolio from 92k to at least 150k in the next 10 years. I am contributing $100 biweekly to this portfolio - This might change in the future. I am 57 yo and I would like to spend less time tweaking my portfolio when I retire in the next 5 years. Is this a good strategy for the future? I am not asking for investment advice....I just want your insight if you please. Also, when I am making all these sales and purchases within my TFSA...Am I going to flag my account with CRA? Thanks read more
👥 Two Friends, Two Very Different Retirements Meet John and Nancy. Both start investing at age 25. Both contribute exactly $200 a month until age 65. Both put in exactly $96,000 of their own hard-earned money over 40 years. They invested in the exact same equity market, which grew at an average of 8.00% gross annualized. So why is one of them $264,000 poorer at retirement? 📉 John: The "Standard" Bank Mutual Fund John went to his local branch and was sold an average Canadian equity mutual fund with a 2.10% MER. Net Annual Return: 5.90% (8.00% minus 2.10% fees) Final Nest Egg: $387,838 Est. Monthly Income (using SWR 4% rule): $1,293/month 🚀 Nancy: The Low-Cost Index ETF Nancy went the DIY route, using a self-directed account to buy a broad-market index ETF with a 0.20% MER. Net Annual Return: 7.80% (8.00% minus 0.20% fees) Final Nest Egg: $652,504 Est. Monthly Income (using SWR 4% rule): $2,175/month 📊 The Brutal Math Because of a seemingly tiny 1.90% difference in fees: • John lost 40% of his entire potential nest egg to the bank ($264,666). • Nancy gets $882 more every single month to spend in retirement. It wasn't because Nancy worked harder, saved more, or picked better stocks. She just didn't pay the bank to do what she could do herself for next to nothing. 💡 The Nuance Of course, this assumes both reinvested 100% of dividends and that tax drag remains equal (e.g. within a TFSA or RRSP). It also relies on standard nominal SWR metrics. However, even with inflation or taxes, the fee-percentage relationship remains devastatingly constant. Small numbers over 40 years are massively amplified by compounding. If you wouldn't give away 40% of your paycheck to an advisor, you shouldn't let them take 40% of your future. What age were you when you realized how destructive MERs could be, and did you immediately move your funds out of traditional mutual funds?read more
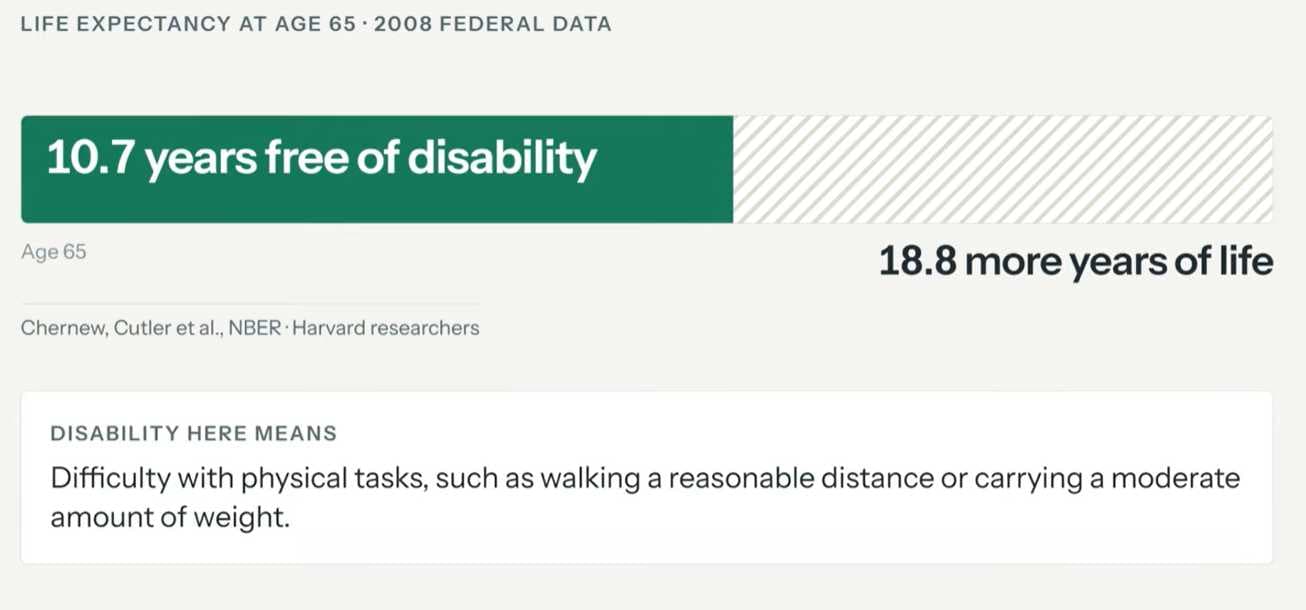
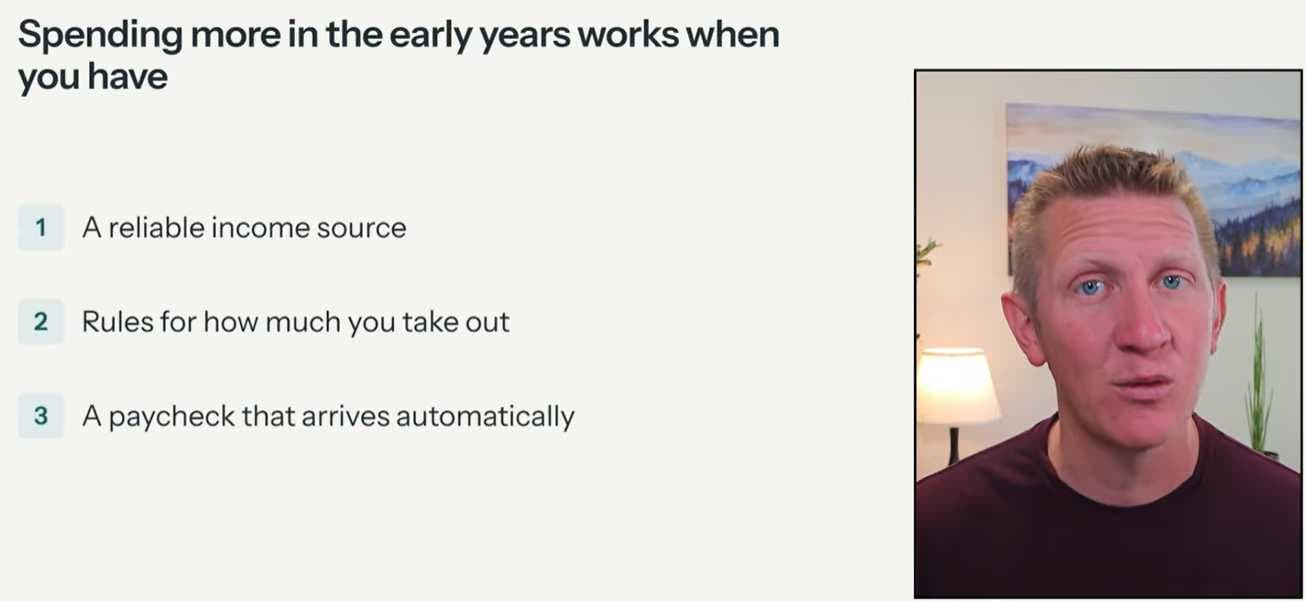
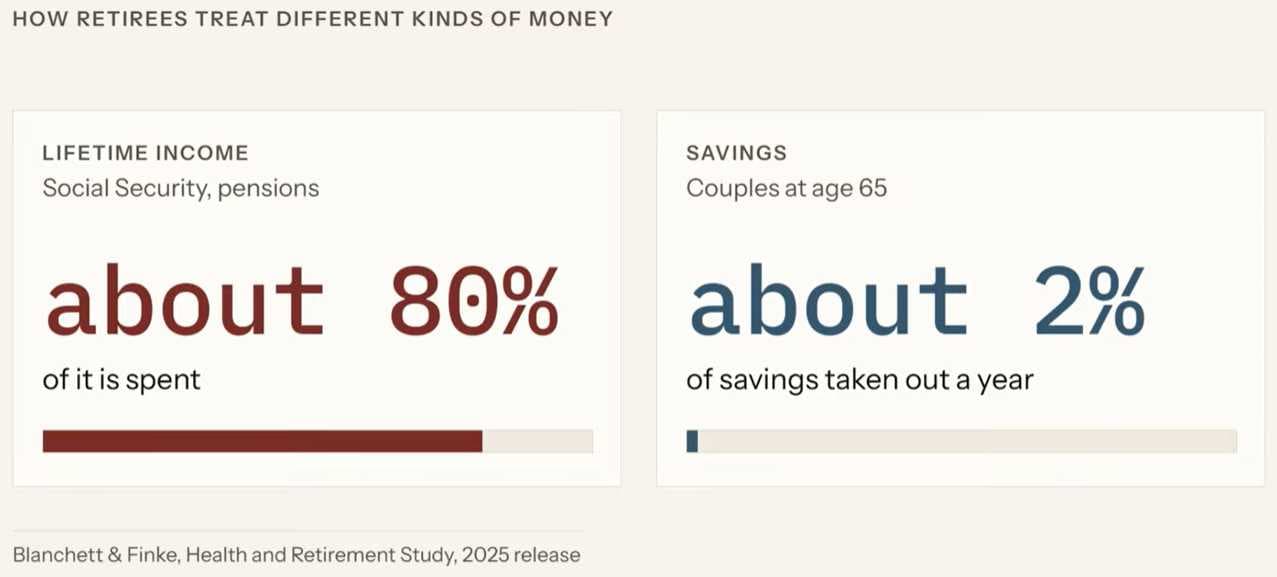
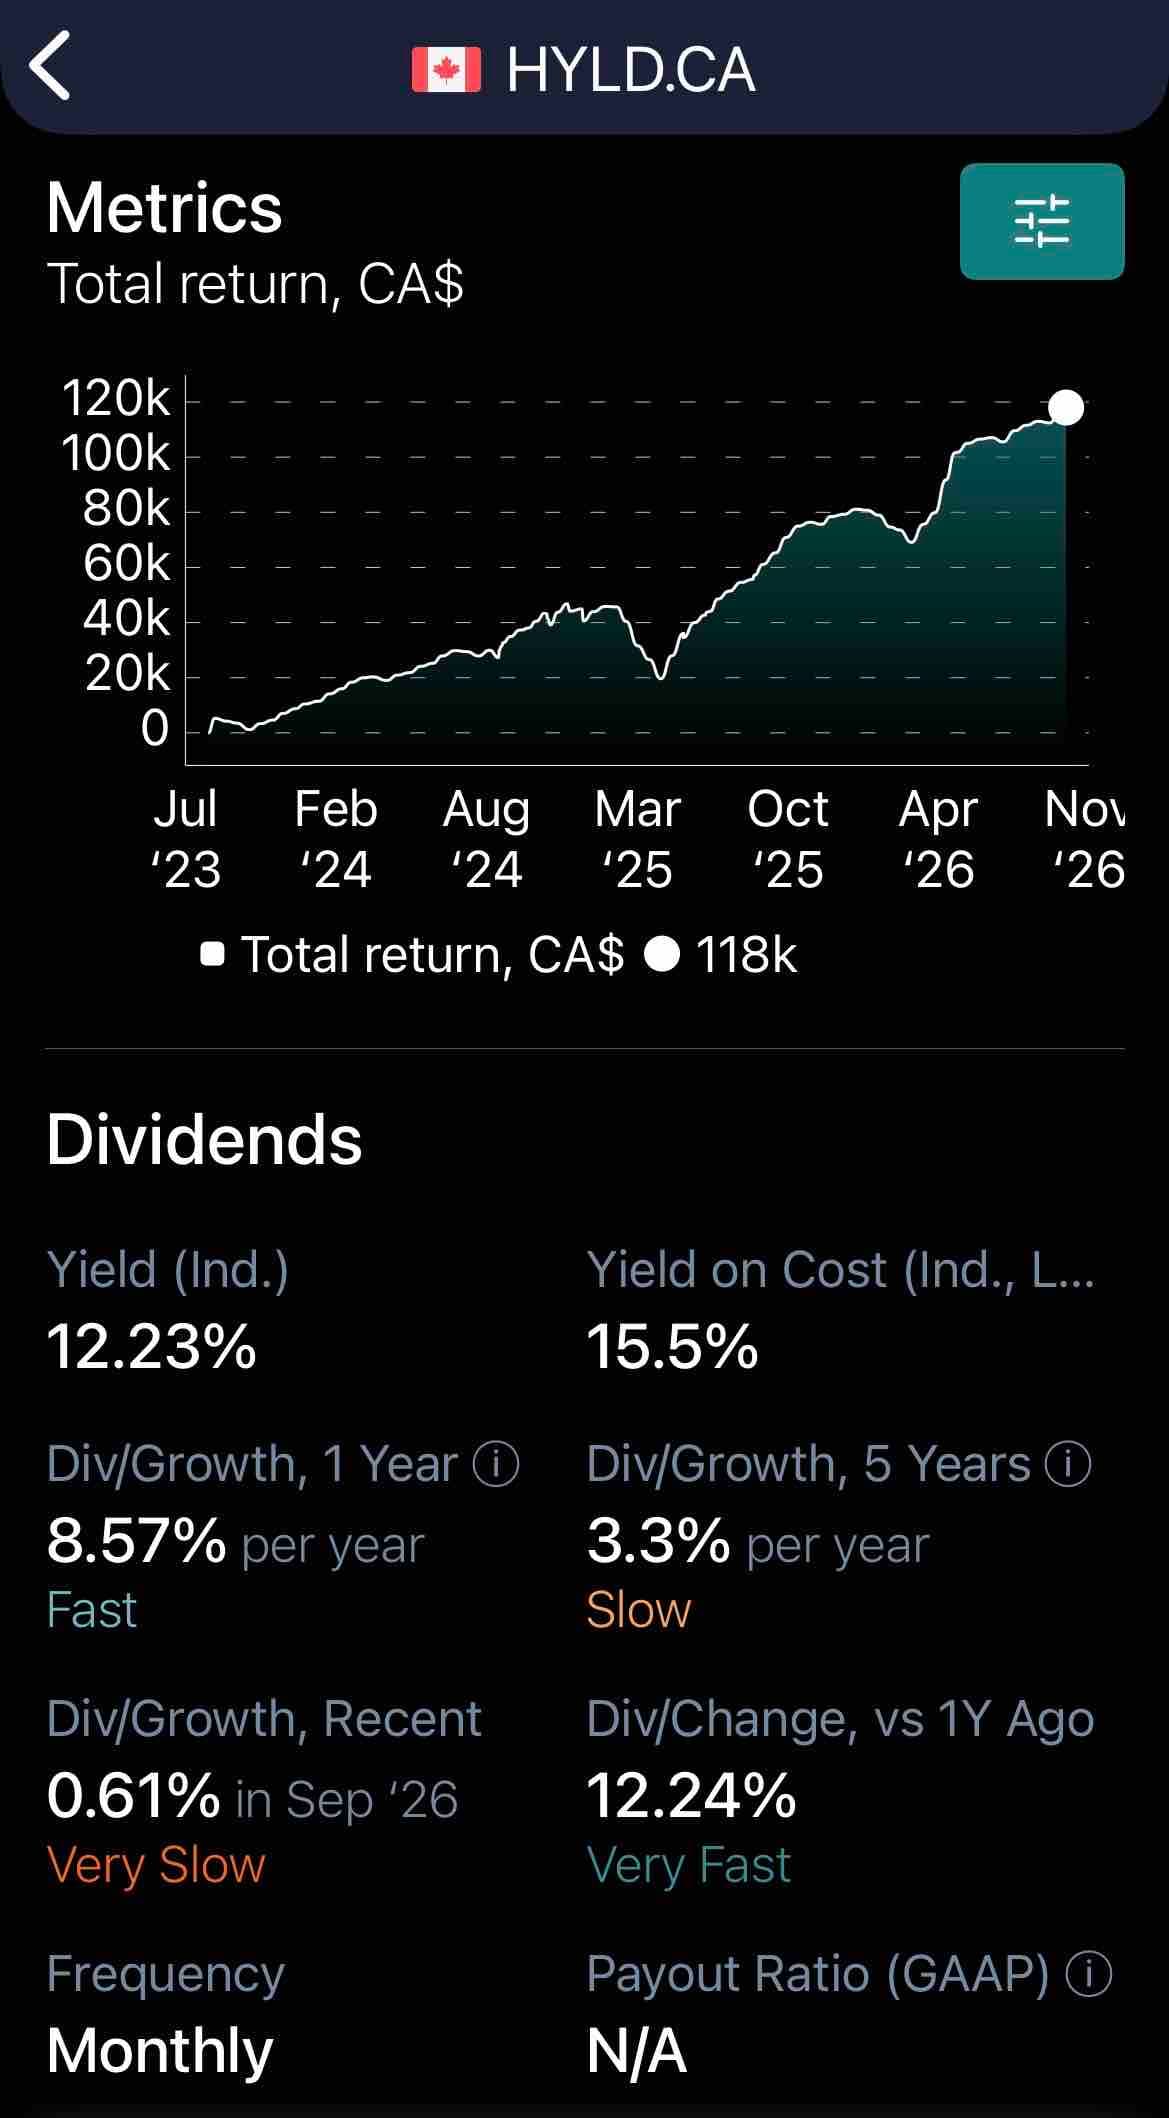
... is the title of a video from Joe on his new channel Retirement Income Investor. In the video, Joe cited a few academic studies on retirement spending. They mirror many of my previous postings on : 1) life design > safe withdrawals, 2) non-linear U-shaped retirement spending, 3) auto cash deposits leading to more spending. It is good to see that my intuitions and critical thinking are consistent with these formal studies. In my 30+ years in high tech, I didn't get COLA every year. I survived pay decreases in new jobs. I even survived family court taking more than half away. Why should I blindly follow some rigid 30-year-old study that calls not adjusting for inflation every year unsafe? I rejected such fear porn. So should you. https://www.youtube.com/watch?v=DDFc_m7xUik $HYLDread more
In 2017, I left my private banker job and had to choose between a small bank pension and a lump sum. To match that pension at 65, the lump sum needed to earn about 3% a year. I moved $108,760 into a LIRA and never added a dollar. Nine years later it's worth $339,595 and has paid $37,864 in dividends along the way. Pension or lump sum, run the math before you choose. Full report: https://bit.ly/4xIeIyv
I was listening to the radio and they were talking about the government considering increasing the retirement age from 65. This is why investing for your own future is so important, regardless of your workplace pension plan or CPP. Working hard toward my goal of retiring by 55, or as close to it as possible. Hope I can achieve it!
This past month I opened a Roth IRA and have been contributing $20 a week every Friday, plus any spare change I have when the market takes a dip. But here’s my plan to make it profitable. Strategy: 1. Price point 15 individual long term growth stocks 2. Price point 4 ETF stocks 3. Requirements: all stocks and ETFs must have a 120% or higher 5 year growth. 4. Goal: buy ETF’s on market dips and individual stocks on individual dips. Here are the stocks I plan on adding to my ROTH IRA portfolio: ETFs: $SMH$VOO$VDE$VGT Individual Stocks: $GOOGL$META$LLY$HLT$TSM$XOM and the rest still undecided. Let me know what stocks you recommend for a Roth IRA. read more
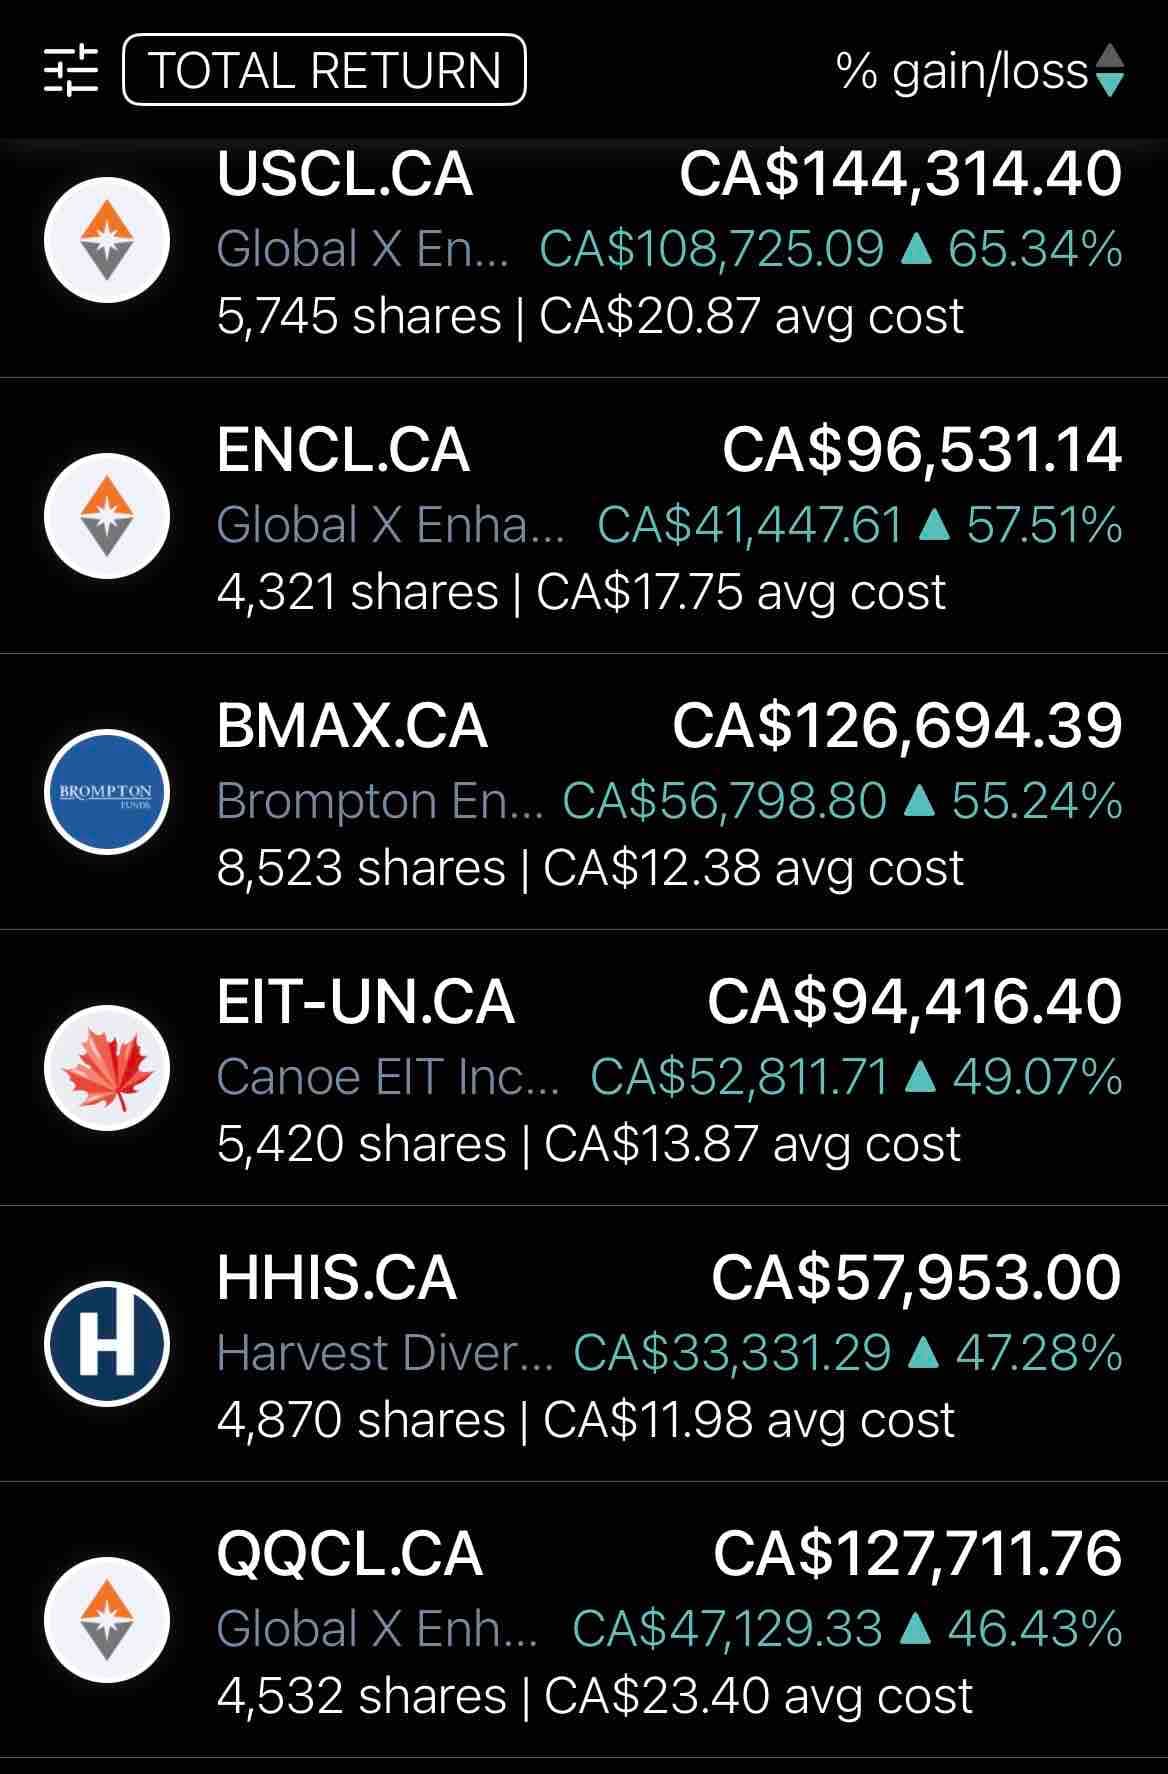
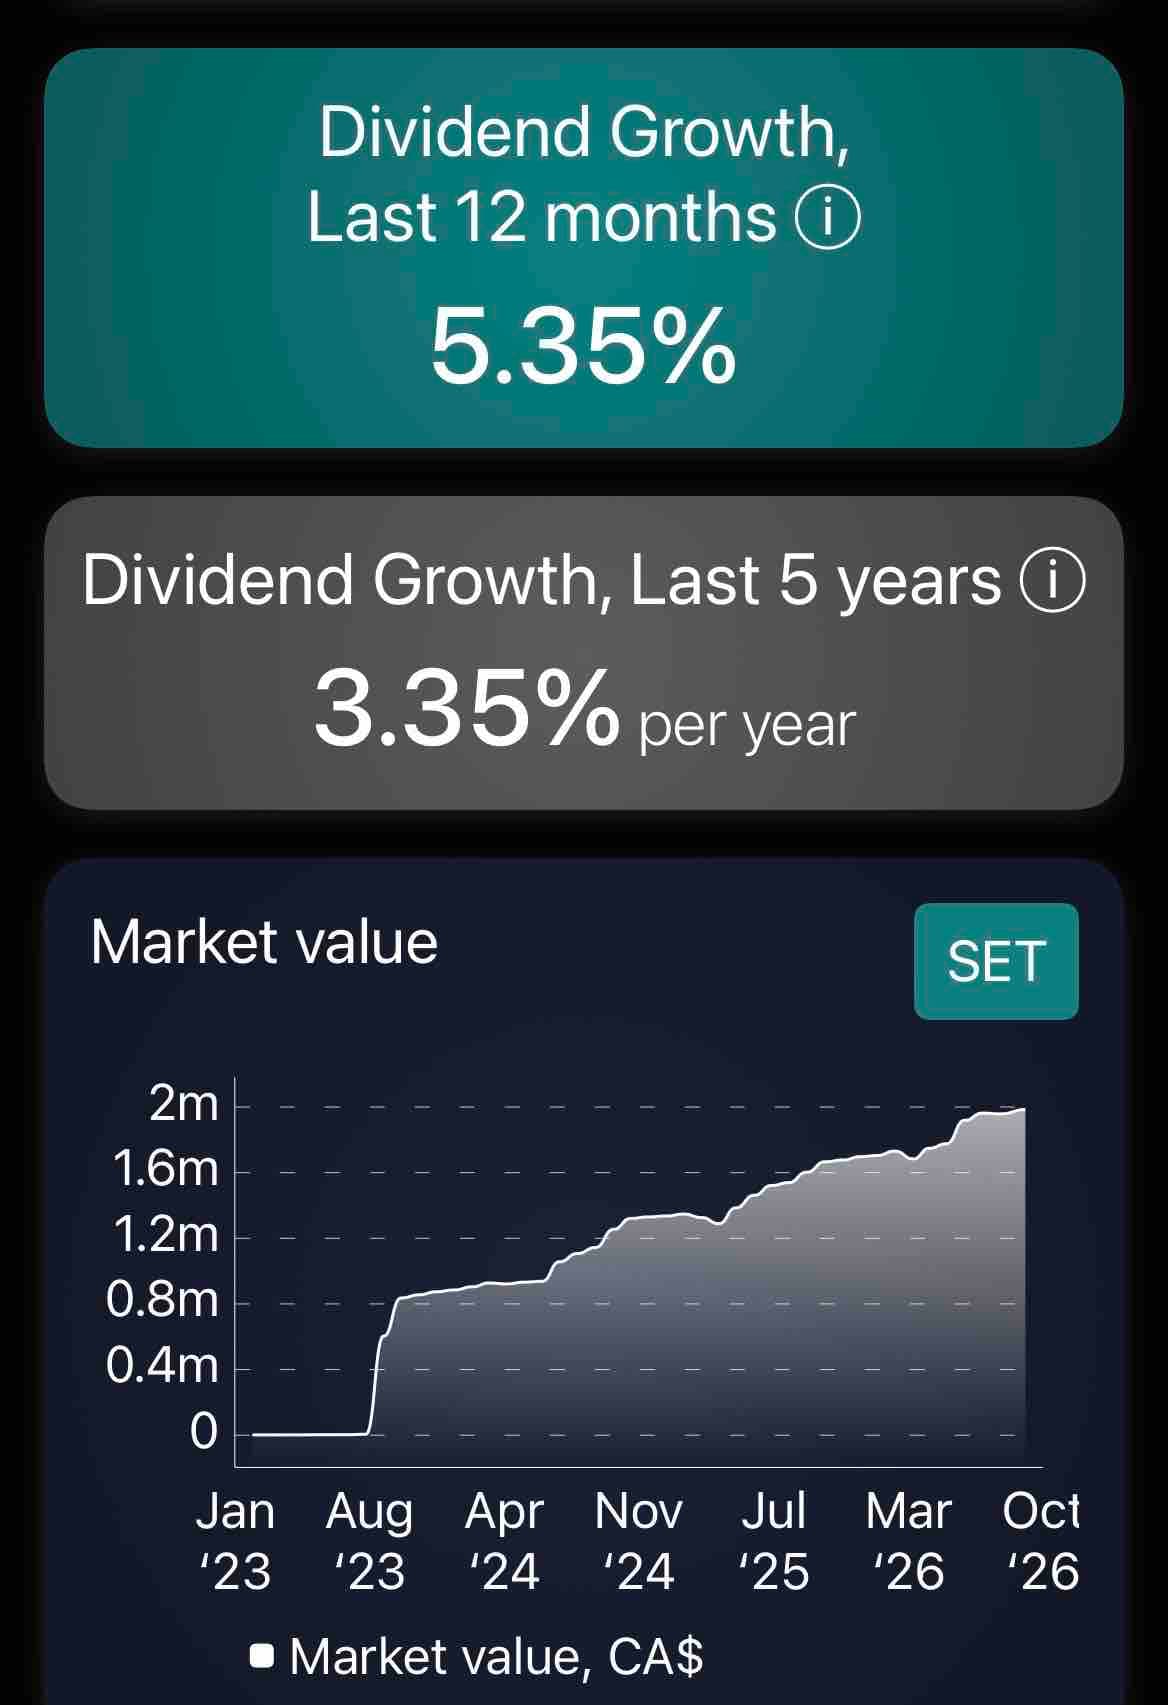
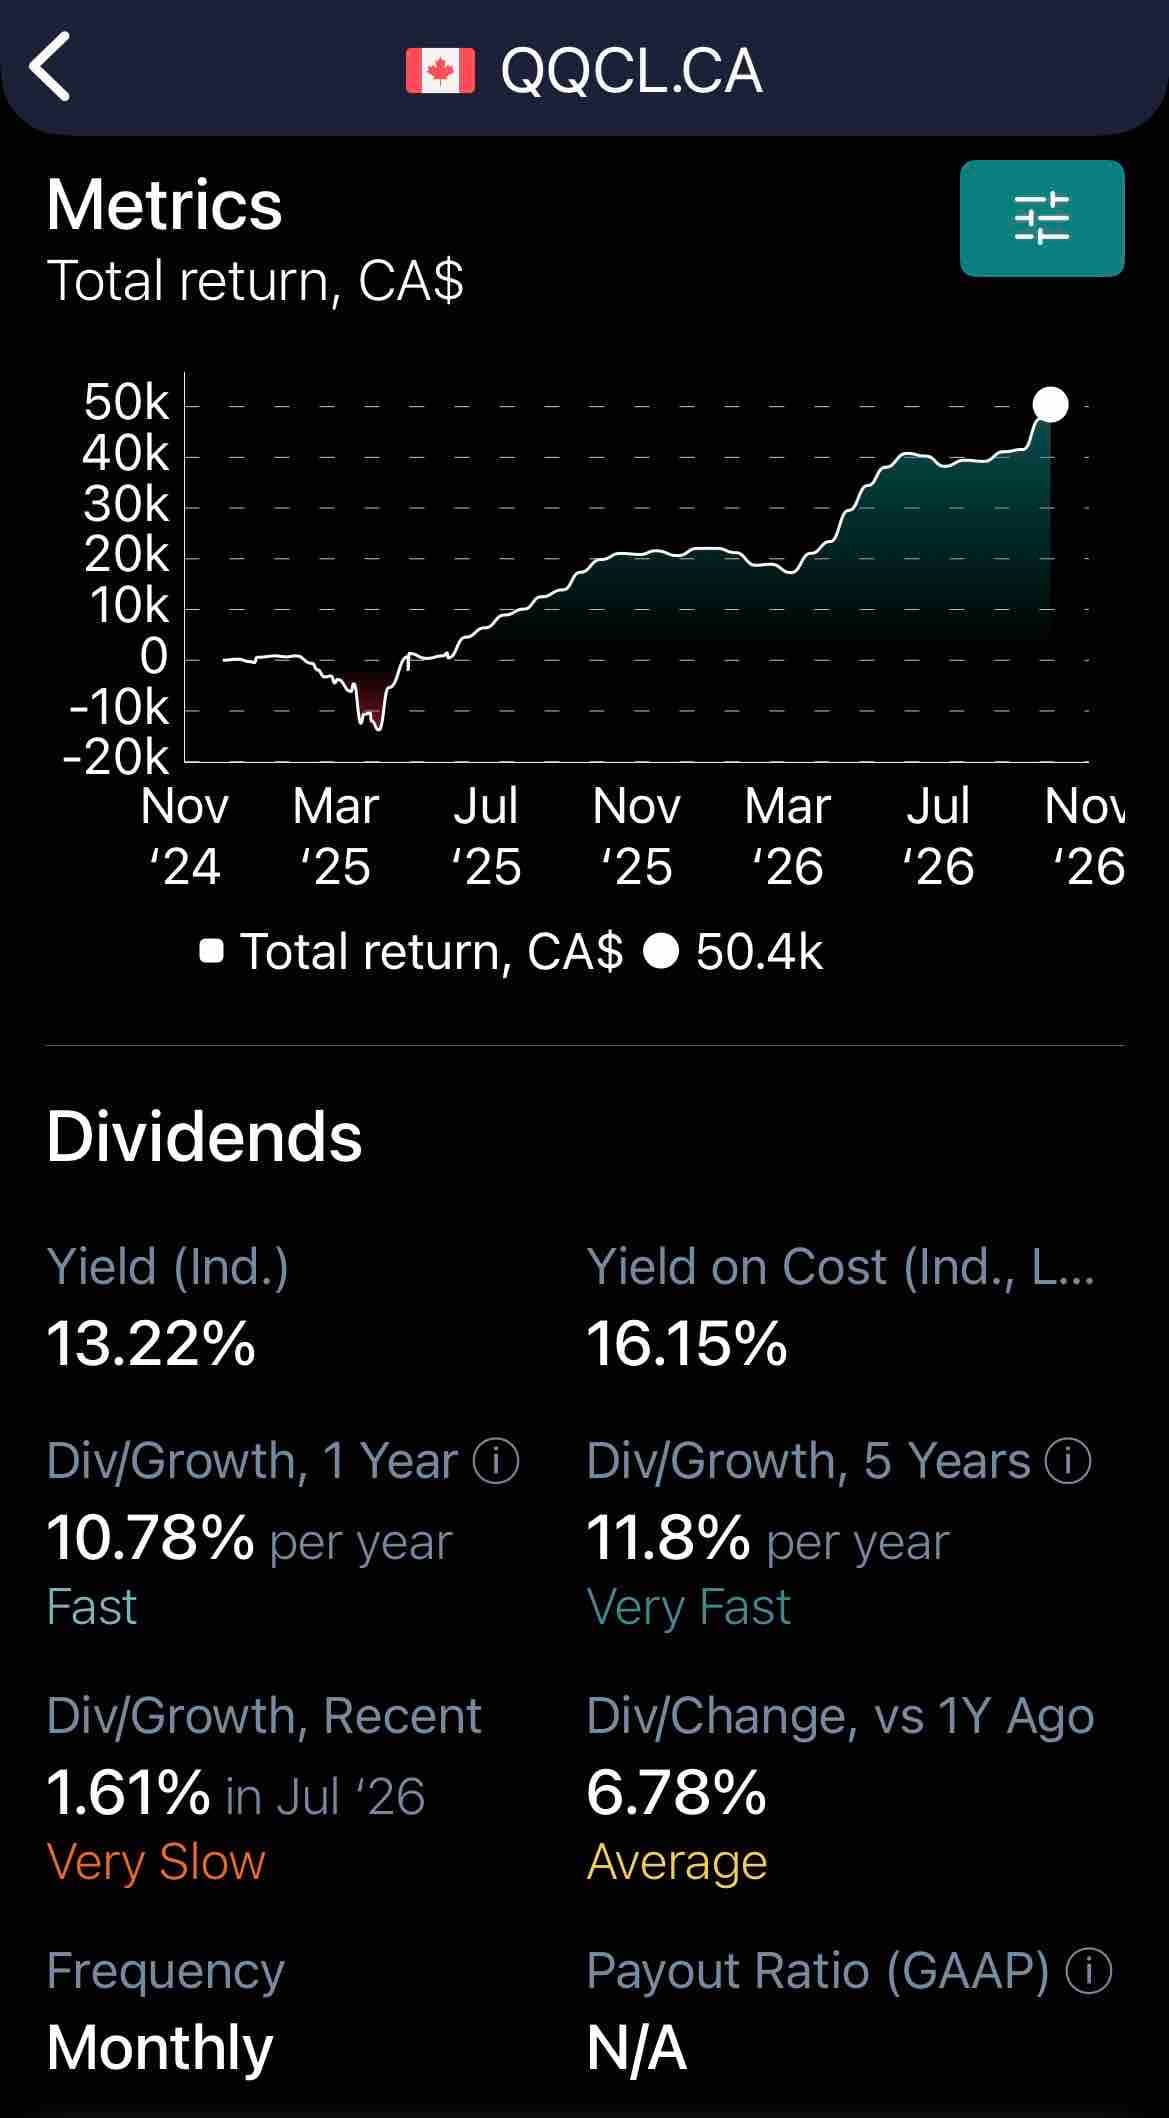
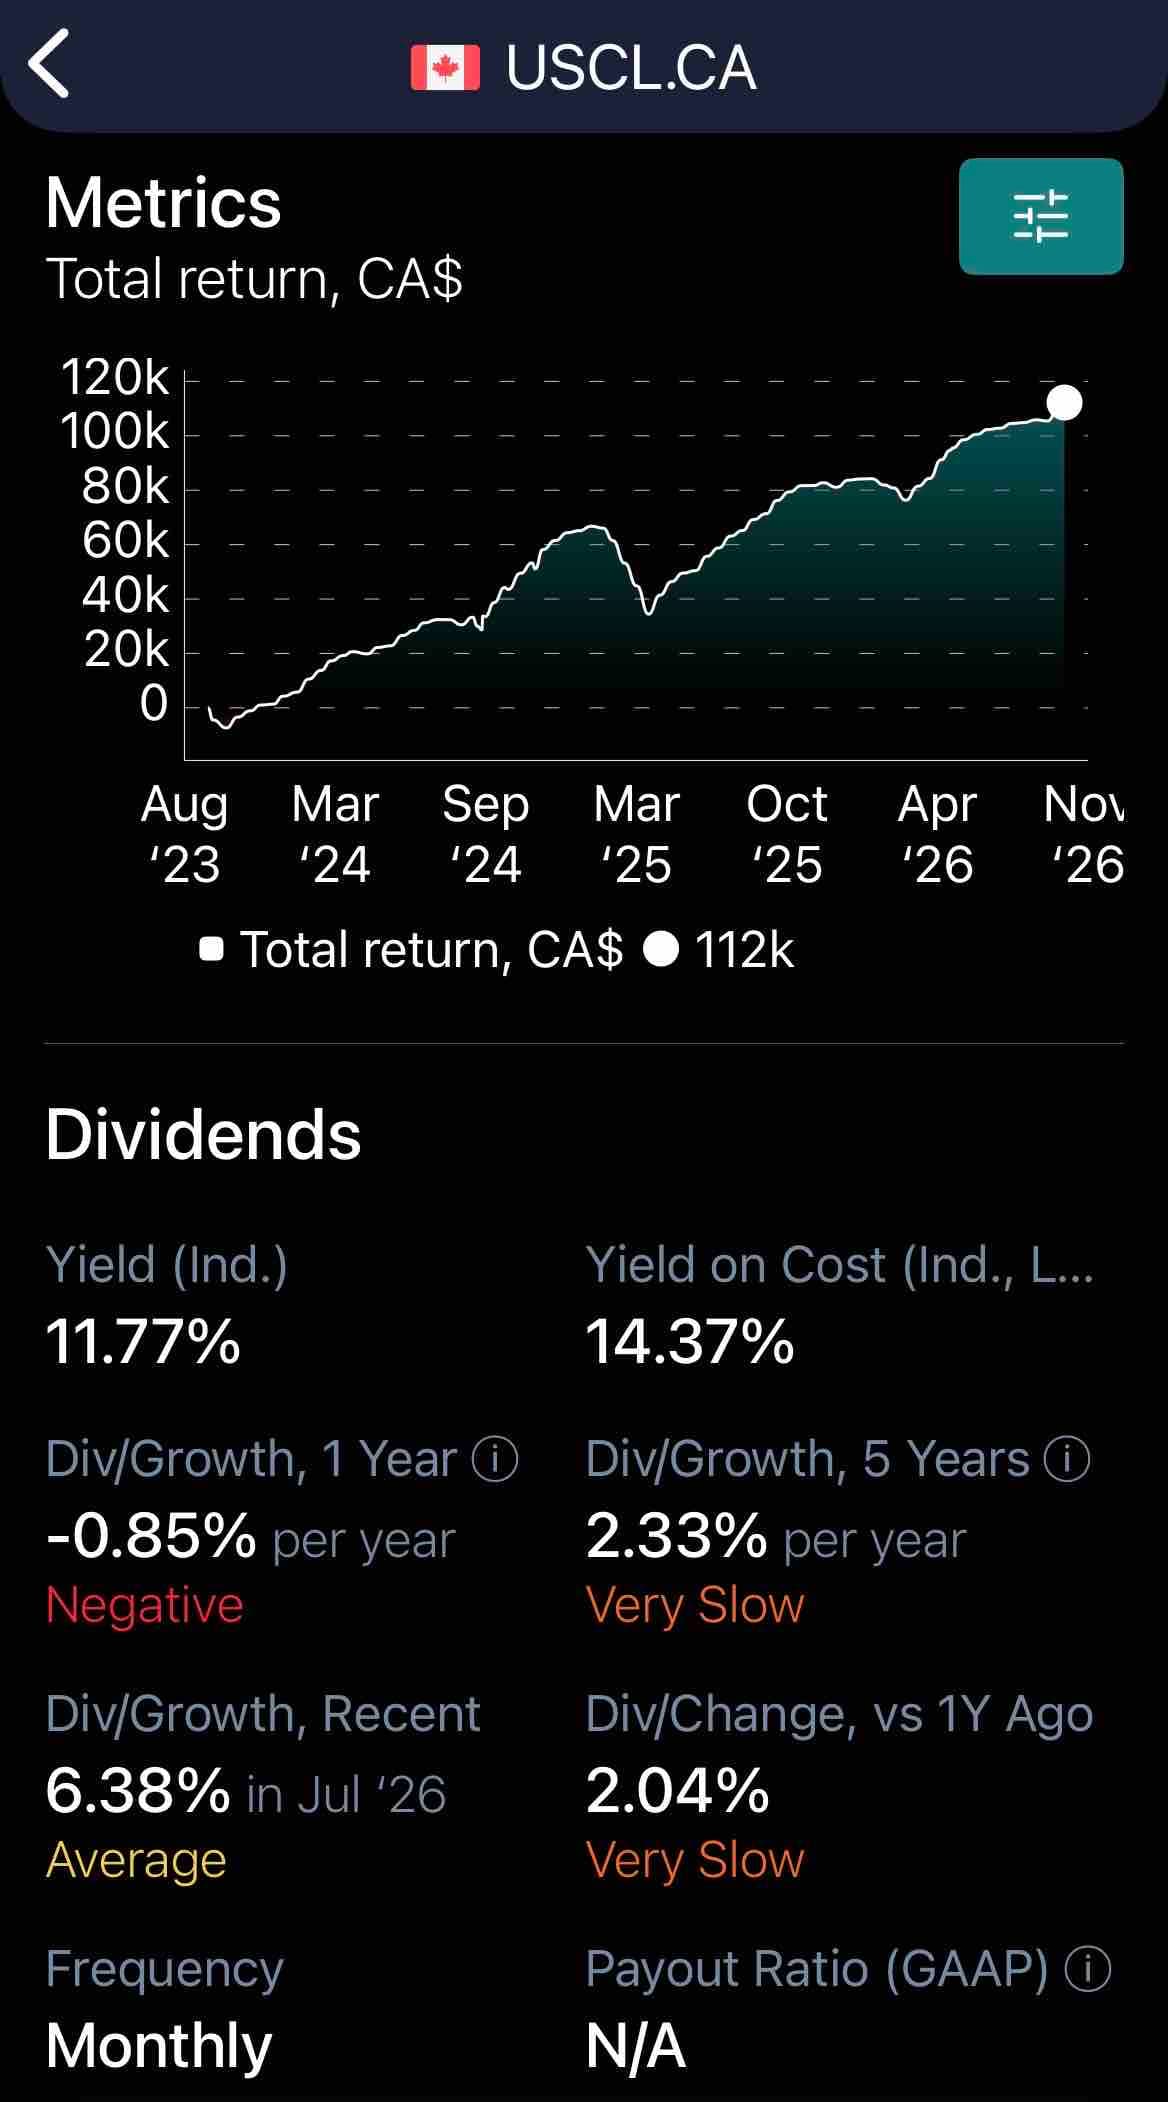
In the past 3 years I have received over $550,000 in income but without sacrificing an eroding NAV. I am still up 35% or $393,000 on NAV appreciation or growth. I added my top 14 NAV appreciating assets in the screenshots below! They range from holding over the past 3/2/1 years! Retirement is a beautiful thing!! Always do your own research 🧐 and analysis 📊 read more
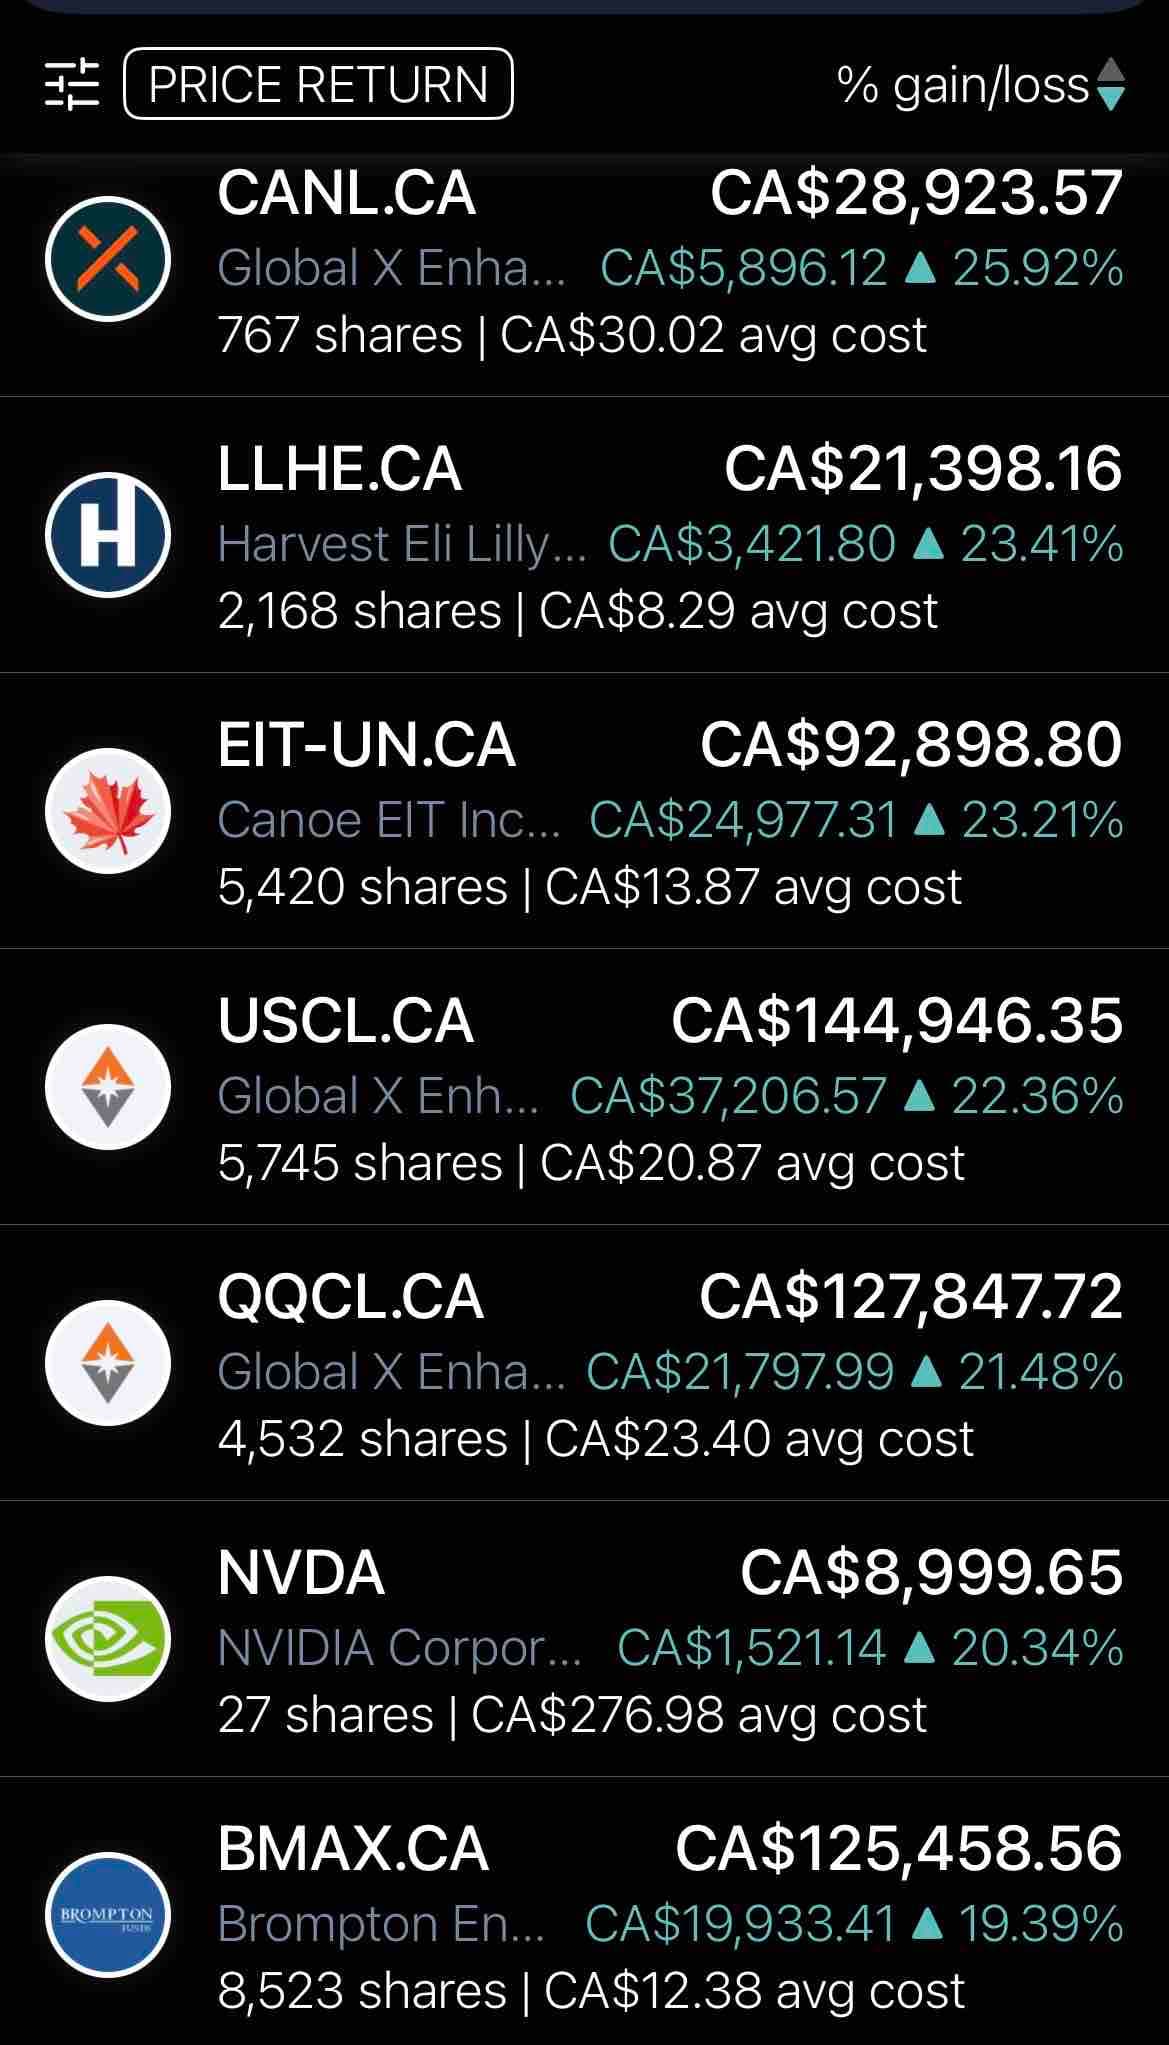
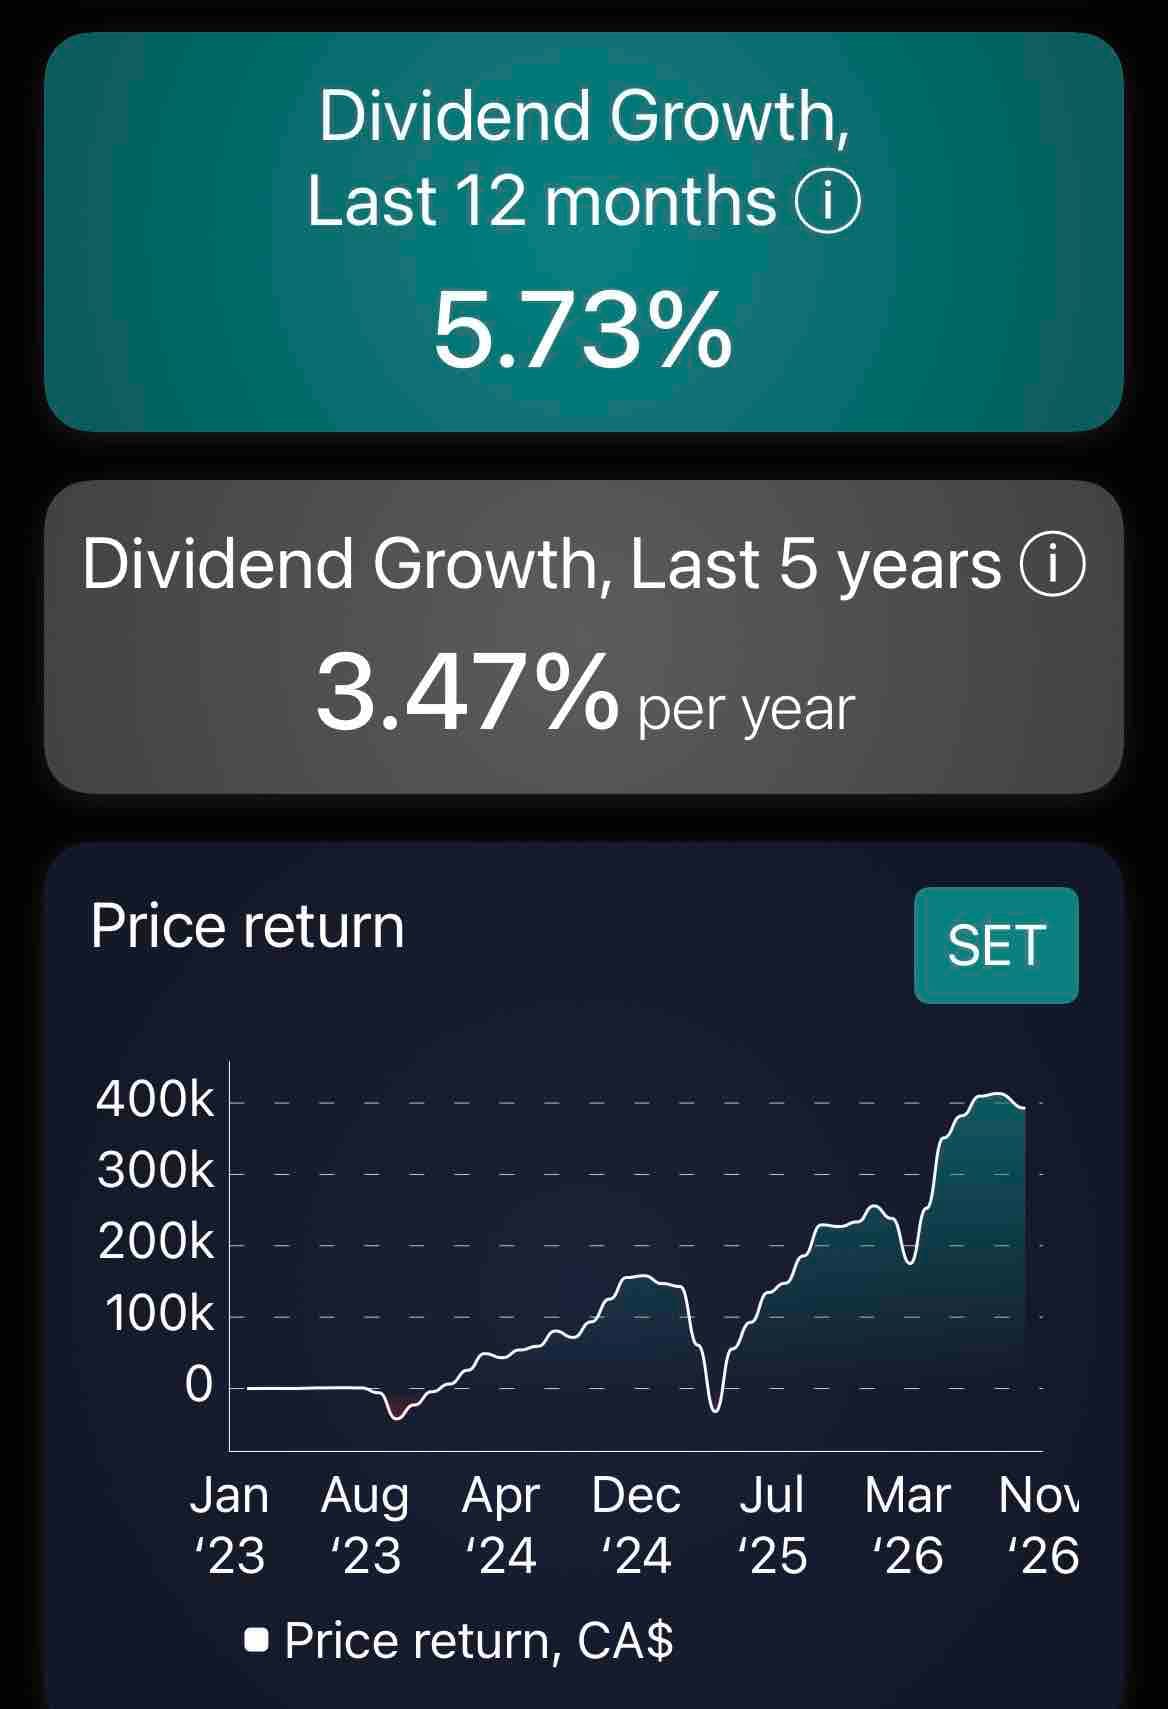
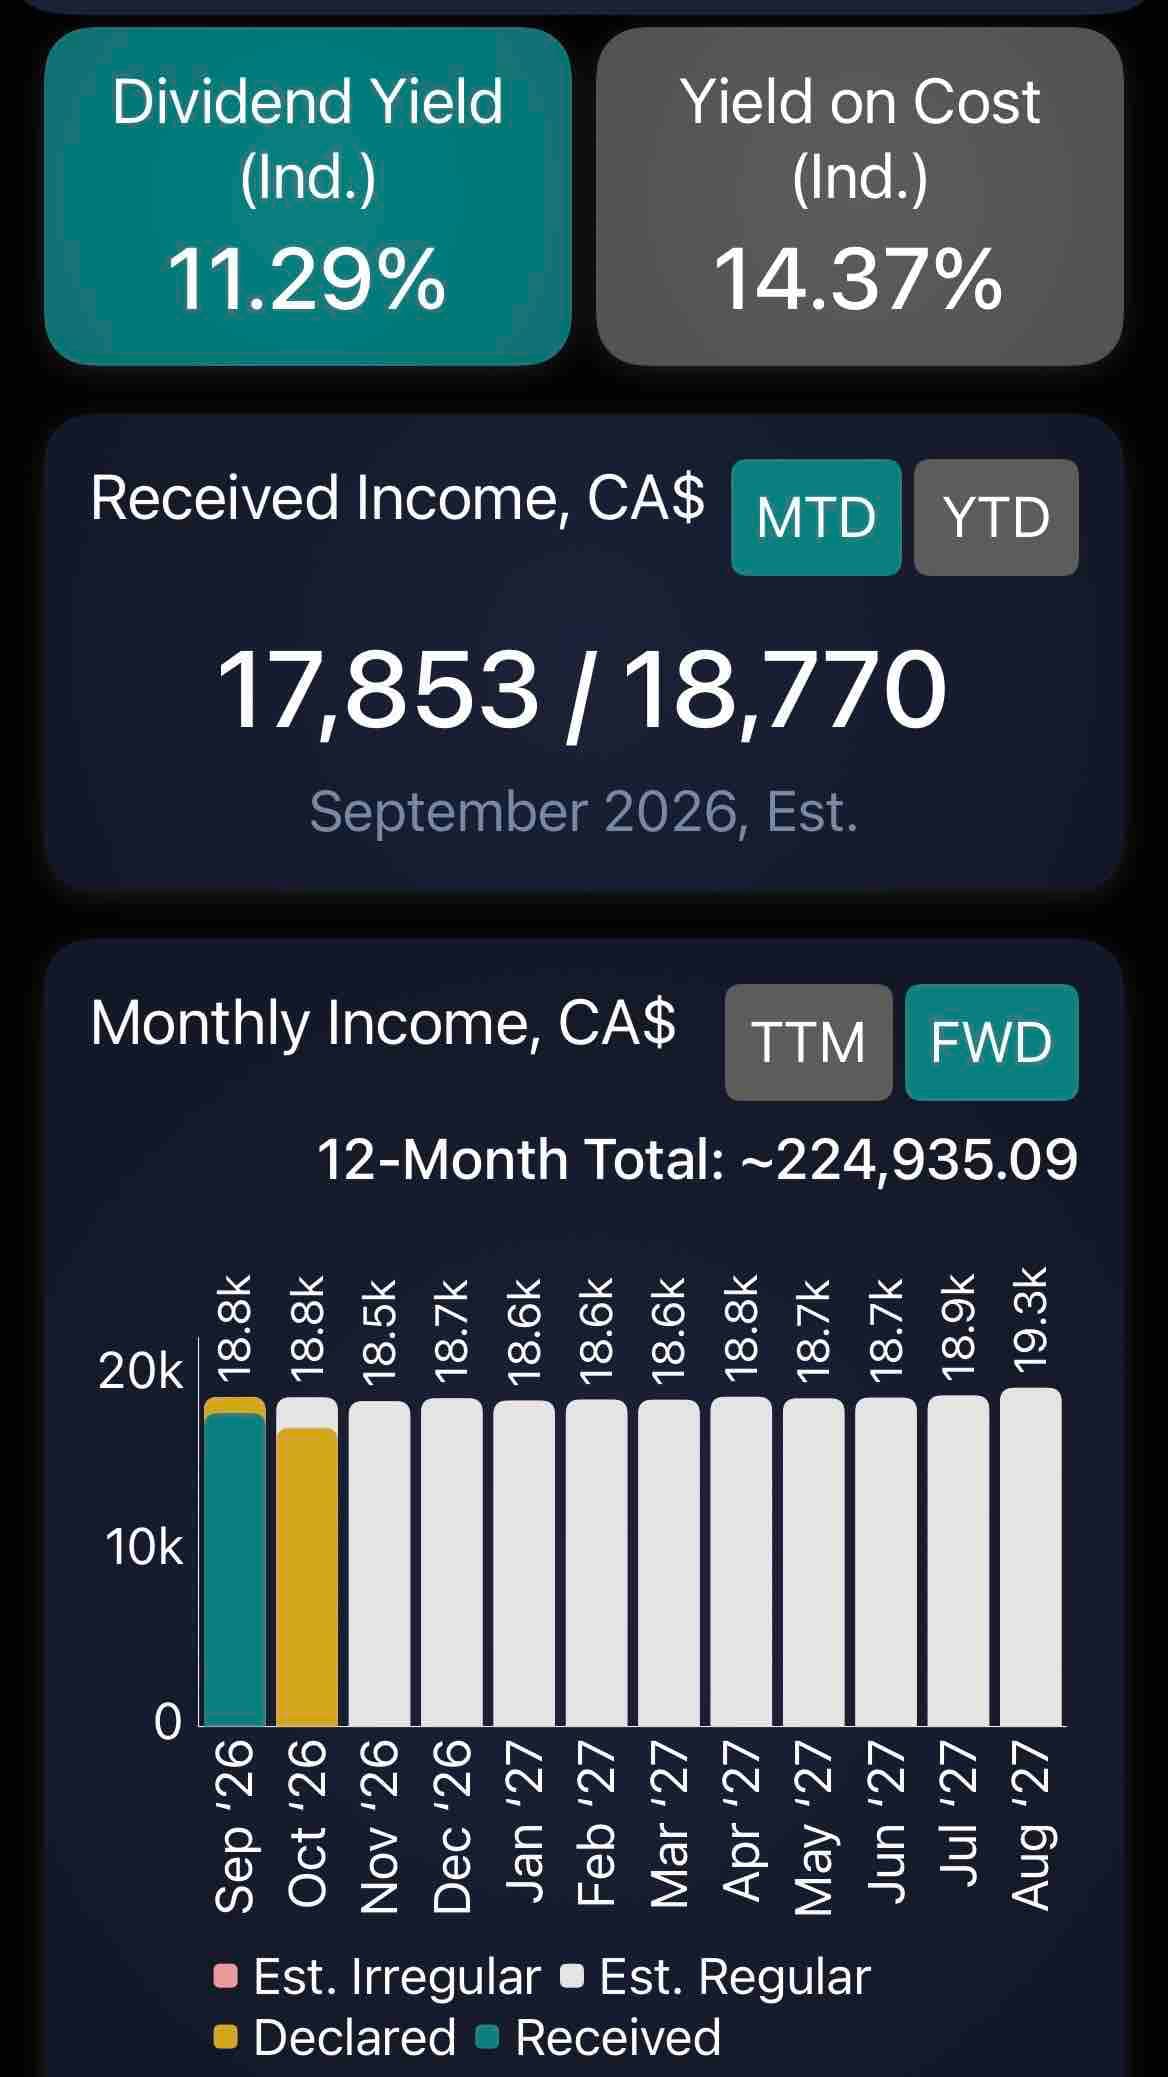
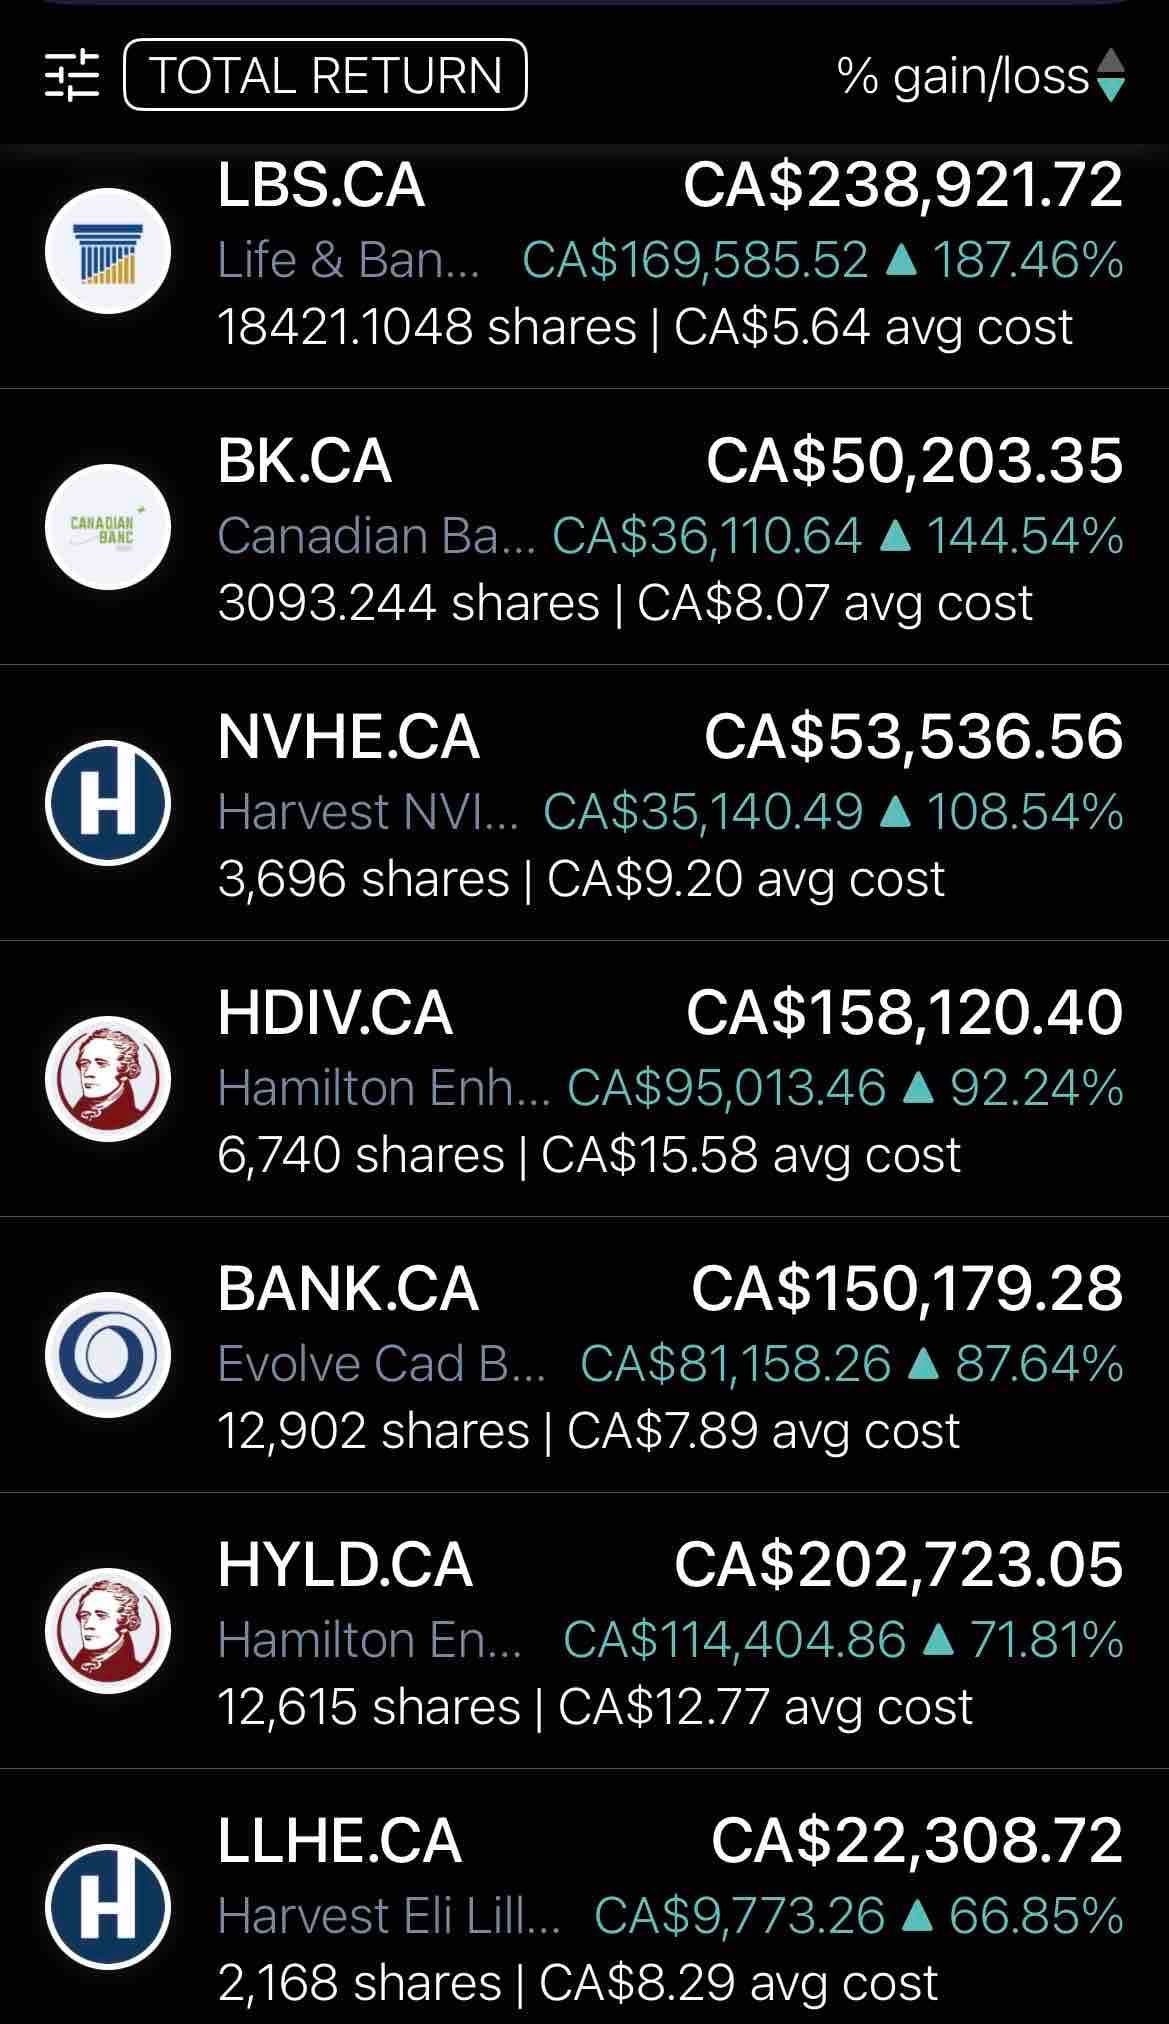
Sept Income: $18,768.55 YTD: $173,757.14 I ran some numbers this week and my portfolio is up over 21% or over $354,000 YTD 🚀 We are ever getting closer to 1M total return in 3 years and I’m sure I will post when this happens 🎉 I decided to let go of a small position in $COSY (COST) stock as it’s been spinning its wheels for far too long. I put the proceeds into my usual monthly purchases. I still own 3 single stocks in $LLHE$NVHE and $NVDA. I continue to optimize my portfolio each month. As I am in the critical stages of an RRSP (RRIF) meltdown I am pulling out a yearly income of 6 figures and will continue to do so to at least 65 yrs old. Posts: ATH/Milestone Over 150% total return in 2 yrs 260% TFSA total return since 2020 This year I have been purchasing assets with a lower dividend 2%-6% which has allowed my portfolio to catch even more of the market upside. I have now added $ZEQT-T to my portfolio and will continue to purchase each month as I get closer to finishing my current asset purchases. Buys: $HEQL $UTIL $ZWT $IDVO $ZEQT-T Sell: $COSY Please review screen shots below for greater detail. Stay engaged and stay invested 💹 Always do your own research 🧐 and analysis 📊read more
Allow your portfolio to grow into your ideal dividend yield by purchasing appreciating assets. Dont chase yield but let yield chase you! Appreciating assets receive dividend increases. This maybe repetitive but I have 4 screen shot examples with an average YOC of 15.26% Assets purchased between 18 months to 3 yrs. If you have to support your asset NAV by purchasing more, You hold the wrong asset. If your overall NAV is negative, re-asses your portfolio makeup and adjust accordingly. Always do your own research 🧐 and analysis 📊read more
A stock paying a 9% dividend doesn’t automatically mean you’re earning 9%. If the share price falls 15%, your investment could be losing value despite the dividends. Smart dividend investing means looking beyond yield and focus on: 1. Total Returns 3. Cash Flow, and 3. Dividend Sustainability. Comment YIELD & I’ll share my top 3 dividend paying stocks.read more
So this is my first full year of being retired and officially just hit my LIF Withdrawal Ceilings! One of the funny things about retirement is discovering that even when your investments are doing well, the government still has rules about how much of your own money you can take out. I’ve now officially maxed out my annual withdrawals from BOTH my provincial LIF and my federal LIF. That’s right. Two accounts. Two withdrawal limits. And apparently, two reminders that I’m not entirely in charge of my own retirement money. 😂 The idea behind a LIF is to make sure you don’t blow through your pension money too quickly. I understand the logic, but here’s the thing: I’m not trying to spend my portfolio into oblivion. I’m trying to make it work for me. My investments generate income, I take what I’m allowed to withdraw, and I reinvest what I don’t need. And that brings me to the interesting part. Next year, I’m expecting my withdrawal room to increase because the money I’ve left invested continues to work for me. The reinvested distributions, along with any investment growth, can increase the account balance used to calculate next year’s maximum withdrawal. For my BC provincial LIF, there’s another wrinkle: the previous year’s investment return can also affect the maximum withdrawal. Another great problem to have😁 The federal LIF uses a different calculation, based primarily on the account balance at the beginning of the year and the applicable age-based percentage. So, while I can’t simply add all this year’s profits to next year’s withdrawal allowance, a growing portfolio can certainly help increase the dollars I’m permitted to take out. Of course, the government gets to decide how much I’m allowed to withdraw from these two accounts each year. But it doesn’t get to decide how much I enjoy retirement. There are worse problems to have than wanting to withdraw more money because your investments have grown! Imagine being told you’ve saved too much, earned too much investment income, and now have to wait until next year to take more of it out! I’ll take that problem over running out of money any day. How many other retirees are bumping up against their LIF withdrawal limits while their portfolios keep growing?read more
Hated to sell 1,500 $CVE Cenovus Energy in my RIF today at $44.50 😞😬😬 but best I did 👍🏻 Why????? 1. Lock in some profit. In my RIF, I had bought & sold 2,700 CVE for a 22K gain Still holding 1,300 shares at an average cost of $31.51 🫣 2. Like Portfolio Manager Eric Nuttell of Nine. Point Energy Fund, I wanted to keep some dry powder in case we get a dip in the sector. This sale drops my Energy weighting to 52% & raises my Cash allocation to 11%. I will hopefully continue to book a bit of Energy gains if/when prices perk up a bit. 3. As a retiree, I thought it prudent to increase my Cash💰 Wedge to cover my scheduled 2027 RIF withdrawals. With the cash I now have on hand, I will not need to sell stock if we get a major draw down over the next 15 months 👍🏻 Although I hated to sell Cenovus, it’s a CMA (Cover My Ass) move 🤡🌎 If I was 56 instead of 66 years of age, it is highly unlikely I‘d sell this much of a Conviction Buy 😬But such is life. Emotions need to be SET ASIDE & laid out retirement plans followed. Anyone else forcing themselves to book gains or raise cash 💲 to be prudent? I just sense too many headwinds on the horizon 🫣 Energy makes all of Canada 🇨🇦 stronger & more independent 💥💥read more
At least, that’s what we’ve been told. Work for 30 or 40 years. Save as much as possible. Retire. Then slowly start eating into the portfolio until you eventually run out of money. But what if you retire… and your portfolio keeps getting bigger? We’re withdrawing money every month. We’re travelling. We’re enjoying life. We’ve done Europe twice and Mexico. We’ve helped the kids. And somehow… the portfolio keeps accumulating. I’m not selling off chunks of my portfolio just to create cash. I’m primarily living off the income it produces and allowing the rest to keep working. Which has completely changed how I think about retirement. Maybe the goal shouldn’t be: “How do I make my money last until I die?” Maybe the goal can be: “How do I build a portfolio that can fund my retirement without having to destroy the portfolio?” Obviously, markets don’t go up forever, and there will be bad years. But if your portfolio can generate enough income to cover your lifestyle while still participating in the growth of the market… you may end up with the strangest retirement problem of all: You retired… but your portfolio didn’t. 😂 And honestly, I’ll take that problem. What do you think? Is retirement really about de-accumulation? Or is it about making your money work hard enough that you don’t necessarily have to spend the capital?read more
Transparency: I am 27 and I got laid off my job of 4 years in July, got the money from my employer matched dcpp account created. I have emergency funds that can last till I get a job I have money invested in TFSA already and just 1 bucks each in my Fhsa and RRSP don’t need them for now. I need help on what I can invest in for long term run. I know the psa saying it’s not a financial advice. I make sure to run a research on what to invest in before I go on . I am not able to access the money and also not going to be needing it till I retire. Thanks everyone in advance for all your kind suggestions and I am going to tag some of my faves here too @bdinvesting@joyeeyang@aziamery@maxstocks@blossom@sophii.svg@katricejustice #newbie #stocks #retirement #future read more
The FIRE community treats the 4% rule like gospel: Multiply your annual spending by 25 and walk away. Want an $80k lifestyle? The rule says you need $2,000,000. For Canadians, that rigid formula can trap you at work for 5 extra years. 🚨 The $445,000 Blind Spot The standard 4% rule assumes your portfolio must fund 100% of your life forever. It completely ignores guaranteed income. Early retirees often brush off government pensions because age 65 feels too far away. That is a massive planning error. 🇨🇦 The Canadian Reality at Age 65 Between CPP and OAS, a retired couple can conservatively expect ~$39k/year in combined, inflation-indexed income. Even retiring at 45 with zero earnings for 20 years, maxing contributions in your 20s and 30s still secures a significant baseline. That changes the math completely: $80,000 desired lifestyle − $39,000 CPP & OAS = $41,000 net portfolio gap Apply the 4% rule to that remaining gap: $41,000 × 25 = $1,025,000 needed at age 65. Not $2,000,000. 🌉 The 20-Year Bridge (Retiring at 45) You do not need $2M on day one. Your portfolio only needs to do two things: * Fund $80,000/year for 20 years. * Arrive at age 65 with ~$1,025,000 left. At a conservative 4% real (after-inflation) return: You only need $1,555,000 at age 45. • Years 45 to 65: Portfolio draws down to cover the bridge. • Age 65 onward: CPP and OAS turn on, withdrawals drop to $41k, and the remaining $1.025M lasts indefinitely. ⏳ The Real Cost: Your Time $2,000,000 vs. $1,555,000 is a difference of $445,000. Grinding for that extra $445k often means 4 to 6 unnecessary years at a job you're ready to leave. The 4% rule is an easy benchmark for your 20s and 30s. A dynamic cash-flow plan gives you your freedom years sooner. When you get serious about pulling the trigger, run the actual numbers with a fee-only CFP to find your real finish line. 💬 Are you factoring CPP and OAS into your early retirement number, or planning to fund 100% solo?read more
I’ve spent a lot of time trying to educate myself since starting my investing journey at 50, and lately I’ve been hearing about a withdrawal strategy on podcasts, YouTube and from other investors. The idea is to withdraw money from your TFSA, wait until the following year and then sell investments in your non-registered account to fill that TFSA room back up. I’hear this frequently from investors using covered call ETFs as part of their retirement income strategy. I’m wondering. Is this actually the most tax efficient way to withdraw your money? Depending on your income and the capital gains in your non-registered account, couldn’t you end up paying more tax by doing this? And what about the tax-free growth you’re potentially missing while that money is out of your TFSA? I’m not saying the strategy is wrong. It might make perfect sense depending on your situation. I just wonder if people are actually running the numbers or simply assuming it’s more tax efficient because the initial TFSA withdrawal is tax-free. So for those using or planning to use this strategy, have you actually calculated the tax savings compared to withdrawing from your non-registered account first? Curious to hear what others think.read more
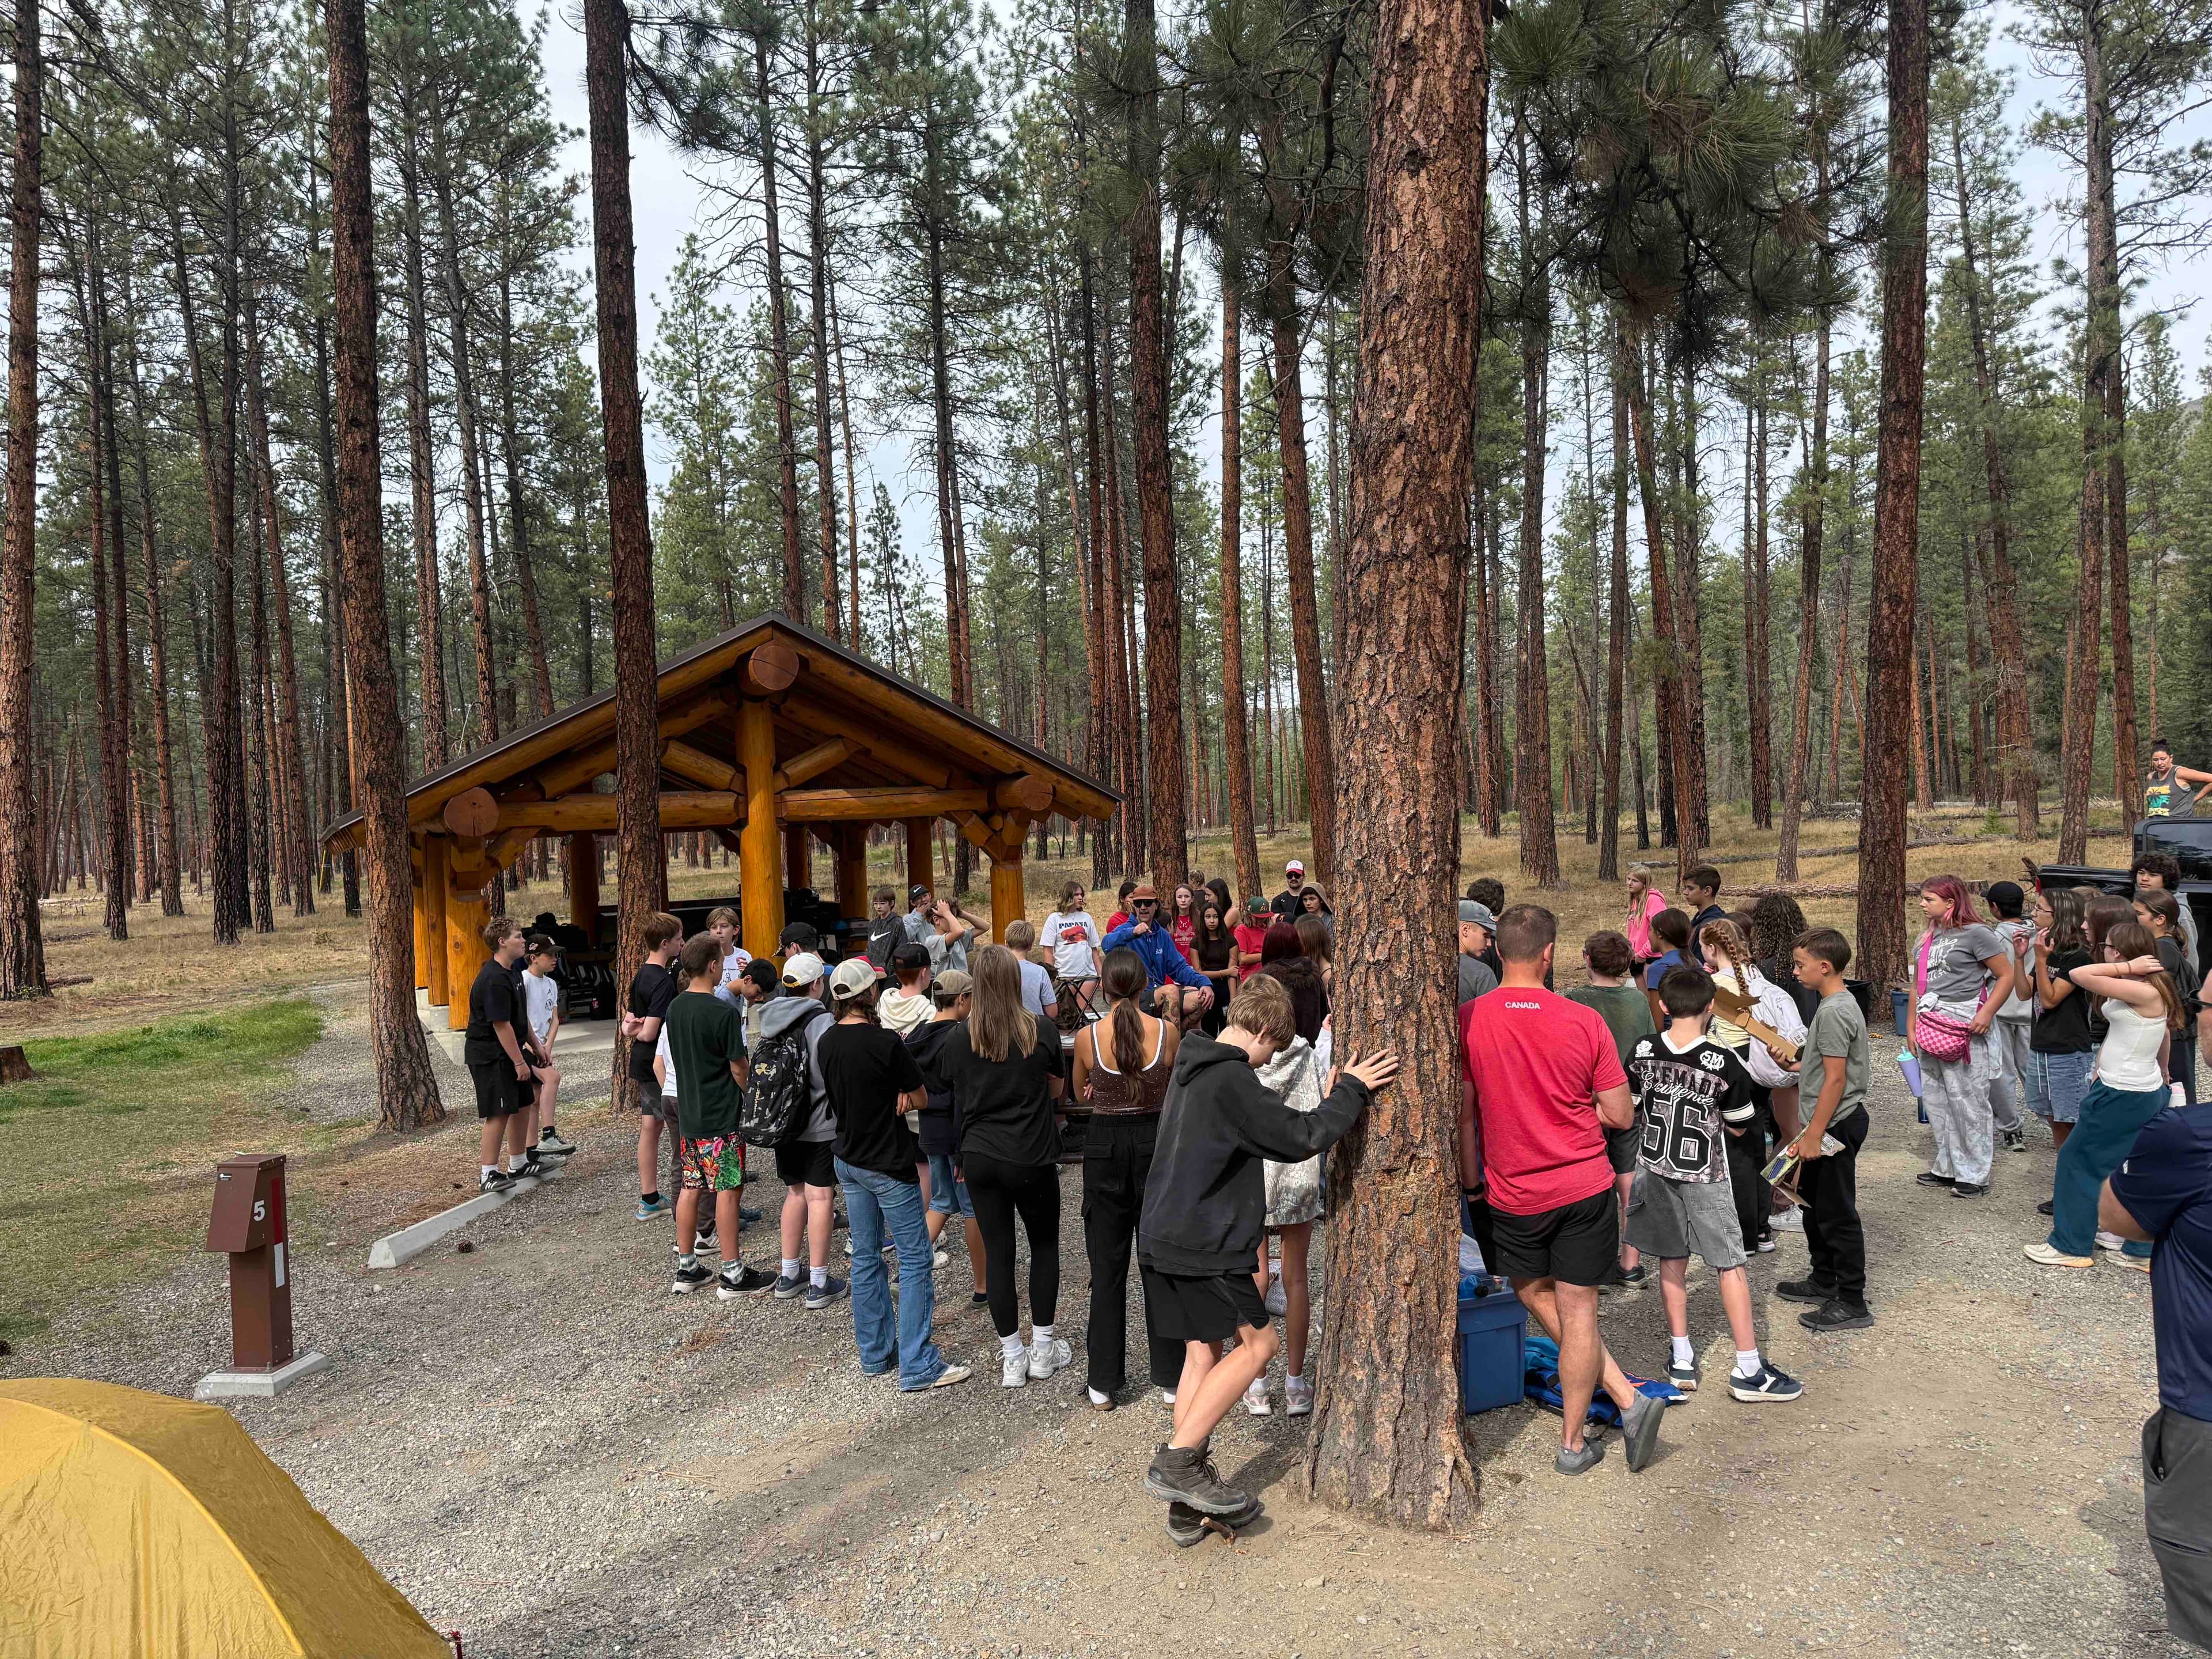
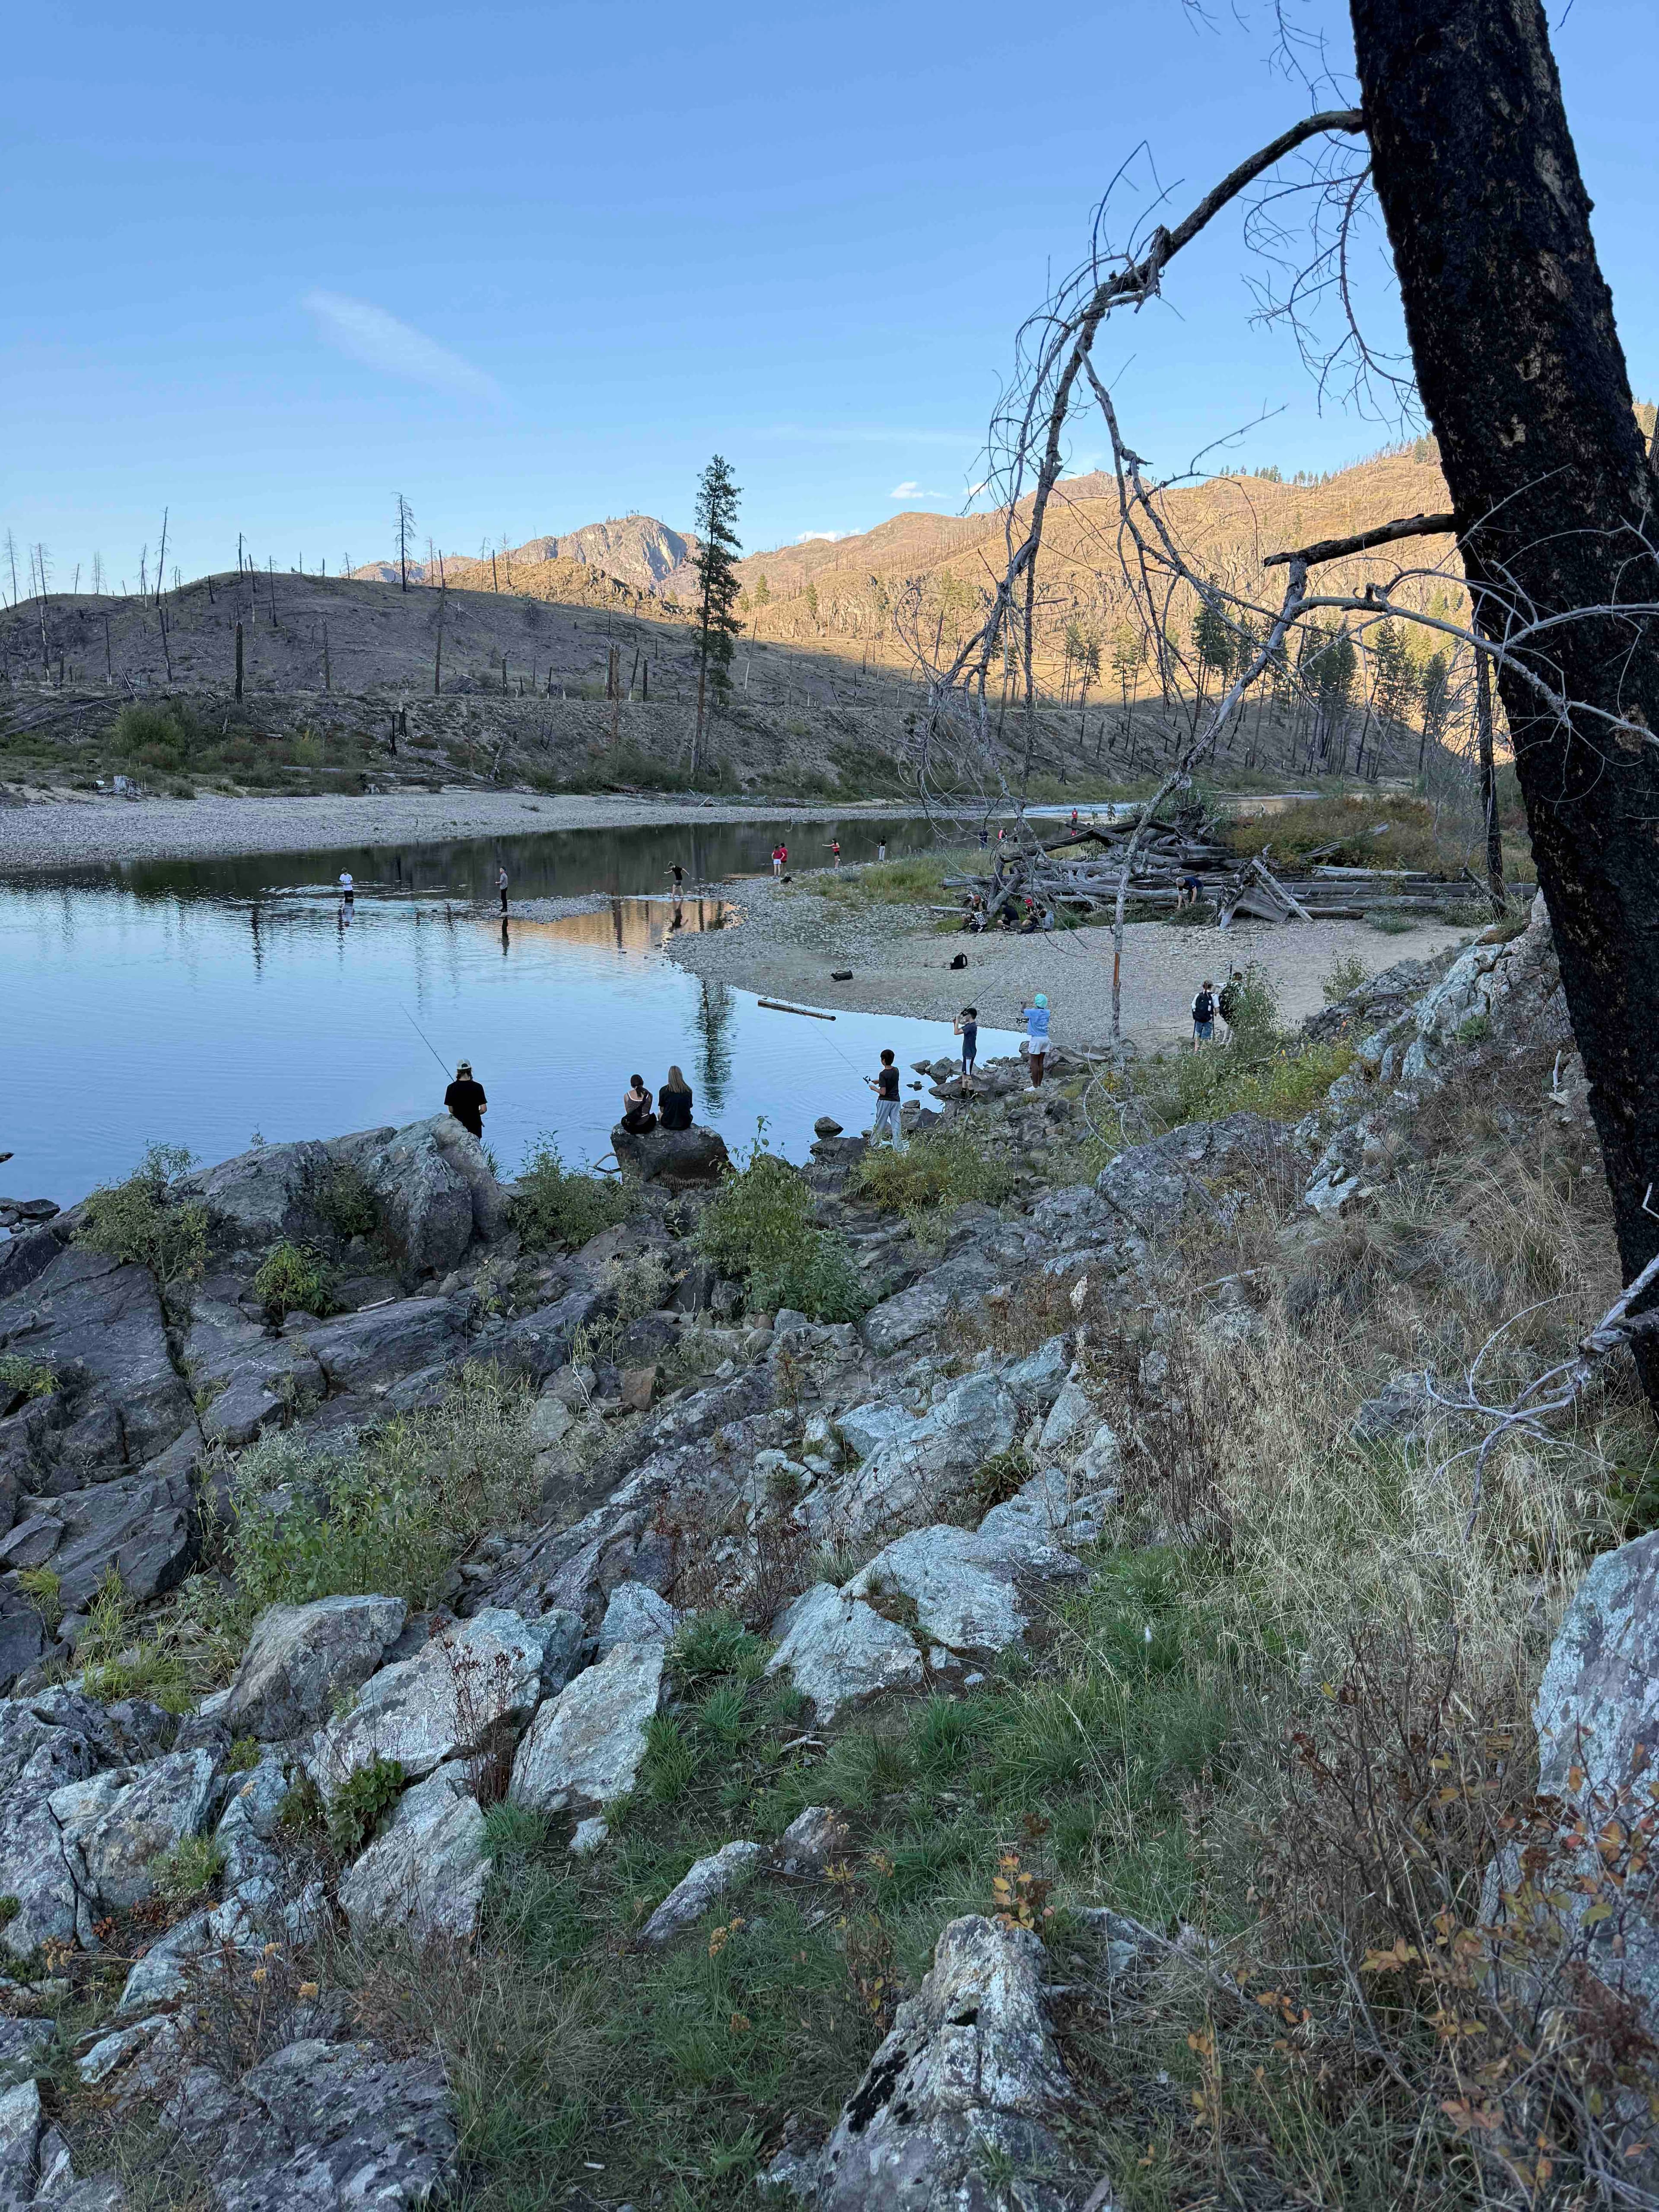
We spend years trying to figure out how to retire. But there’s something about retirement I’ve never really planned for, and lately I’ve started wondering if it might be just as important as the money. What happens when you remove work? Not the paycheque. We spend plenty of time figuring out how to replace that. What should we invest in? TFSA or RRSP? How much do we need? How do we become more tax efficient? How do we eventually draw down all these accounts? And for those pursuing FIRE, how early can we make it happen? I’m talking about everything else work gives us. I was listening to episode 69 of The Wealthy Barber Podcast and something in the conversation really made me think about this differently. Work can provide purpose, contribution and connection. I’d add value and challenge to that list. What replaces those things when work disappears? This becomes even more interesting when you think about how long retirement could actually last. Statistics Canada says Canadian life expectancy at birth was 82.16 years in 2024. Once Canadians reach 65, the average remaining life expectancy is another 19.43 years for males and 22.15 years for females based on 2022–2024 data. Now imagine someone retires at 50 and lives until 88. That’s 38 years. I’ve been in the workforce for roughly 33 years. In that example, I could actually spend more time retired than I spent working full-time. That’s a lot of life to simply say, “I’ll figure out what I’m going to do when I get there.” Then I found something else that made me think about this even more. Statistics Canada studied social participation and mortality among Canadians aged 65 and older. They followed people for roughly 8 to 9 years and found that those with low social participation had a higher risk of death during the follow-up period, even after accounting for a number of health, behavioural and demographic factors. That doesn’t mean retirement causes an early death, and it certainly doesn’t mean being bored will kill you. But Statistics Canada also points to retirement and the loss of roles that can accompany it as circumstances that can contribute to social isolation. Maybe planning for retirement isn’t only about replacing your paycheque. Maybe we should also be thinking about how we’re going to replace some of the things work has been giving us for decades: Purpose. Contribution. Value. Connection. Challenge. I’ve actually had a couple of small examples of this recently. I didn’t get home from work until around 1 a.m. last night and I really didn’t feel like doing much when I got up this morning. But I took the dog for a walk and did a short workout anyway. Nothing spectacular, but it was enough of a challenge to get my brain moving and motivated for the day. Now I’m heading into my days off and I volunteered to go on my daughter’s three-day, two-night outdoor camping trip because they needed parent volunteers. I’ll get to spend that time with my daughter, but I’ll also get to connect with kids from her school, her teacher and some of the other parent volunteers. I hadn’t really thought about it this way when I volunteered, but that’s connection, contribution and challenge outside of work. And I think I’ve been building some of this in other ways without really intending to. Creating content challenges me. Investing constantly gives me something new to learn. Blossom has introduced me to people I never would have met otherwise. Some are my age, some are younger and many see investing completely differently than I do. Going to BlossomCon in Vancouver really brought that home. Meeting Moe at the airport, sitting down with Mr. Financial, Will and Jess at breakfast, and then meeting so many other people at the conference made those online connections real. Maybe I’ve accidentally started building part of my retirement life before I’ve actually retired. Because imagine having complete freedom over every day. No alarm because you have to go to work. No deadlines unless you create them. No workplace where you’re automatically surrounded by other people. Nobody necessarily needs you to show up. At first that sounds pretty amazing. But what challenges you? Where does your sense of purpose come from? Where do you contribute something of value? Where do your connections come from? We spend decades building the portfolio that will eventually allow us to stop working. Maybe we should spend some of that time building the life we’re going to retire to. So forget about your portfolio for a minute. If your job disappeared tomorrow, what would replace the purpose, contribution, value, connection and challenge it currently gives you? And maybe the bigger question is: are you building any of that now? https://open.spotify.com/episode/1FC6RRIieZwodJUSF8hJi8?si=YqPHhyuqQ42nvsbMe2InQw&utm_source=copy-linkread more
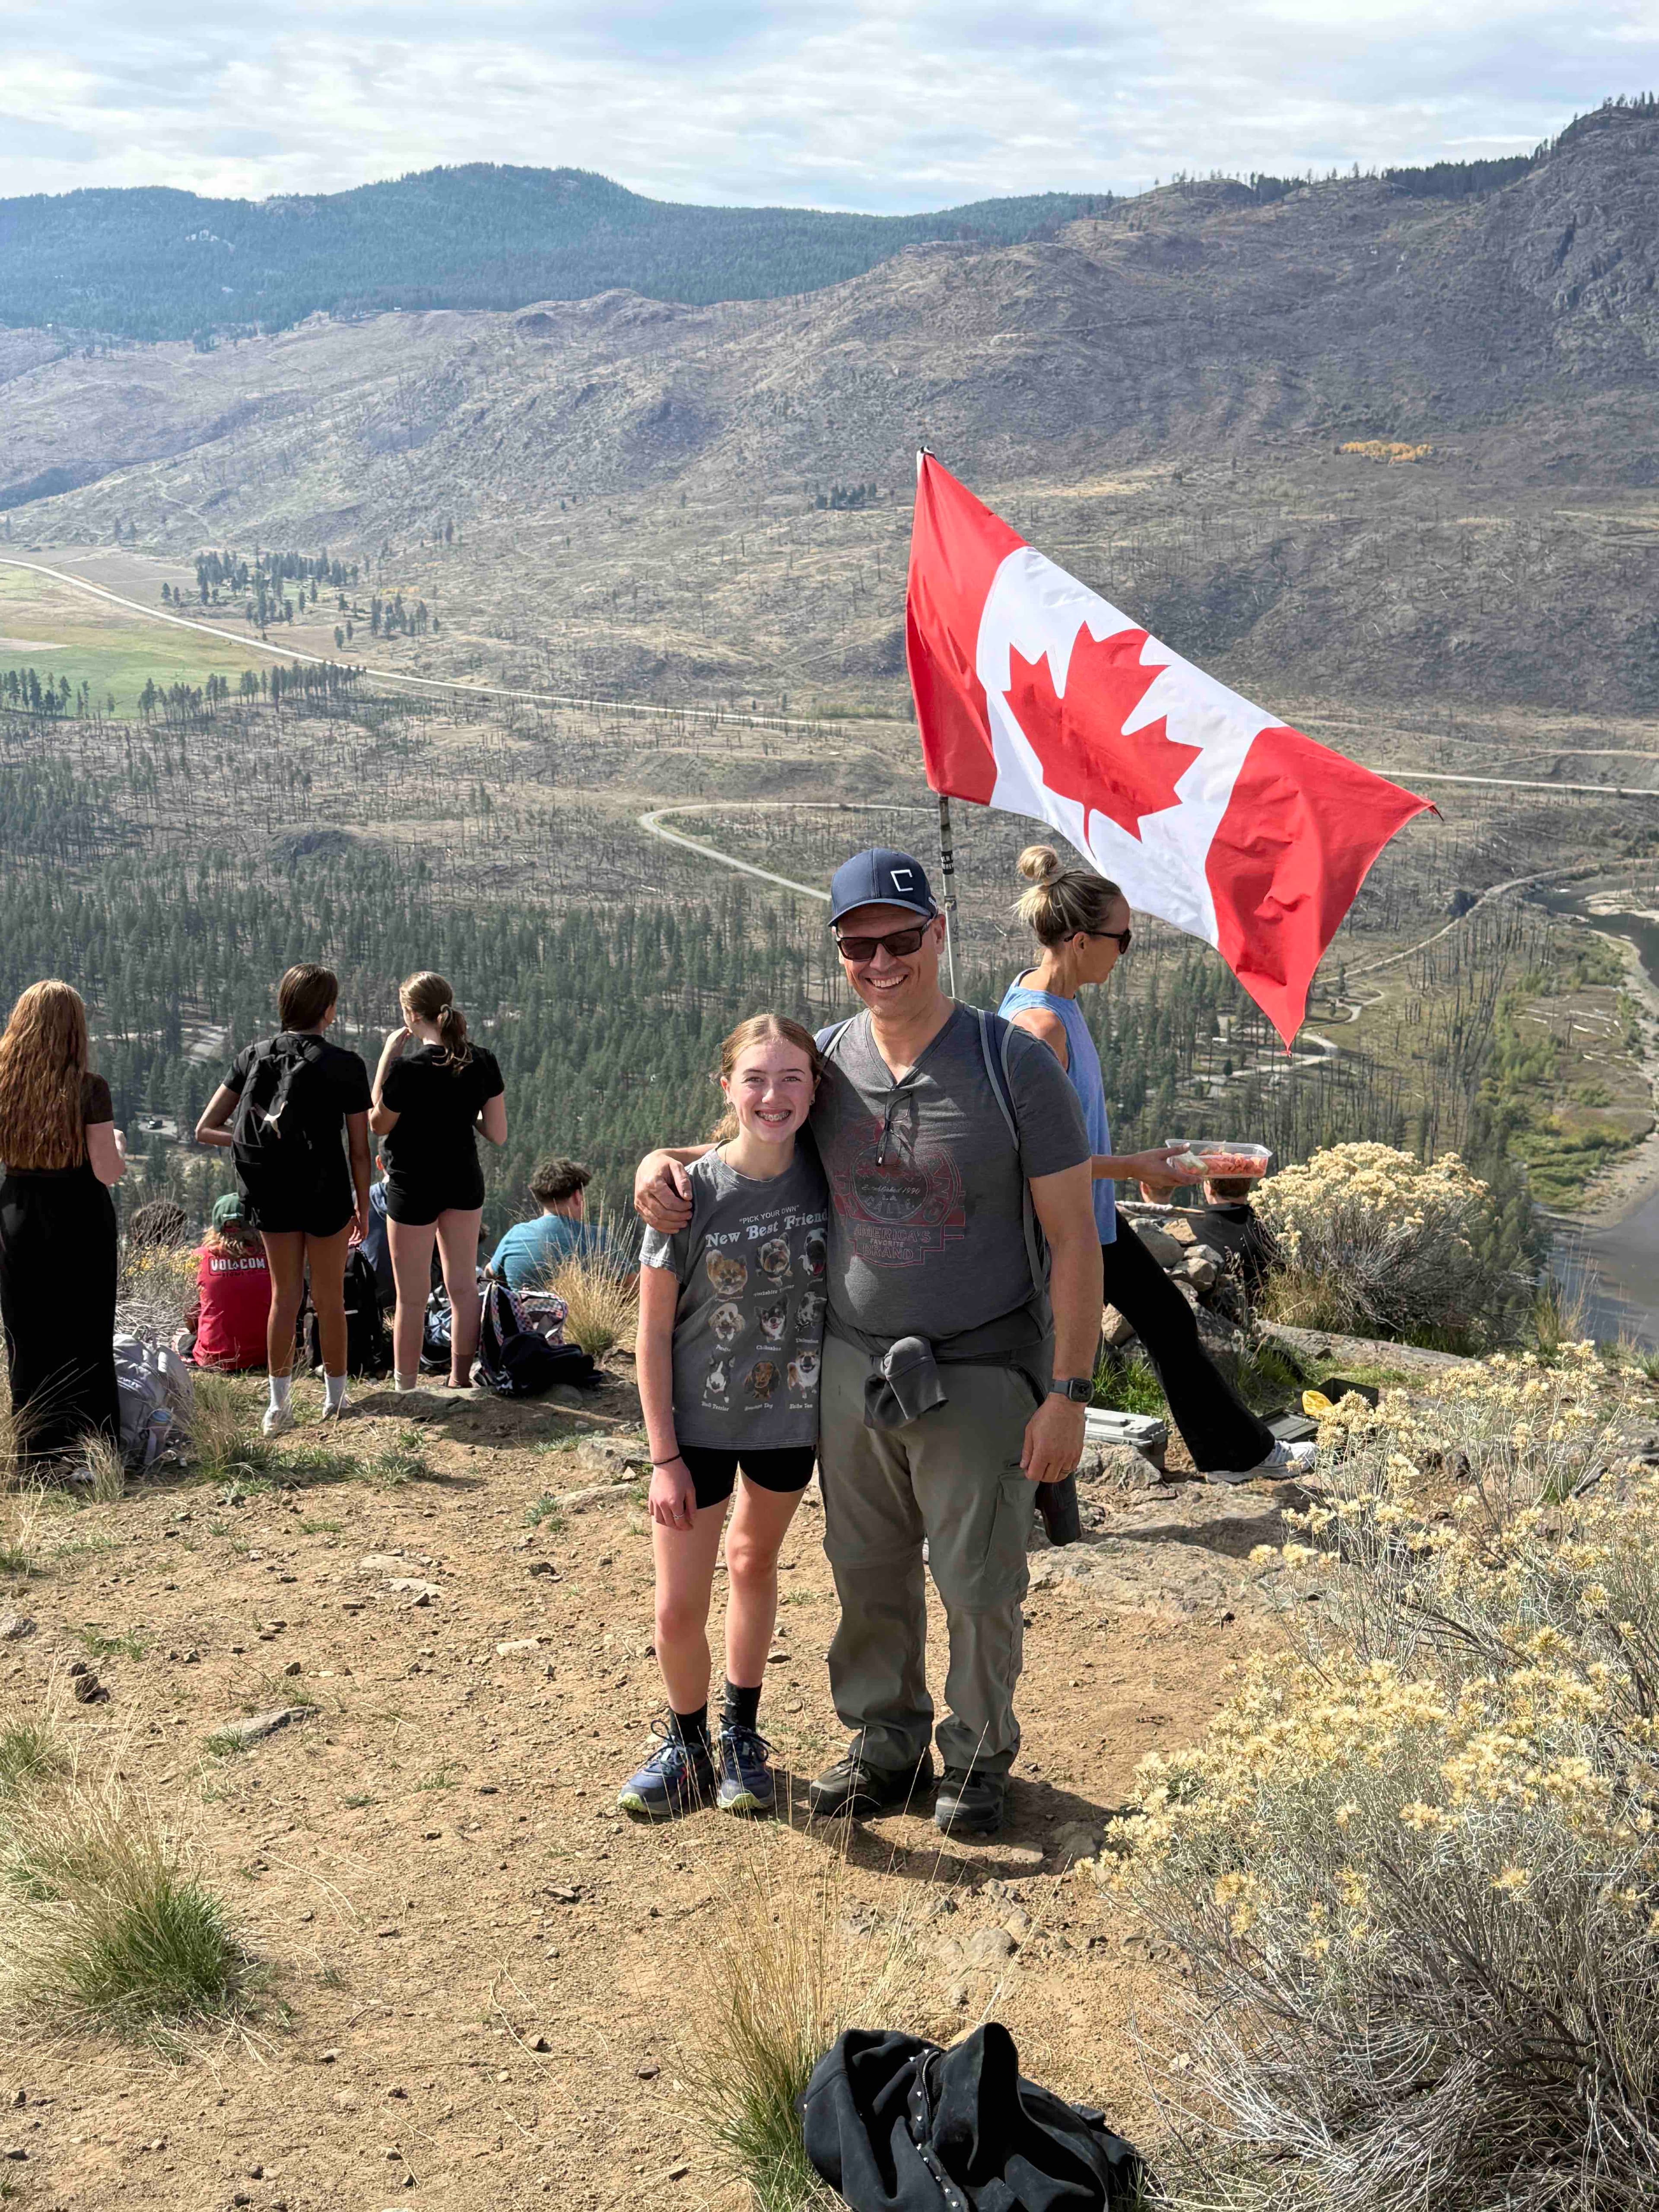
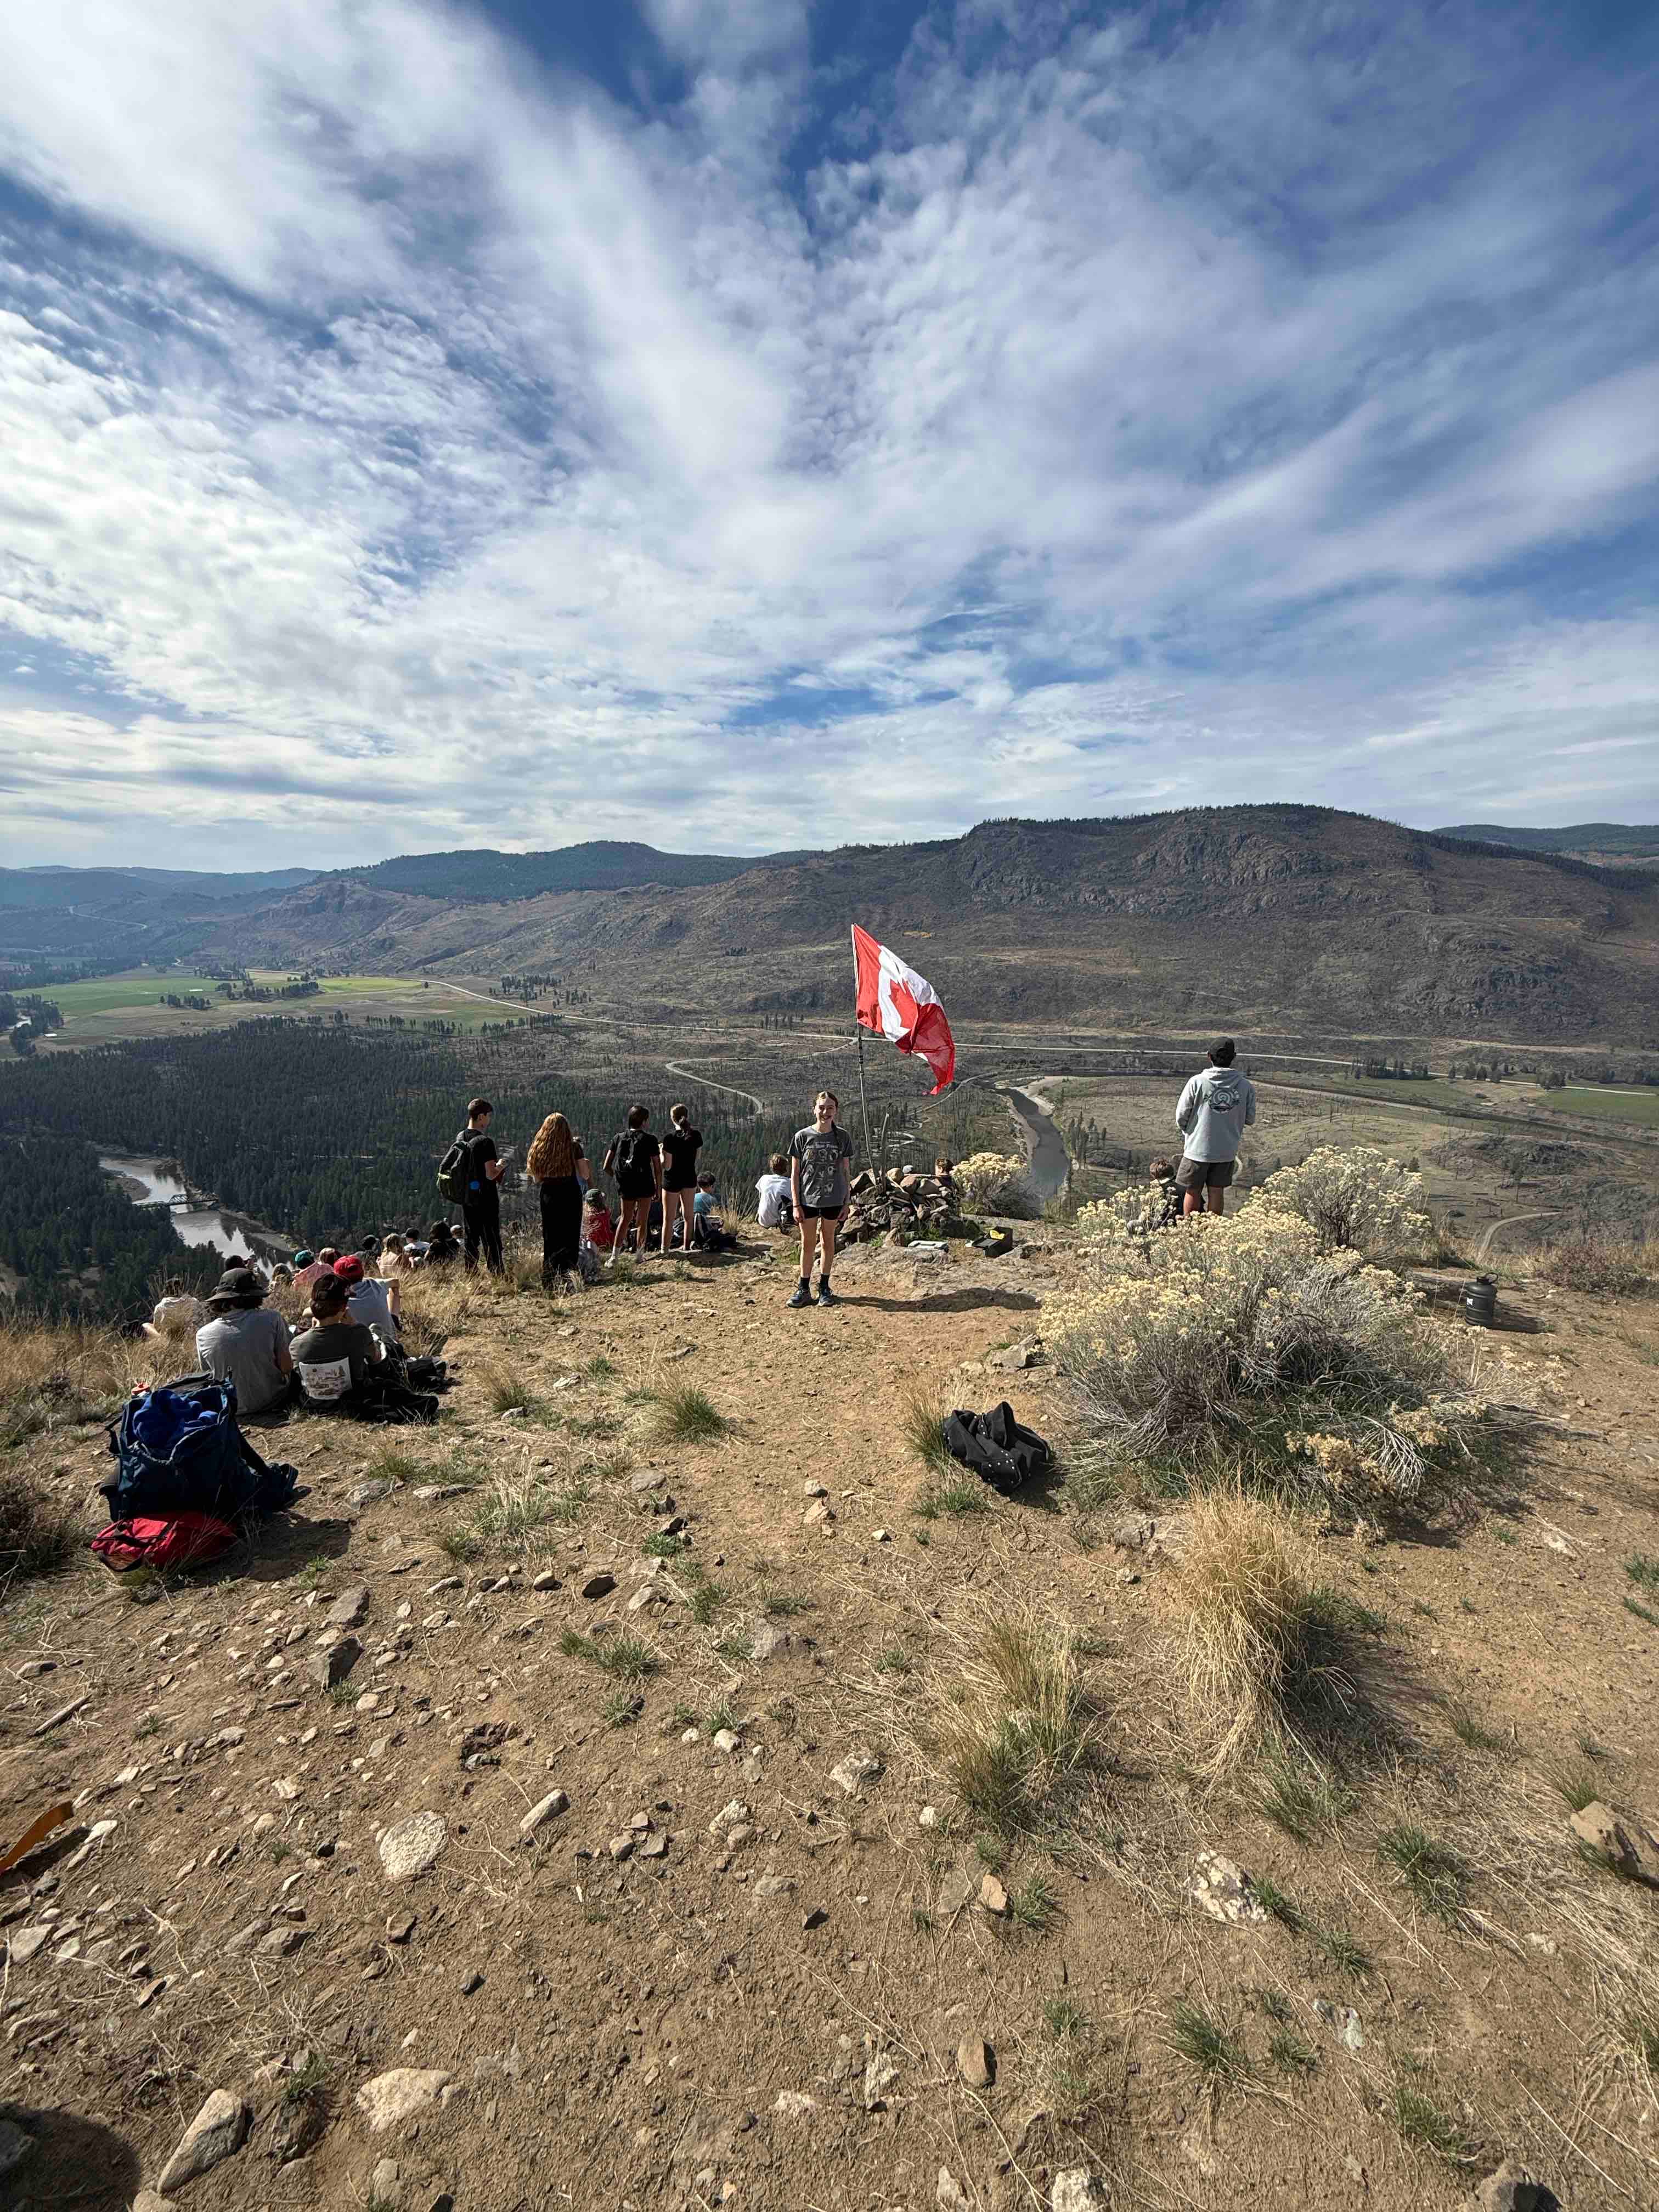
We’re all on Blossom because we want to learn and share all things investing. But over the last year, I’ve learned that investing is about far more than I originally thought. We spend a lot of time talking about numbers, ETFs, covered calls, dividends and total returns, but those are really just the tools. Today I invested in my family. I volunteered to go on my daughter’s outdoor ed trip with about 80 kids. We climbed a mountain, stood at the top and took in the valley below. And standing there with her was a pretty good reminder of why I’m doing all of this. I’m not investing just to watch a number on a screen get bigger. I’m investing so I can have more control over my time and more choices about what I do with it. Today, that meant being able to step away from everyday life and spend the day climbing a mountain with my daughter. We talk so much about what investing might give us 10, 20 or 30 years from now, but maybe it’s worth thinking about what it allows us to do along the way too. For me, investing is ultimately about time and choices. Has investing changed any of the choices you’re able to make in your life today?read more
@etf.go suggested that we should cover more ideas around the timing of moving an RRSP into a RRIF. He's definitely right, because this isn't a topic most of us hear about on Blossom very often. He asked how early you can convert, whether you can convert just part of it, whether you can still contribute to an RRSP afterward, and what else we should be aware of. You can convert an RRSP to a RRIF at any age. The age 71 rule is the deadline for dealing with your RRSP, not the earliest age you can make the move. If the money goes directly from your RRSP to your RRIF, the transfer itself isn't taxable. You pay tax as you withdraw it. You can do a partial conversion, too. If you had $300,000 in an RRSP, you could move $30,000 into a RRIF and leave the rest in the RRSP. And yes, you can still contribute to an RRSP after opening a RRIF, as long as you have contribution room and make the contributions by the end of the year you turn 71. You can't make regular new contributions to the RRIF. So why would you convert before 71? You might be retired and ready to start drawing income. Once you turn 65, RRIF withdrawals can also qualify for the pension income tax credit and may qualify for pension income splitting with a spouse. You can withdraw directly from an RRSP as well, so those age 65 rules are worth considering when you decide whether to convert some of it. The cost of starting early is that required annual withdrawals begin the year after you open the RRIF. You can always take out more than the minimum, but there is a percentage you have to withdraw each year, and that percentage generally increases as you get older. Every withdrawal is taxable income, whether you needed the money that year or not. To me, looking at your income across several years is the best way to make the decision. It doesn't work very well to look at one year in isolation when your income might change quite a bit between your last year of work, the start of CPP and OAS, and the years when RRIF withdrawals are required. For someone who retires before taking CPP and OAS, the years in between can be a good time to start melting down an RRSP. That just means withdrawing some money each year while their income may be lower. They may be able to pull money out fairly tax efficiently during those years, instead of leaving it all until RRIF withdrawals are added on top of CPP and OAS. Whether that works depends on their other income, so I'd want to run the numbers across those years before deciding how much to take. One other decision comes up when you open the RRIF: you can base its minimum withdrawals on your spouse's age instead of your own. You have to choose that on the original application. I covered it in my last post, but it's easy to miss when you're focused on the question of when to convert. If you've made the move, did you convert everything at once or start with part of your RRSP?read more
One of the best parts of being retired off of passive income it the opportunity to pursue hobbies that may have been out of reach due to finances, time, or work obligations. Today I've got the truck packed and the car in tow, headed to Watkins Glen International Speedway to race this weekend. I was in the car business my whole life, but rarely had the chance to enjoy my passion in this way. What hobbies have you taken up since retirement? Or, if you havent retired yet (emphasis on the YET, let's get there!) what types of hobbies have you struggled to dedicate time to, that you'll finally be able to pursue?
Sharing... https://www.youtube.com/watch?v=-rHmy5dPzfo This video calls out 10 things retirees with they knew... 1. I traded too much of my life for money 2. I didn't learn how to withdraw my money 3. I relied too much on CPP and OAS, and it wasn't enough 4. I gave too much money to my kids before securing myself 5. I waited too long to downsize 6. I didn't spend enough on my health 7. I didn't simplify my finances soon enough 8. I didn't plan for the cost of living alone 9. I underestimated inflation 10. I didn’t plan my retirement abroad properly, and it cost meread more
Have you ever thought, "boy, I wish I could pay my taxes earlier than necessary!"? It may sound crazy, but there can be good reasons for a retiree to withdraw more than they're required to from a RRIF. In my column this week, I go into some reasons why you might want to do that – and consider some other options for seniors with no beneficiaries. As always, questions and comments are welcome to agalbraith@globeandmail.com Gift link below (first 30 clicks free): https://www.theglobeandmail.com/gift/abf033097f2aee7cc380b493716e784abcd3170694bf0ae4c6f2ccb5a67962f4/GSA3HYHEGJGSTDAMSPZDCG5LGYread more