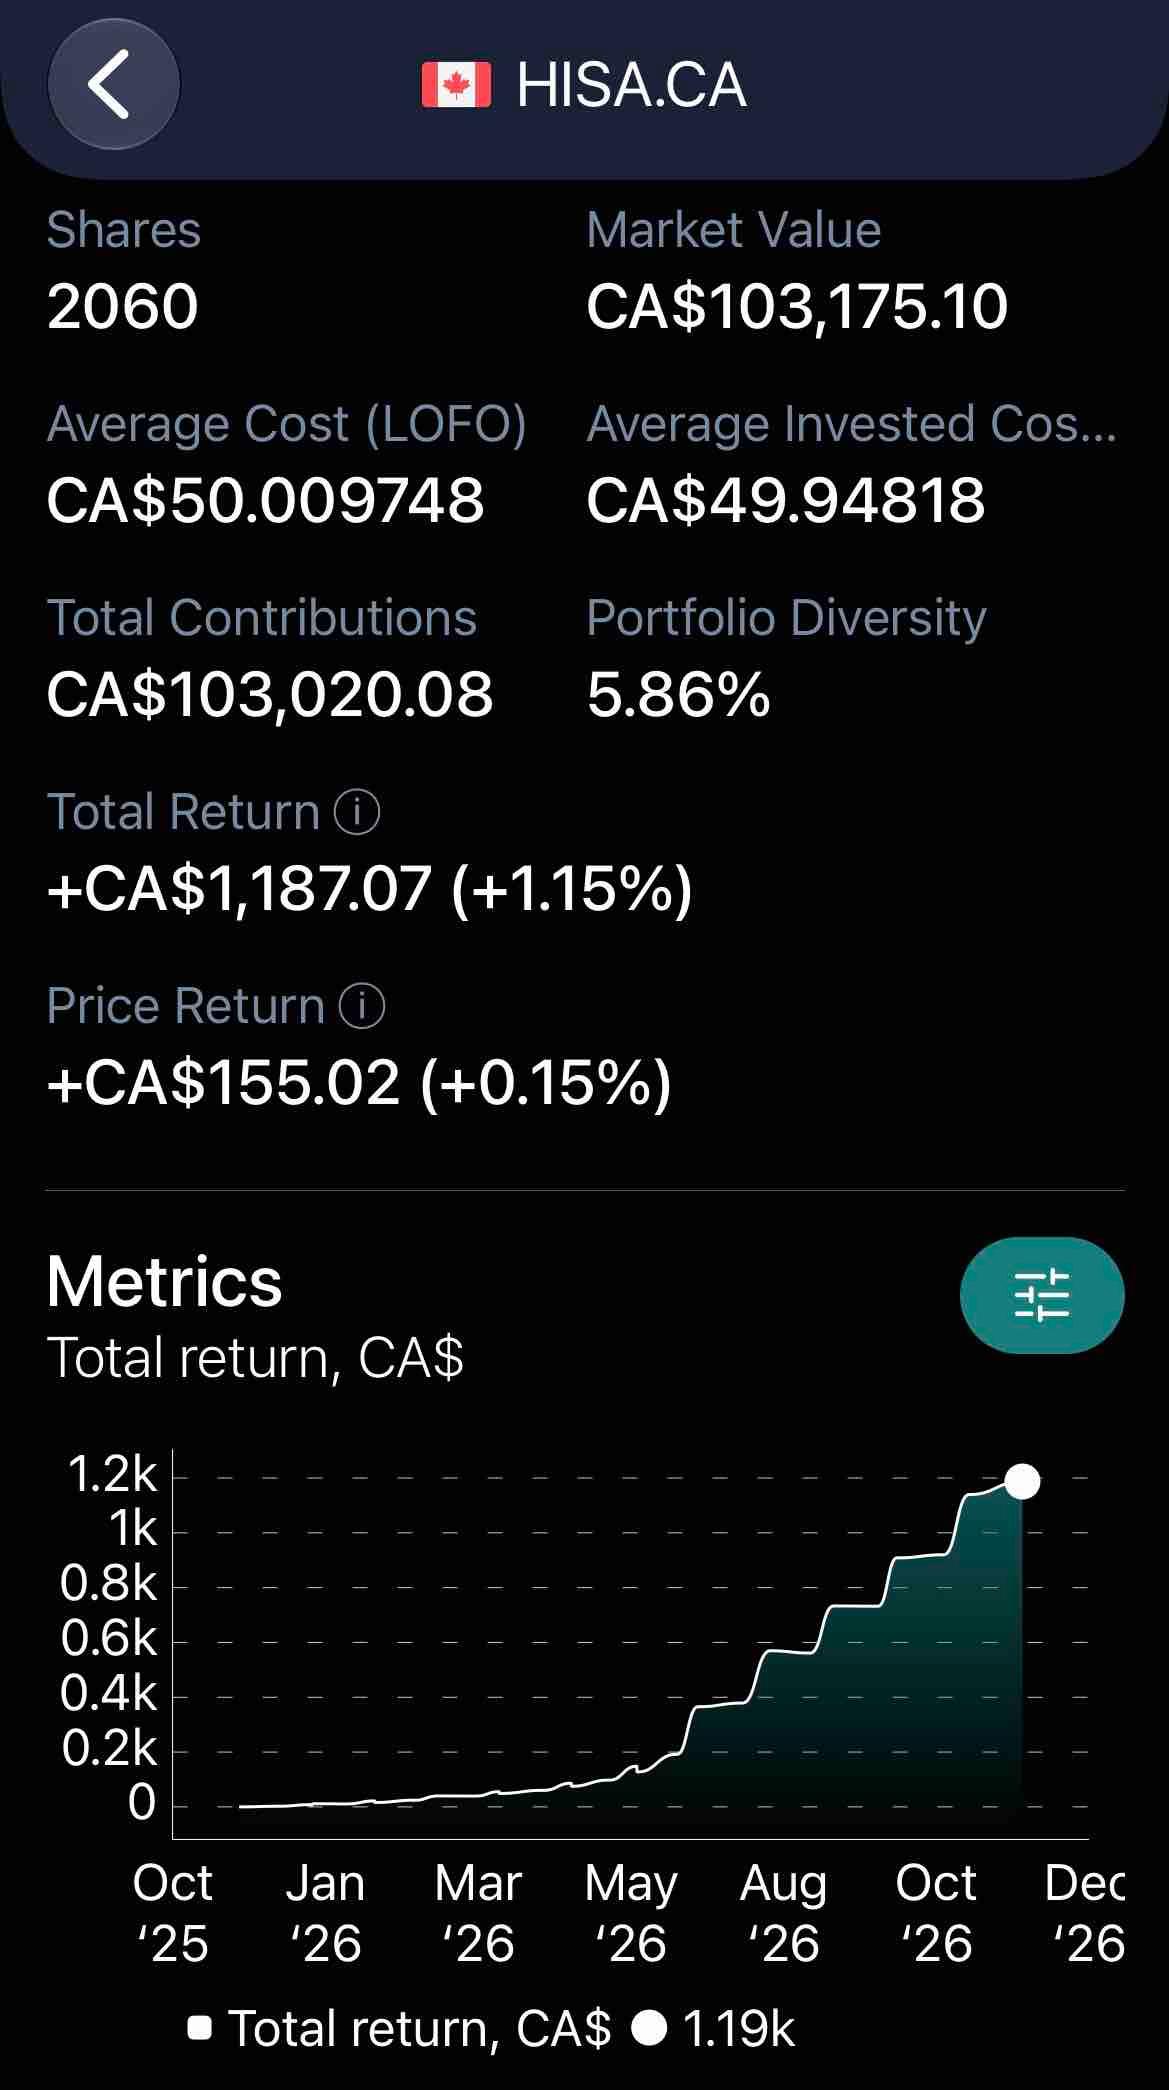
I have seen more than one post this month stating that “cash is trash” as inflation eats away at your returns. This is true over the long term but I’m holding my $HISA position in the form of a “Cash wedge” during retirement. • Sequence of return risk If the market really crashes or enters a bear market, this may affect my income flow in the form of dividend cuts. I can use my cash wedge to backfill any shortfalls. • Allows for recovery time If we do not see any immediate market recovery, this allows my portfolio to recover without having to sell anything. • Piece of mind The market fluctuations and noise become less of a concern with no need to panic. My $HISA position should be viewed as an Insurance premium against market volatility. I have been an advocate for holding a cash wedge during retirement as many financial institutions advise the same 1-3 years! My portfolio has taken a beating this past month but all roads eventually lead to a full recovery over time. I may even look at deploying a little of that cash in the near future as long as my dividends hold true! My $HISA position can be seen bellow. Always do your own research 🧐 and analysis 📊
322 views
11 Comments
L G@junky12 · 2h
Cash is not trash now! 💰💰
Andrew T
@andt987 · 2h
HISA along with other Cash ETFs are all taxed fully as interest income instead of capital gains in a non-registered account. Better to hold $HSAV which doesn’t pay distributions and is taxed as capital gains when you sell as needed
Kyle T@kyletfreedom58 · 2h
I moved my "cash" wedge to $SPLT this fall... maybe a little prematurely... since it offers some security of preffered shares with a 6% yield. I suppose I should have kept another $50K in $NSAV?
Kyle Garrett
@kgcottawa · 43m
Very wise. I’ve seen a few too many people build a “cash wedge” using funds with >1 beta and hefty MERs. That somewhat defeats the purpose. I prefer actual cash or money market funds, like yourself.
See the full comment section 👀Sign up for the full Blossom experience!