Taking a price target from $80 -> $57 for an industry leader like $NFLX is a no joke downgrade! Downgrades like this intrigue me, as they're rare for quality companies & 'potentially' create opportunities. Sounds like analyst's primary concerns are 'softening user engagement & content slate risks'. Full disclosure: Bullet points below taken from Gemini's overview on the downgrade. - Weakening Overall Engagement: Wells Fargo estimates average viewing fell to ~1.6 hours per subscriber per day in the first half of the year—down roughly 8% compared to adjusted 2023 levels. Overall viewing hours on Netflix dipped 8% year-over-year. - Declining Impact from Originals: Viewing hours for the top 100 original series fell 3% in H1 and are projected to drop 21% year-over-year in H2. Cahall argues Netflix suffers from a "hit problem"—expanding into reality TV, documentaries, live sports, and gaming without generating enough mega-hits. - Content Distribution Dilution: Broader distribution onto third-party platforms like YouTube expands reach but dilutes the exclusivity of blockbuster original programming. - Margin & Earnings Pressure: Second-half content investments and a shifting schedule are expected to weigh on profitability. Wells Fargo lowered its 2027 and 2028 EPS estimates to $3.77 and $4.52 (below consensus), projecting operating margins of 32.6% in 2027 and 34.2% in 2028. Where does this leave me? My fair value continues to be ~$70, so today's $71.xx definitely doesn't provide the margin of safety I'd need to start buying shares. Strangely enough, Wells Fargo's new price target fairly close to the margin of safety I'm looking for, assuming of course nothing changes between now & then (if it ever get there).read more
I’ve been trading options on wealthsimple in a non registered account (cad) and I’ve noticed that my profits in USD aren’t matching up with what the conversions are in CAD, for example today I made 103 usd which is around 144 cad, however it says I made about 113 cad. I know that there’s a 1.5% fx fee, but that’s absolutely egregious. I think it makes sense to get the USD account for $10/month right? Because it’s not making sense to me at the moment where the rest of the money is going… Like +40 USD is converting to 49 Cad, + 52 USD is converting to 62 Cad, I love wealthsimple but wtf is that BS
Sold 20 shares on the pullback, bought back 25 at a lower cost - increasing my position and pulling out $23.45 of a difference between the two transactions. Still extremely bullish and looking forward to earnings!
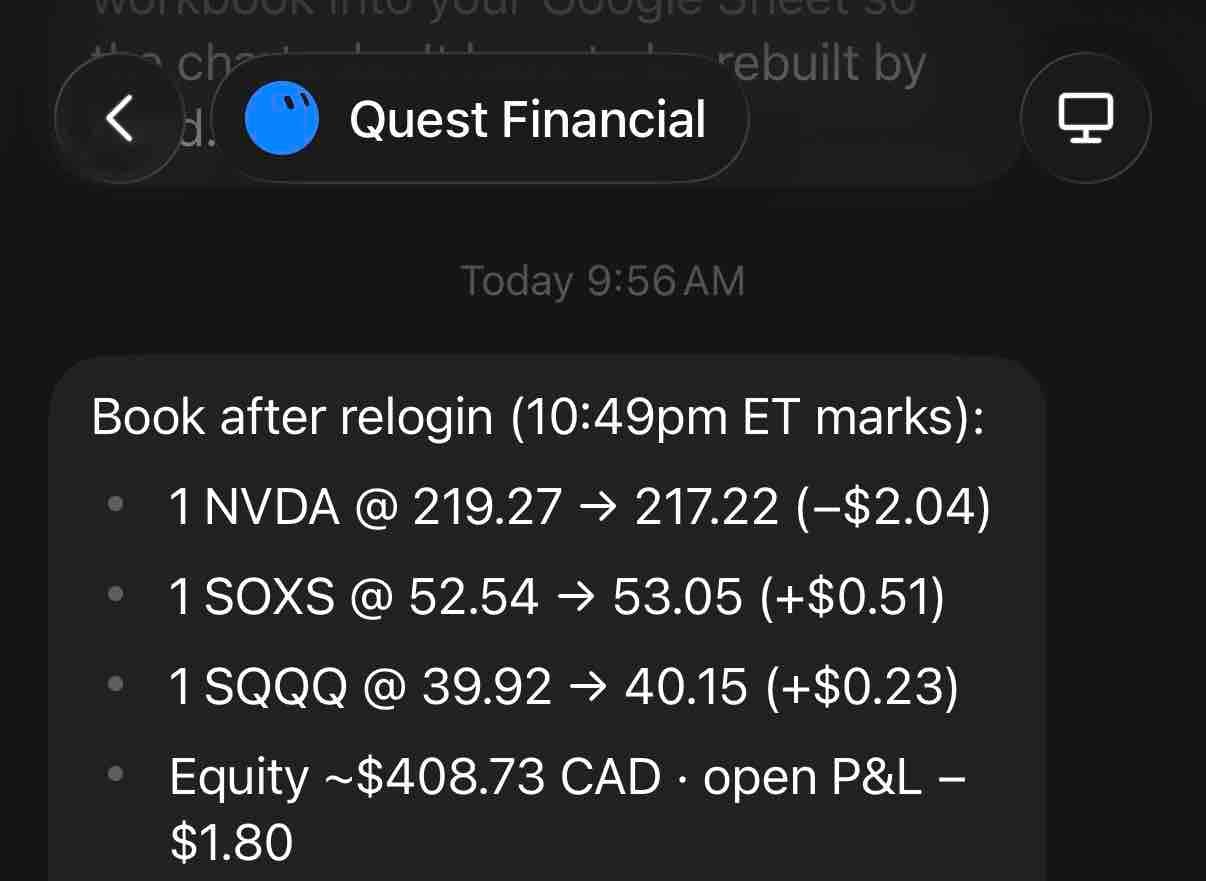
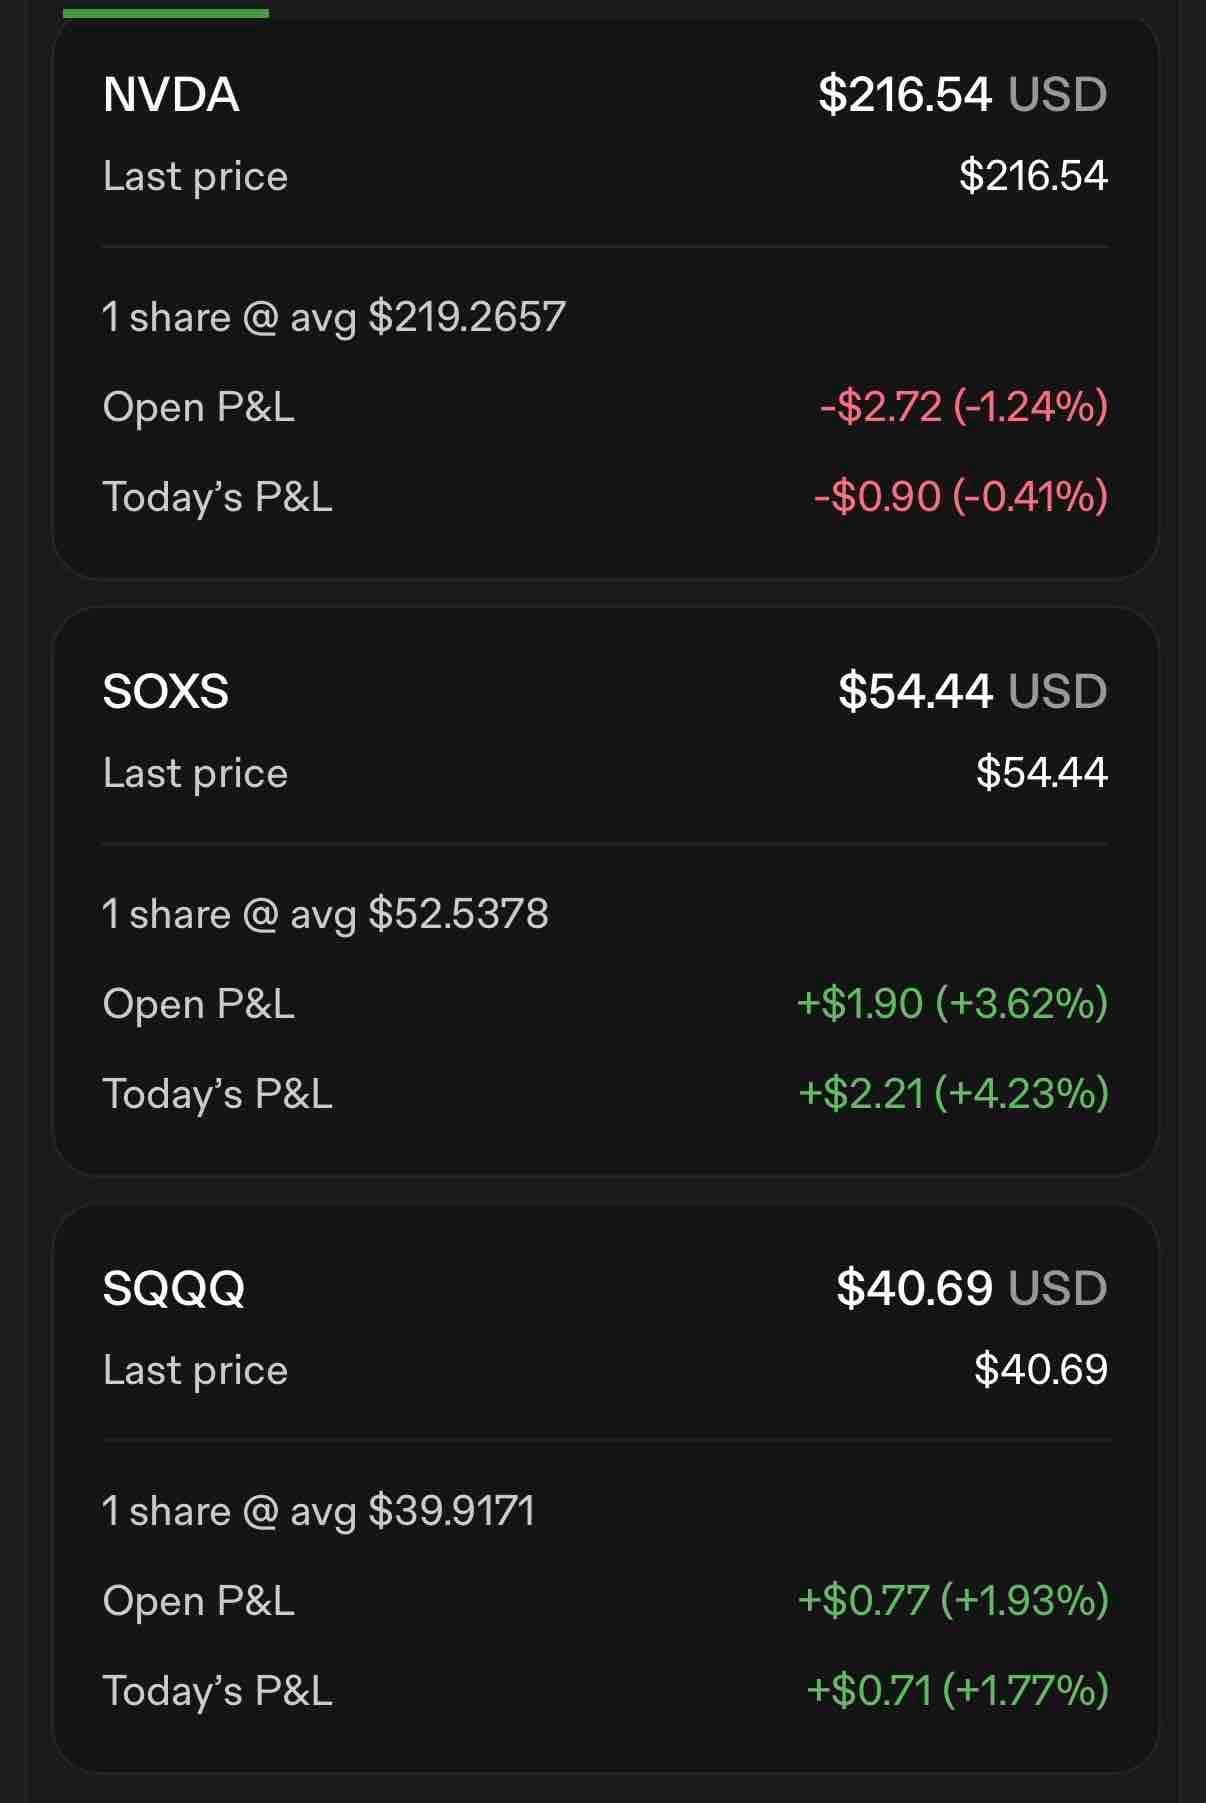
At a resort in Asia. Decided to let grok bot take over my old questrade account to test things out. It literally executed trades while I was sleeping. Space X AI is cooking something special here. Can’t wait to see what $TSLA integration will look like. $SPCX $NVDA $SOXS $SQQQread more
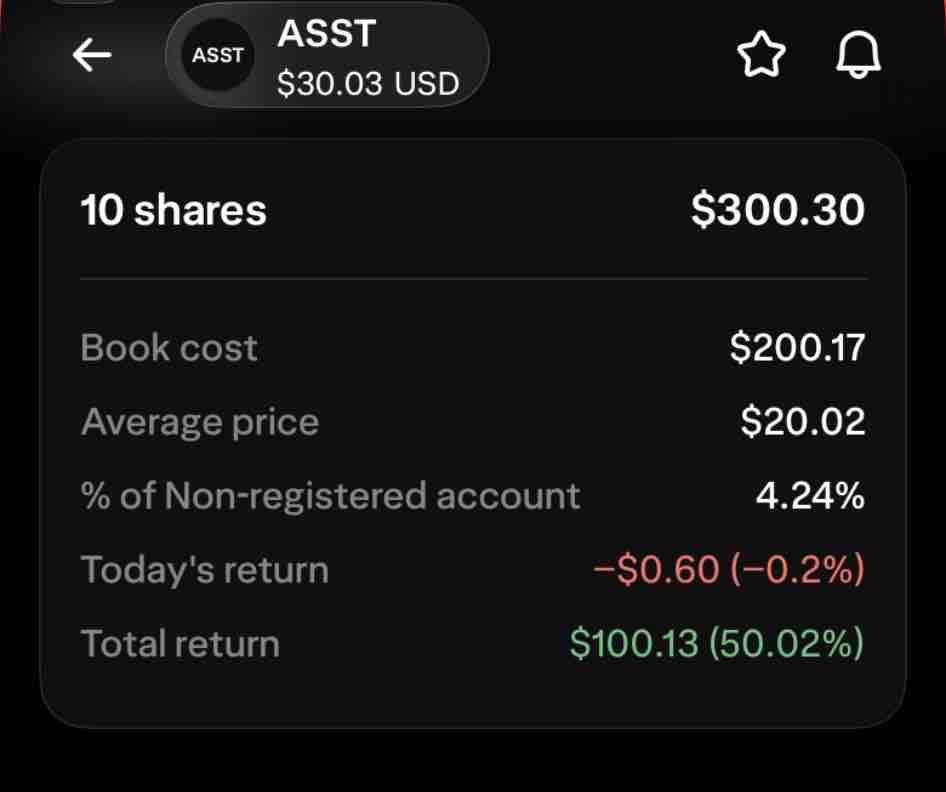
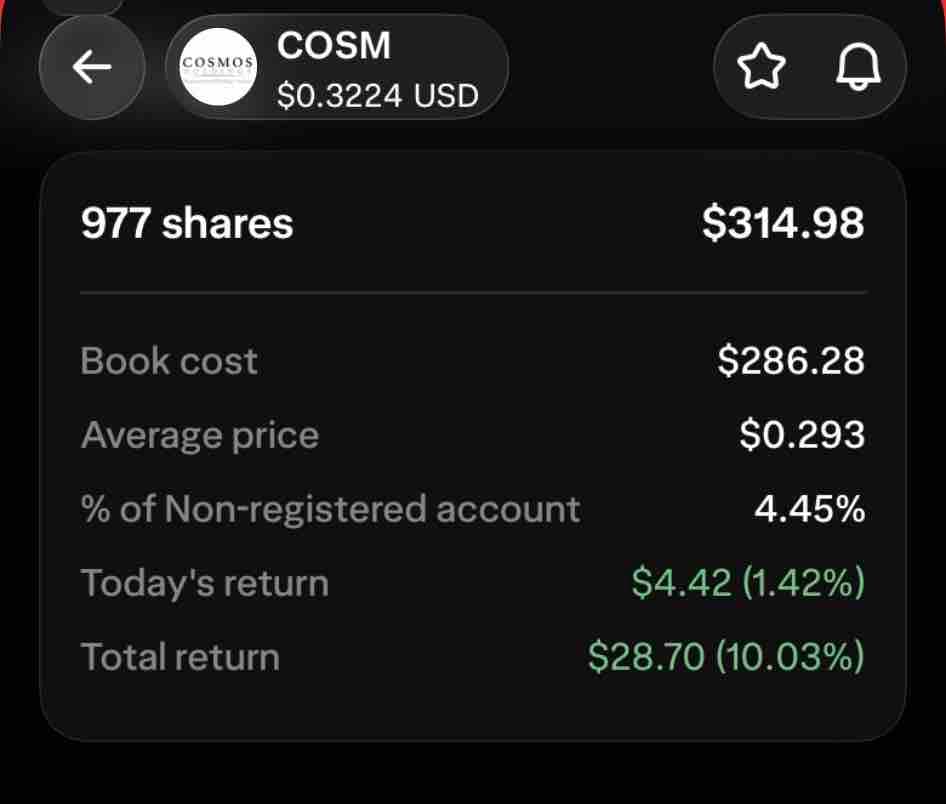
Hey! Been another while since the last update, so here's what's new! For those of you who are new, here's the breakdown of my silly little project: Every time I skip buying coffee at my local bakery, I buy stock instead. It's essentially an exercise in discipline. Basically, the rules are: - stock has to be high risk/reward - must be cheaper than a cup of coffee ($3.25CAD) - can stop buying shares once it caps out on price, or position reaches 1000 shares - not allowed to sell unless it gets at least 100% return - not allowed to sell to take a loss Best case: 🚀🌙 Worst case: Bankrupt or delisted 😵 ☠️ $ASST and $COSM are the two I've bought so far. $ASST is doing it's predictable thing along side $BTC and $COSM had has a slew of news lately. Both are doing well. Has anyone else started this fun little project?? If so, let me know which stock you picked and how that discipline is going! read more
It's that time of the week again! Time to celebrate our wins, no matter how big or small and no matter how good or bad the market has treated us! I'll show you mine, if you show me yours! 😜😅 Leave your WINS in the comments! Top Stocks of the Week 📈 1. $GTCH ⬆️ 14.81% 2. $ASST ⬆️ 11.34% 3. $ORCL ⬆️ 5.75% Top Options of the Week 📊 1. $SMR ⬆️ 133% (Call LEAP - Unrealized) 2. $WAL ⬆️ 75% (Put LEAP - Unrealized) 3. $ET ⬆️ 39.66% (Call LEAP - Unrealized) read more
It's that time of the week again! Time to celebrate our wins, no matter how big or small and no matter how good or bad the market has treated us! I'll show you mine, if you show me yours! 😜😅 Leave your WINS in the comments! Top Stocks of the Week 📈 1. $ASST (Strive Inc.) ⬆️ +20.40% 2. $HOOD (Robinhood) ⬆️ +20.54% 3. $IREN (IREN Limited) ⬆️ +22.13% Top Options of ffh e Week 📊 1. $XOM Jan 15 '27 $210 Call ⬆️ +95.74% (Long Call - Unrealized) 2. $T Sep 18 $7.50 Put ⬆️ +50.00% (Long Put - Unrealized) 3. $AMD Dec 15 '28 $5 Put ⬆️ +40.00% (Long Put - Unrealized) read more
NVIDIA's portfolio is impressive. But I'm not chasing every stock just because NVIDIA owns it. That distinction matters to me. A company can have a brilliant strategic investor and still be a terrible entry point. Price matters. Valuation matters. Balance sheets matter. Execution matters. Timing matters. Take the AI infrastructure names. The underlying theme can be completely correct while the stock is still overpriced. I remind myself of that constantly. A great company isn't automatically a great investment at every price. So when I see NVIDIA putting billions into a company, my process has started looking like this. First, understand why NVIDIA invested. Then look at the company's actual fundamentals. After that, check the valuation. Identify the biggest risk to the thesis. And only then decide whether the current price actually gives me enough margin of safety. Only after all of that do I even start thinking about buying. Honestly, I'm more interested in finding the second-order opportunity than chasing the headline. If NVIDIA is spending billions to solve an AI bottleneck, maybe the real opportunity is another company solving that same bottleneck at a better valuation. That's the rabbit hole I keep going down. Do you buy the headline stock, or search for the second-order beneficiary?read more
Been adding to $GOOGL and $AVGO on this pullback. Here’s why: $GOOGL is down ~18% off its highs. Q2 revenue grew 24% y/y, cloud grew 82% to $24.8b, and the cloud backlog hit $514b. It’s trading under 17x forward earnings — cheaper than $MSFT and $META. The market is pricing in capex fear, not the growth already showing up. $AVGO is down ~25% off its ATH. The same week, AI semiconductor revenue grew 221% y/y and management guided for that segment to double again by 2027. The stock sold off right after arguably its best quarter. Both dips have the same shape: strong numbers, but the market got spooked by the size of the AI spend. That gap between the fear and the actual print is usually the opportunity. Not always, but usually.read more
I made a move this week that might surprise a few of you: I sold my Amazon $AMZN position and rotated the proceeds into Vistra Energy $VST - new position of 64 shares. Here's the thinking behind it. As we've spoken about before, the AI buildout has a bottleneck and it's not chips. We've talked about the "picks and shovels" of the AI data center boom, the companies that profit no matter which AI model or hyperscaler wins. Everyone's focused on GPUs. But there's a quieter bottleneck that's about to become the loudest problem in the room: power. Data centers running frontier AI models need enormous, reliable, 24/7 electricity, and a lot of it needs to come from sources that don't fluctuate with the weather, like nuclear and natural gas. The hyperscalers know this very well. That's exactly why Vistra $VST just partnered with KKR, NVIDIA $NVDA and the Kuwait Investment Authority to launch Helix Digital Infrastructure, a venture built to power AI data centers directly with Vistra committing up to $1 billion as a founding investor. When NVIDIA is co-investing in your power supply, that tells you where the bottleneck really is. Vistra owns one of the largest and most diverse power generation fleets in the country, spanning across nuclear, natural gas, and battery storage. Why Vistra, and Why Now? The Numbers... Growth is accelerating, not slowing. First-half 2026 net income surged to $1.33 billion, up from just $59 million a year earlier, while operating revenue for the same period climbed to $9.66 billion from $8.18 billion. Q2 2026 adjusted EBITDA hit $1.77 billion, up about 31% year-over-year, and management guided full-year 2026 adjusted EBITDA to $7.4 to $7.8 billion, with adjusted free cash flow of roughly $3.9 to $4.7 billion. The company is expanding its physical footprint as well, closing on the Lotus acquisition which added 2,600 MW of natural gas capacity, and moving to acquire Cogentrix Energy later this year. Here's the part that really sold me: it's still cheap relative to that growth as their PEG ratio sits around 0.5. Quick refresher for anyone newer to investing: the PEG ratio takes the P/E ratio and divides it by expected earnings growth, so a PEG under 1 generally signals a stock is cheap relative to how fast it's actually growing, not just cheap on paper. Compare that to close peer Constellation Energy $CEG, which trades at a PEG closer to 1.5x, roughly three times more expensive on a growth-adjusted basis, despite operating in the same sector. On a straight P/E basis, Vistra trades around 16 to 18x forward earnings, roughly in line with its independent power producer group, while CEG trades north of 24x. On top of all that, Vistra is targeting at least $1 billion in share buybacks and $300 million in annual dividends. Why did I sell Amazon instead of trimming something else? This wasn't a "I don't believe in Amazon anymore" trade, it was a portfolio allocation decision. My holdings were already heavily concentrated in mega-cap tech and AI software/hardware names, and Amazon was one of my smallest, least-differentiated positions in that bucket. Selling it did two things at once: it trimmed my biggest concentration risk of too much correlated tech exposure, and it funded a completely different way to play the same AI trend, the energy layer underneath it instead of the software and retail layer on top of it. I still think Amazon is a great business. But "fine and expensive and redundant with what I already own" always loses to "cheap, growing, and gives me exposure I didn't have"... every time. The honest risks I'm not going to pretend this is a risk-free decision. Vistra carries meaningfully more leverage than a company like Constellation. Extreme weather such as Texas winter storms is a real operational risk for a Texas-heavy fleet, and regulatory risk around coal and emissions rules is ongoing. I'm sizing the position accordingly to that risk. This isn't a go all in move, it's simply a rotation to get paid for taking on the AI power bottleneck instead of just riding the demand side of it. Bottom line: everyone keeps chasing the AI winners on the compute side. I'd rather own the thing they all can't get enough of: Power. Curious to hear if anyone else is playing the energy side of this trade.read more
$ORCL is a $355 stock trading at $145 $AMAT is a $1,071 stock trading at $517 $IREN is a $102 stock trading at $44 $NOW is a $195 stock trading at $141 $MRVL is a $316 stock trading at $228 $META is a $810 stock trading at $610read more
This is one of the problems with investing on social media. Someone posts: $SOFI → $50 $CRWV → $250 $CRDO → $320 $APP → $800 And suddenly those numbers are stuck in everyone's head. But where did they come from? That's the part I care about. What revenue growth is being assumed? What margins? What free cash flow? What valuation multiple? How much dilution? What happens if growth slows? And how long is the thesis supposed to take? A price target without those assumptions is just a number. I don't want my investment thesis to be: “Someone on X thinks this stock will hit $300.” I'd rather say: “I think the business can generate X amount of earnings or cash flow, and at this valuation I believe the market could reasonably price it around Y.” Now we have something we can actually debate. That's investing.read more
The reason was the bond market: yields pushed through 5% and repriced every stock at once. But the index color hid the real story. The market did not fall as one. The leaders held. $QCOM closed up over four percent Tuesday while the indexes bled, the cleanest strength on my board. $META held green while the market fell, its relative strength at the top of my scale, though it is getting overbought. The weak side sank. $WDC , $LRCX and $AMAT , the equipment behind the AI chips, carry some of the weakest strength on my board and stayed in distribution. That is the weak side, the names the money is leaving. Two I have tracked: $AVGO kept leaking, down more than six percent, my skip holding. $ABBV walked right up to the line I have watched and my scanner flipped it to a buy, the buyers finally at the door. Not investment advice. Find more of my deep dives on my newsletter 🐝
How am I looking? These are the damages from today😬 Any other LEAPS I should add? These are my current positions, and stocks I am bullish on. Although $GOOGL and $AMZN are in a strong downtrend I don’t expect them to go that much lower, if you want my chart analysis on them both i am happy to share it in the comments
Wow, I really missed out on $BE, I started watching the stock 3 weeks ago. I bought a put from $219 and held to $205 (since I expected a reaction from the gap). I expected us to go to $186 which was my target to buy calls. My small profit is nothing compared to what I would’ve gotten if I bought calls as I sold my put. Although the returns would’ve been much greater, it reminds me of the time when I bought $SOXL (3x $SOXX) at around 15$ and sold at 30$, and it ran up to 280$ in a year, Or $MU at $50-60. I need to learn how to leave my money alone and invest long-term instead of chasing measly gains. I left so much money behind trying to trade instead of investing. read more
Last week, I took some VIX calls to hedge my portfolio when the VIX was at 14.10 I took 3 contracts @ $1.50 with a $19.50 strike and Oct 21 Exp. Today, I sold 1/3 contracts for a 25% gain and will continue to hold the remaining 2 contracts Drop your best hedging strategies below in the comments, I'd like to hear others perspectives about this! $SPY
I’m currently holding about 10% dry powder in my portfolio If it were you — which route do you think you'd go in in real time? Broad Market DCA: Put it on autopilot into low-cost S&P 500 or total market ETFs? Opportunistic Dip Buying: Wait for a sharp 5–10% correction in high-conviction growth names? Defensive Yield: Lock it into short-term stuff w/ little yield? Alternative Rotation: Put it to work in hard assets, dividend growers, or small-caps? Thoughts? 🤔💡 #Investing #Stocks #PortfolioStrategy #PersonalFinanceread more