This is one of the problems with investing on social media. Someone posts: $SOFI → $50 $CRWV → $250 $CRDO → $320 $APP → $800 And suddenly those numbers are stuck in everyone's head. But where did they come from? That's the part I care about. What revenue growth is being assumed? What margins? What free cash flow? What valuation multiple? How much dilution? What happens if growth slows? And how long is the thesis supposed to take? A price target without those assumptions is just a number. I don't want my investment thesis to be: “Someone on X thinks this stock will hit $300.” I'd rather say: “I think the business can generate X amount of earnings or cash flow, and at this valuation I believe the market could reasonably price it around Y.” Now we have something we can actually debate. That's investing.read more
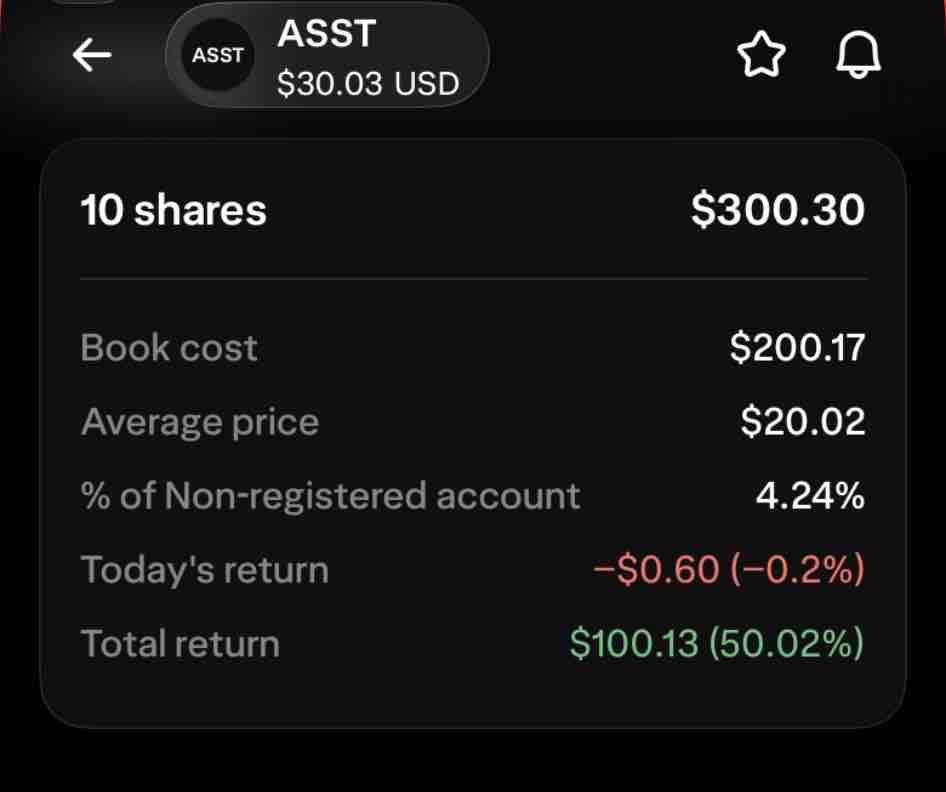
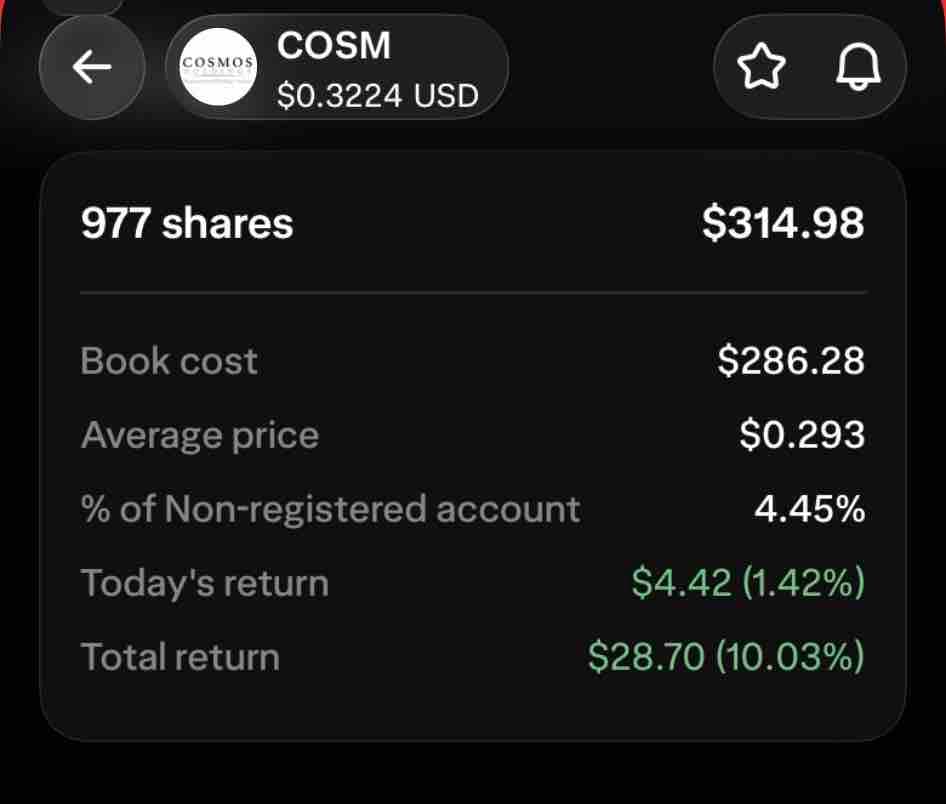
Hey! Been another while since the last update, so here's what's new! For those of you who are new, here's the breakdown of my silly little project: Every time I skip buying coffee at my local bakery, I buy stock instead. It's essentially an exercise in discipline. Basically, the rules are: - stock has to be high risk/reward - must be cheaper than a cup of coffee ($3.25CAD) - can stop buying shares once it caps out on price, or position reaches 1000 shares - not allowed to sell unless it gets at least 100% return - not allowed to sell to take a loss Best case: 🚀🌙 Worst case: Bankrupt or delisted 😵 ☠️ $ASST and $COSM are the two I've bought so far. $ASST is doing it's predictable thing along side $BTC and $COSM had has a slew of news lately. Both are doing well. Has anyone else started this fun little project?? If so, let me know which stock you picked and how that discipline is going! read more
Wealthsimple says that when you sell a U.S. security from a CAD account, the 1.5% FX fee is effectively applied to the exchange rate, so you receive about 98.5% of the converted CAD amount. You look at “$0 commission” and then discover the currency conversion is quietly taking a bite out of your money.
🗓 Post Date: 9/18/26 ----------------------------------- 🚦 Started: 8/17/26 | 💵 $100 Only 🎯 TRADE DETAILS - STILL OPEN #️⃣ Trade #: 5 🎟 MOS | 2 shares @ $24.77 avg 💲 Capital Deployed: $49.54 💵 Cash Remaining: $55.82 🕒 Time in Trade: 5 days ✨️ Trade Results: TBD 🪜 CLIMBING PROGRESS 🔙 Previous Ladder: $105.36 👣 Step Change: TBD 💰 Current Ladder: TBD 🧗♀️ Total Climb Returns: +5.36% ⛰️ Total Journey: 5 weeks 🔄 Trades Completed: 4 ----------------------------------- Hello tradevestors, 👋 Week 5 is officially over, but my $MOS trade is still open from Monday. I bought 2 shares, sold 1, then bought another. I’ll calculate the final P/L once the entire trade is closed since the multiple transactions make it a little more complicated. Follow along, and let’s see how high I can climb this 1 Stock Ladder. 🧗♀️ 🪜 Myra, The Weekly Tradevestor read more
Taking a price target from $80 -> $57 for an industry leader like $NFLX is a no joke downgrade! Downgrades like this intrigue me, as they're rare for quality companies & 'potentially' create opportunities. Sounds like analyst's primary concerns are 'softening user engagement & content slate risks'. Full disclosure: Bullet points below taken from Gemini's overview on the downgrade. - Weakening Overall Engagement: Wells Fargo estimates average viewing fell to ~1.6 hours per subscriber per day in the first half of the year—down roughly 8% compared to adjusted 2023 levels. Overall viewing hours on Netflix dipped 8% year-over-year. - Declining Impact from Originals: Viewing hours for the top 100 original series fell 3% in H1 and are projected to drop 21% year-over-year in H2. Cahall argues Netflix suffers from a "hit problem"—expanding into reality TV, documentaries, live sports, and gaming without generating enough mega-hits. - Content Distribution Dilution: Broader distribution onto third-party platforms like YouTube expands reach but dilutes the exclusivity of blockbuster original programming. - Margin & Earnings Pressure: Second-half content investments and a shifting schedule are expected to weigh on profitability. Wells Fargo lowered its 2027 and 2028 EPS estimates to $3.77 and $4.52 (below consensus), projecting operating margins of 32.6% in 2027 and 34.2% in 2028. Where does this leave me? My fair value continues to be ~$70, so today's $71.xx definitely doesn't provide the margin of safety I'd need to start buying shares. Strangely enough, Wells Fargo's new price target fairly close to the margin of safety I'm looking for, assuming of course nothing changes between now & then (if it ever get there).read more