DEBUNKED: The RRSP Tax Trap 🪤
“The RRSP is a tax trap."
That is the biggest myth in Canadian personal finance.
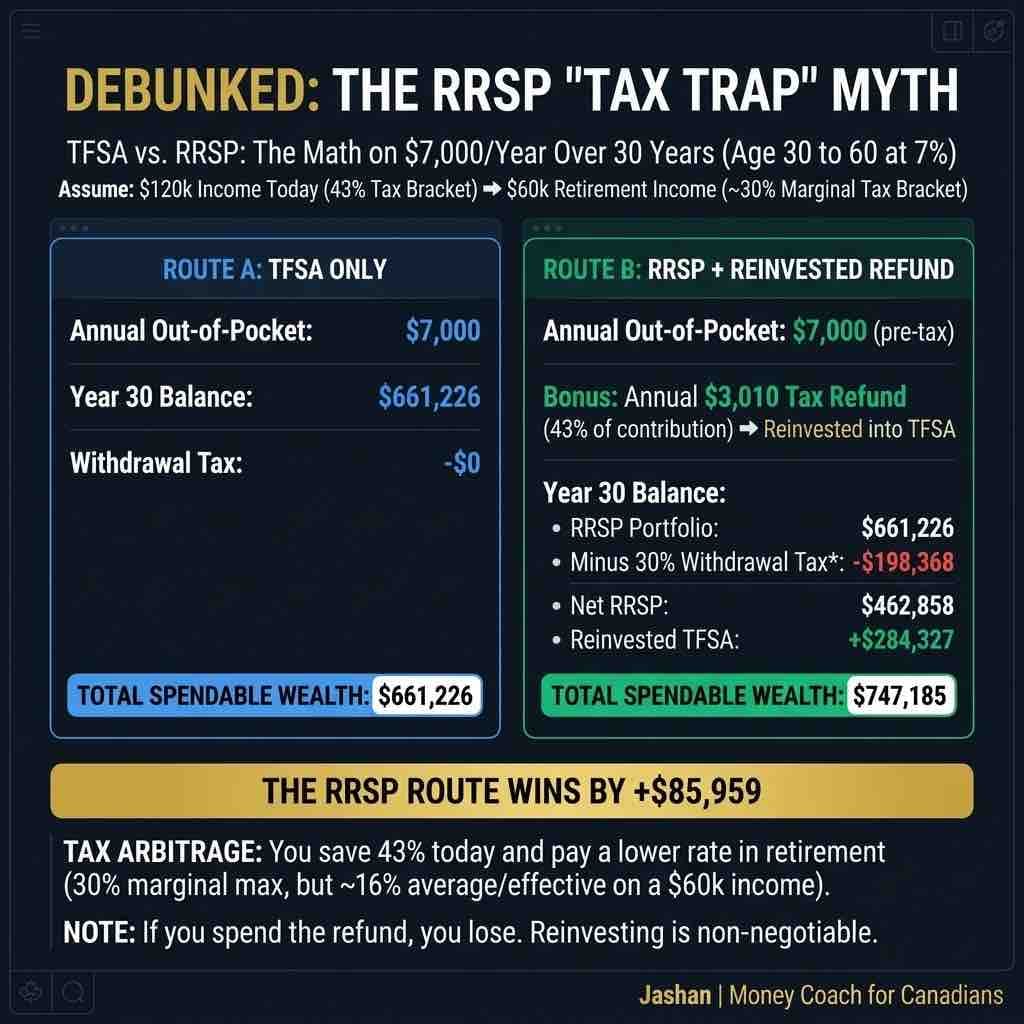
Let’s run the exact math for a 30-year-old earning $120k (43% tax bracket), retiring on $60k (30% tax bracket), and investing $7,000/year for 30 years at 7%.
Route A: TFSA Only
You invest $7,000 after-tax.
It compounds to $661,226.
Withdrawal tax: $0.
Total Spendable Wealth: $661,226
Route B: RRSP + Reinvested Refund
You invest $7,000 pre-tax.
It hits the exact same $661,226.
At a 30% retirement tax rate, you keep $462,858.
Looks like a trap, right?
But critics ignore the refund.
At a 43% tax bracket, your $7k RRSP deposit triggers a $3,010 tax refund every single year.
If you reinvest that $3,010 refund directly into your TFSA, it compounds to an extra $284,327 tax-free.
The Final Verdict:
$462,858 (After-tax RRSP)
+
$284,327 (Reinvested TFSA)
=
$747,185 (Total Spendable Wealth)
The RRSP route beats the TFSA by $85,959 in pure liquid cash.
The RRSP is not a tax trap.
Reinvest your refund, win the tax arbitrage game, and let the math work.