What does it take to retire at 55, and can covered call ETFs help replace your employment paycheque? In this episode of Moementum Finance, I'm joined by @retirement_rants, an investor on Blossom community who retired at 55 in September 2025 after more than a decade of investing primarily in index ETFs like VFV (S&P 500) and QQC (Nasdaq 100). But as retirement approached, Carlos made an interesting transition: moving from traditional growth-focused index investing to diversified covered call ETFs targeting approximately 12–16% annual income. Carlos shares his inspiring journey from growing up in a household where money and investing weren't openly discussed, to discovering the stock market at 42, building wealth through consistent investing and the power of compounding, and eventually achieving early retirement. We discuss why he moved toward income investing, how covered call ETFs help him generate monthly cash flow, and why replacing his employment paycheque without regularly selling shares became an important part of his retirement strategy. We also get into his actual portfolio holdings, including QQCL, HYLD, USCL, QDAY and BDAY, why he avoids single-stock covered call ETFs, how he approaches diversification, and why he doesn't believe investors should simply chase the highest advertised yields. Carlos also shares his thoughts on the 4% rule versus his approximately 8% portfolio withdrawal/spending rate, managing market downturns, maintaining a cash reserve, and balancing retirement spending with reinvestment. Beyond investing, Carlos discusses the realities of retiring at 55, travelling with his wife, managing RRIFs, LIFs and TFSAs, deferring CPP and OAS, and some of the financial decisions he would have made differently, including making greater use of a spousal RRSP. He also shares valuable lessons about funding his children's education through RESPs and teaching the next generation about investing. 💬 I'd love to hear from you: Once you reach retirement, would you sell shares in retirement, or switch to covered call ETFs and collect distributions? Let me know why in the comments! Disclaimer: This video is for educational and informational purposes only and does not constitute financial advice. High-yield covered call ETFs carry risks, distributions are not guaranteed, and a high distribution yield does not necessarily translate into a high total return. Past performance is not a guarantee of future results. Information is accurate as of the posting date and may change over time. https://youtu.be/YN0Tw5ZtDZ8?si=QFJM3GZB2xfDyXHP
1,276 views
3 Comments
ETF Go
@etf.go · 36m
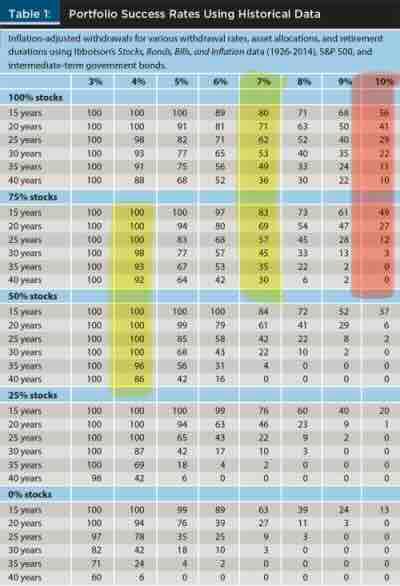
Based on historic data the probability of success (ie not running out of money) at a consistent 8% withdrawal rate for 30-40 year retirement is too low for me to risk. 🤷♂️ Maybe that data is no longer relevant. Maybe future returns will outpace past returns. But maybe they won’t. Maybe the same probabilities will hold. 🤔 Up to each retiree to decide how far they want to push the odds but flexibility of withdrawals likely important for all. 👍
David
@freedombydesign · 42m
Good interview. I’m interested in the withdrawal rate. Some say 3% and he spends 8%. That’s a large difference.
Sunil Lalwani
@sunil1985 · 1h
This would be an interesting video. Will definitely watch it today 🫡
See the full comment section 👀Sign up for the full Blossom experience!