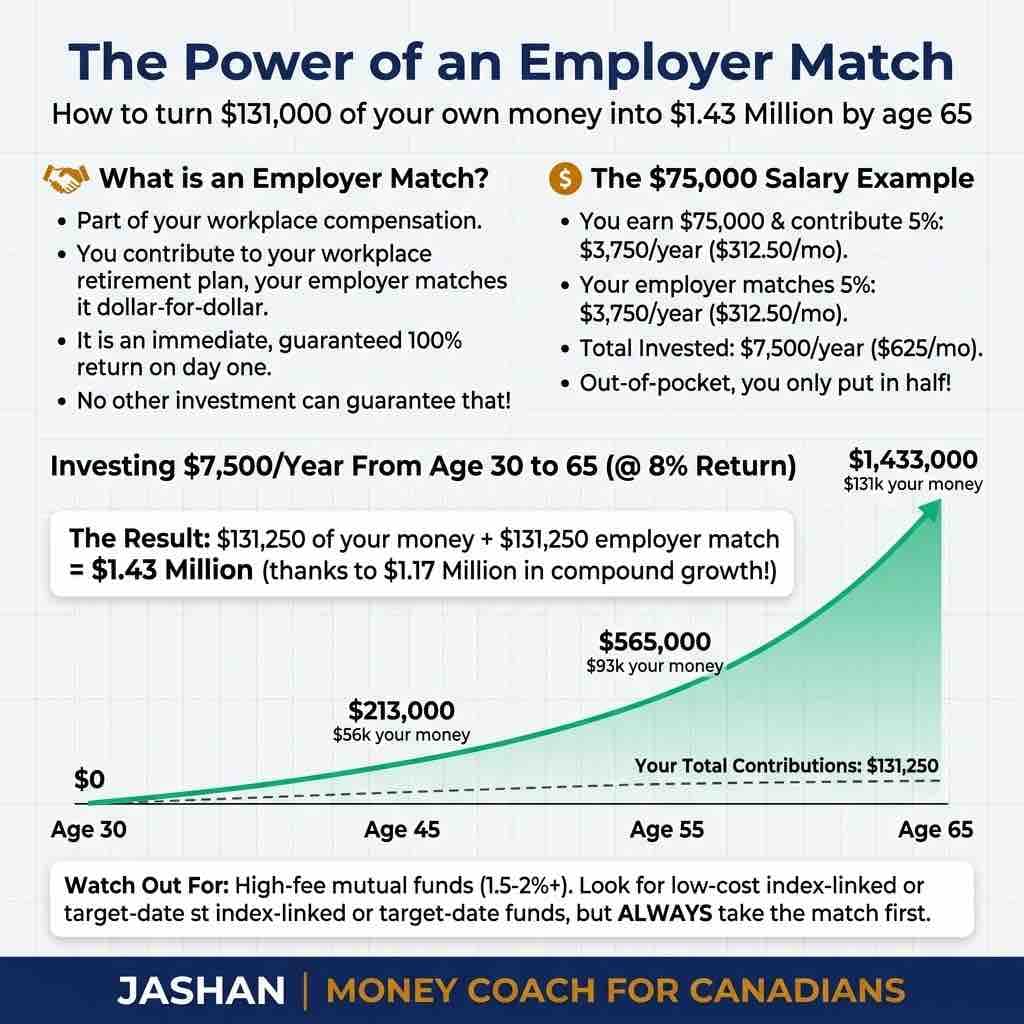
Skipping your employer match is the same as turning down a pay raise. 👉 What It Is An employer match is direct compensation. You deposit into a workplace retirement plan, and your employer matches it dollar-for-dollar up to a set cap. That is an immediate, guaranteed 100% return on your money on day one. 💰 The Math at $75,000 Salary Earn $75,000 per year with a 5% company match. You contribute 5%: $3,750 per year ($312.50 a month). Your employer adds: $3,750 per year. You put $7,500 to work every single year while only paying half of it out of pocket. 📈 The Results (Starting from age 30 to 65 @ 8% Return) Your own contributions: $131,250 Employer match: $131,250 Compound growth: $1.17 Million Total nest egg at 65: $1.43 Million ⚠️ The Catch: High Fees Many Canadian group plans stick you with mutual funds charging 1.5% to 2% management fees. Look for index-linked or target-date options to keep costs low. But even if high-fee funds are your only choice, take the match anyway. A 2% fee never wipes out an instant 100% bonus on day one. 🎯 The Playbook 1️⃣ Contribute only the exact amount needed to get the full match. 2️⃣ Never add extra voluntary money to high-fee group plans. 3️⃣ Send all remaining savings into your personal self-directed TFSA or FHSA with low-cost index ETFs.
708 views
2 Comments
AK
@ak.p92 · 12d
Quick question: If my employer is offering a DC plan match up to 6% and also a stock option match upto 3% in the Rrsp. Which is the ideal place to contribute?
See the full comment section 👀Sign up for the full Blossom experience!