How we Build Wealth as Renters
Before my trip to Japan, I received harsh comments on my post because I said that I didn't care about home ownership and cottages are a money pit. This hit a nerve with this person who felt the need to put me down.
"Everyone here knows that you desperately want to be a homeowner. You are LYING to yourself and everyone on Blossom knows it except for you!"
When I told him that he was being condescending, he doubled down, repeating stereotypes about renters. Insisting that I must be broke. He took my refusal to engage in a rent vs buy debate with him as proof that I was wrong.
He concluded that since, by my own admission, the estate taxes are more favourable for homeowners than renters, I am hurting my son by being a renter.
So... I'm a bad mother for renting?
I often feel like a bad mom. When my son was a toddler, we'd ride the length of a TTC subway line because it entertained him enough for me to work on my master's thesis (I had no childcare) 😅. Last year, my son overheard me saying that I was happy to be working on Christmas for the overtime pay, prompting him to announce at the gathering I missed that 'Mama is working because she cares more about money than her own son'. Recently, my son and I were sharing a bowl of ramen noodles at the food court when an unhoused person, asked me to buy him a bowl. When I said 'Sorry, I don't have any money' my son sobbed loudly yelling 'Mama you are LYING, you have thousands of dollars in your bank account!'. It's better to fumble through awkward money conversation then to not have these discussions.
The reason I don't value home ownership is related to my childhood experiences. For those interested in that story, I will share it in the pinned comments below. Long story short, I don't drive. The Canadian dream of living in a suburb is *my* definition of hell. Unsurprisingly, because of our childhood my sisters and I all live downtown. Furthermore, due to my neurodivergence, I don't want to deal with the drudgery of shovelling snow, lawn care and other home maintenance tasks. Being a women with ADHD, I carry a lot of shame for not living up to gendered homemaking expectations. By renting, I can pay to outsource these tasks. Walkable neighbourhoods are rare in Ottawa, a sprawling car dependent city. Unlike the suburbs where homeowners tend to be the majority, in Canadian downtown cores, this ratio is flipped.
You aren't going to tell a vulnerable female commuter that works 12 hour shifts and walks home from work past midnight and before dawn with a flashlight 🔦 that I don't deserve to pay for an apartment rental in a SAFE area. We don't shame people for going out to restaurants, paying for dry cleaning, dog grooming, car repairs or literally any other service.
While I don't value homeownership, doesn't mean that I will gaslight anyone who dreams to own their home. The same playbook that makes you a wealthy renter will also build your down payment.
The average age of the first time homebuyer in Ontario is now 40 years old! It is dishonest to pretend that homeownership in metropolitan cities is a meritocracy. This is due to decades of policies pushing young families away from cities. Housing supply in North American cities have been artificially restricted due to exclusionary zoning. Not to mention the history of redlining were banks denied mortgages specifically to black and indigenous families.
Don't compare yourself with folks who bought their homes 20 years ago, when it was affordable. Renting or buying, tougher choices are needed compared to those who got in earlier. Investing is the great equalizer since it's more accessible than homeownership.
Both my husband and I had non-linear career paths, hence it took us longer to get established professionally. Since getting married, we have moved to 3 different cities in search of better career opportunities. My husband's career benefited from these moves leading to him having a much higher salary. While larger cities are more expensive, they also offer more opportunities for networking and carrer advancement. The real estate market is more efficient than people realize, the trade offs of having less opportunities and lower salaries in smaller towns are reflected in the lower housing costs.
Why am I worried about retirement? I had to drop out of the workforce when my son couldn't adjust to daycare. The week my son was born we were sued by a collection agency for failure to repay my husband's student loans. Unfortunately, my husband is over a decade older than me so I was terrified we'd have nothing saved for his retirement.
Had we bought a place we wouldn't have been able to navigate these financial hardships. Fortunately, because we were renting a one bedroom apartment in Toronto we could find a way to live on one income, although we couldn't save for retirement, we contributed to my son's RESP (529 plan equivalent). The pandemic allowed my husband to work remotely allowing us to relocate from Toronto to Ottawa (medium cost of living city) for my current job. Renting allowed us to be location flexible to pursue more lucrative career opportunities, resulting in us now earning over 200K/ year as a couple.
We were pressured to buy a place once we moved to Ottawa, however the math did not make sense because we want to live downtown. The downtown condos built in the last 20 years are too small for families (due to condos being built for investors and not end users). The older condos are spacious and cheaper, however the condo fees can run up to $1300/month. When we looked into units in older buildings with a condo lawyer, we uncovered multiple lawsuits and issues due to decades of delayed maintenance.
The Math Behind Why we Rent
A 2 bedroom downtown condo in our area goes for 670,000 K. The unit would be tiny with a bad layout. The condo fees for the unit are $900/ month. If we were to buy this condo using 100K as a down payment, the mortgage would be 3,300 per month. Adding the monthly condo fees, taxes and insurance the costs to own are $4,800/month. Meanwhile the rent for our larger apartment is half the costs of owning! Our building has pool, a scenic view of the city and a dining room appropriately sized for a family! It's not an apple-to-apple comparison we don't have in-suite laundry, our laundry room is in the basement and we have shitty old appliances. However renting allows us to invest 3-4K per month AND afford family vacations. Looking at historical data, Ottawa downtown condos have appreciated at a rate of 2% per year above inflation. Meanwhile, in the four years we have lived in Ottawa we went from zero to over 300K invested! 🤯
How we make renting work:
1) Use All Tax Sheltered Investment Accounts for Investing
The FHSA (in Canada) is the renters RRSP, lifetime contribution limit of 40K means that my husband and I will get 80K in extra in RRSP contribution room.
2) Screen Your Landlord
Just as a prospective landlord will screen tenants, you should screen your landlord.
Check how the property is maintained.
Being forced to move is stressful and expensive. My family avoids this by renting from buildings owned by rental companies. I prefer the service from professional landlords with full-time staff and a 24 h super on call. Look up Google and reddit reviews for rental companies.
Introduce yourself saying that you are a long-term tenant looking to stay 'X' years and ask your potential landlord about their intentions to sell the home etc. You can't predict the future, but you can make an informed decision.
3) Lean into Location Flexibility
We rent to live in a walkable neighbourhood in the best school district for my son. In many urban areas it's cheaper to rent than own. This is because you can only charge what the market will bear. Obviously, your landlord didn't buy the property yesterday, they profit from their business.
4) Don't Rent More Space than you Need!
Homeowners tend to get more space than needed while renters tend to only rent the space they need. Embrace this, bigger homes mean more money spent on utilities, furniture and junk you don't. Consider multi-unit housing to reduce costs via economies of scale. People overestimate how much a larger home will make them happier while underestimating how much a longer commute will make them miserable.
5) Invest more than the difference
Just as a homeowner shouldn't ONLY rely on their home equity for retirement, renters should be investing MORE than the difference between the costs of owning vs renting to build up a sufficient nest egg. Psychologically, it is hard to have the discipline to save, homeowners benefit from the forced savings of a mortgage. Setting up auto deposit into your brokerage account helps!
6) Ignore The Haters
Don't feel pressured to buy if you're not ready. Homeowners are also throwing money away on front-loaded interest, renovations, real estate transaction costs, land transfer taxes etc.
7) Evaluate What matters to You
Money, like time, is a limited resource. Decide what matters to you and budget accordingly such that your spending aligns with your values. Be flexible as priorities change over time.
Your unconventional financial journey is not failure but a story of resilience.
Plot Twist
Over the weekend my uncle, a Silicon Valley Tech CEO, visited us. His wife gave my sisters and I envelopes to open at the same time.
My son saw my face change. 'What's wrong mama, you look sad. I guess you didn't like your card!'
I was stunned to see a check with my name on it and a lot of zeros..
My sister whispered "Are you going to buy a house now?"
"Nope " I replied.
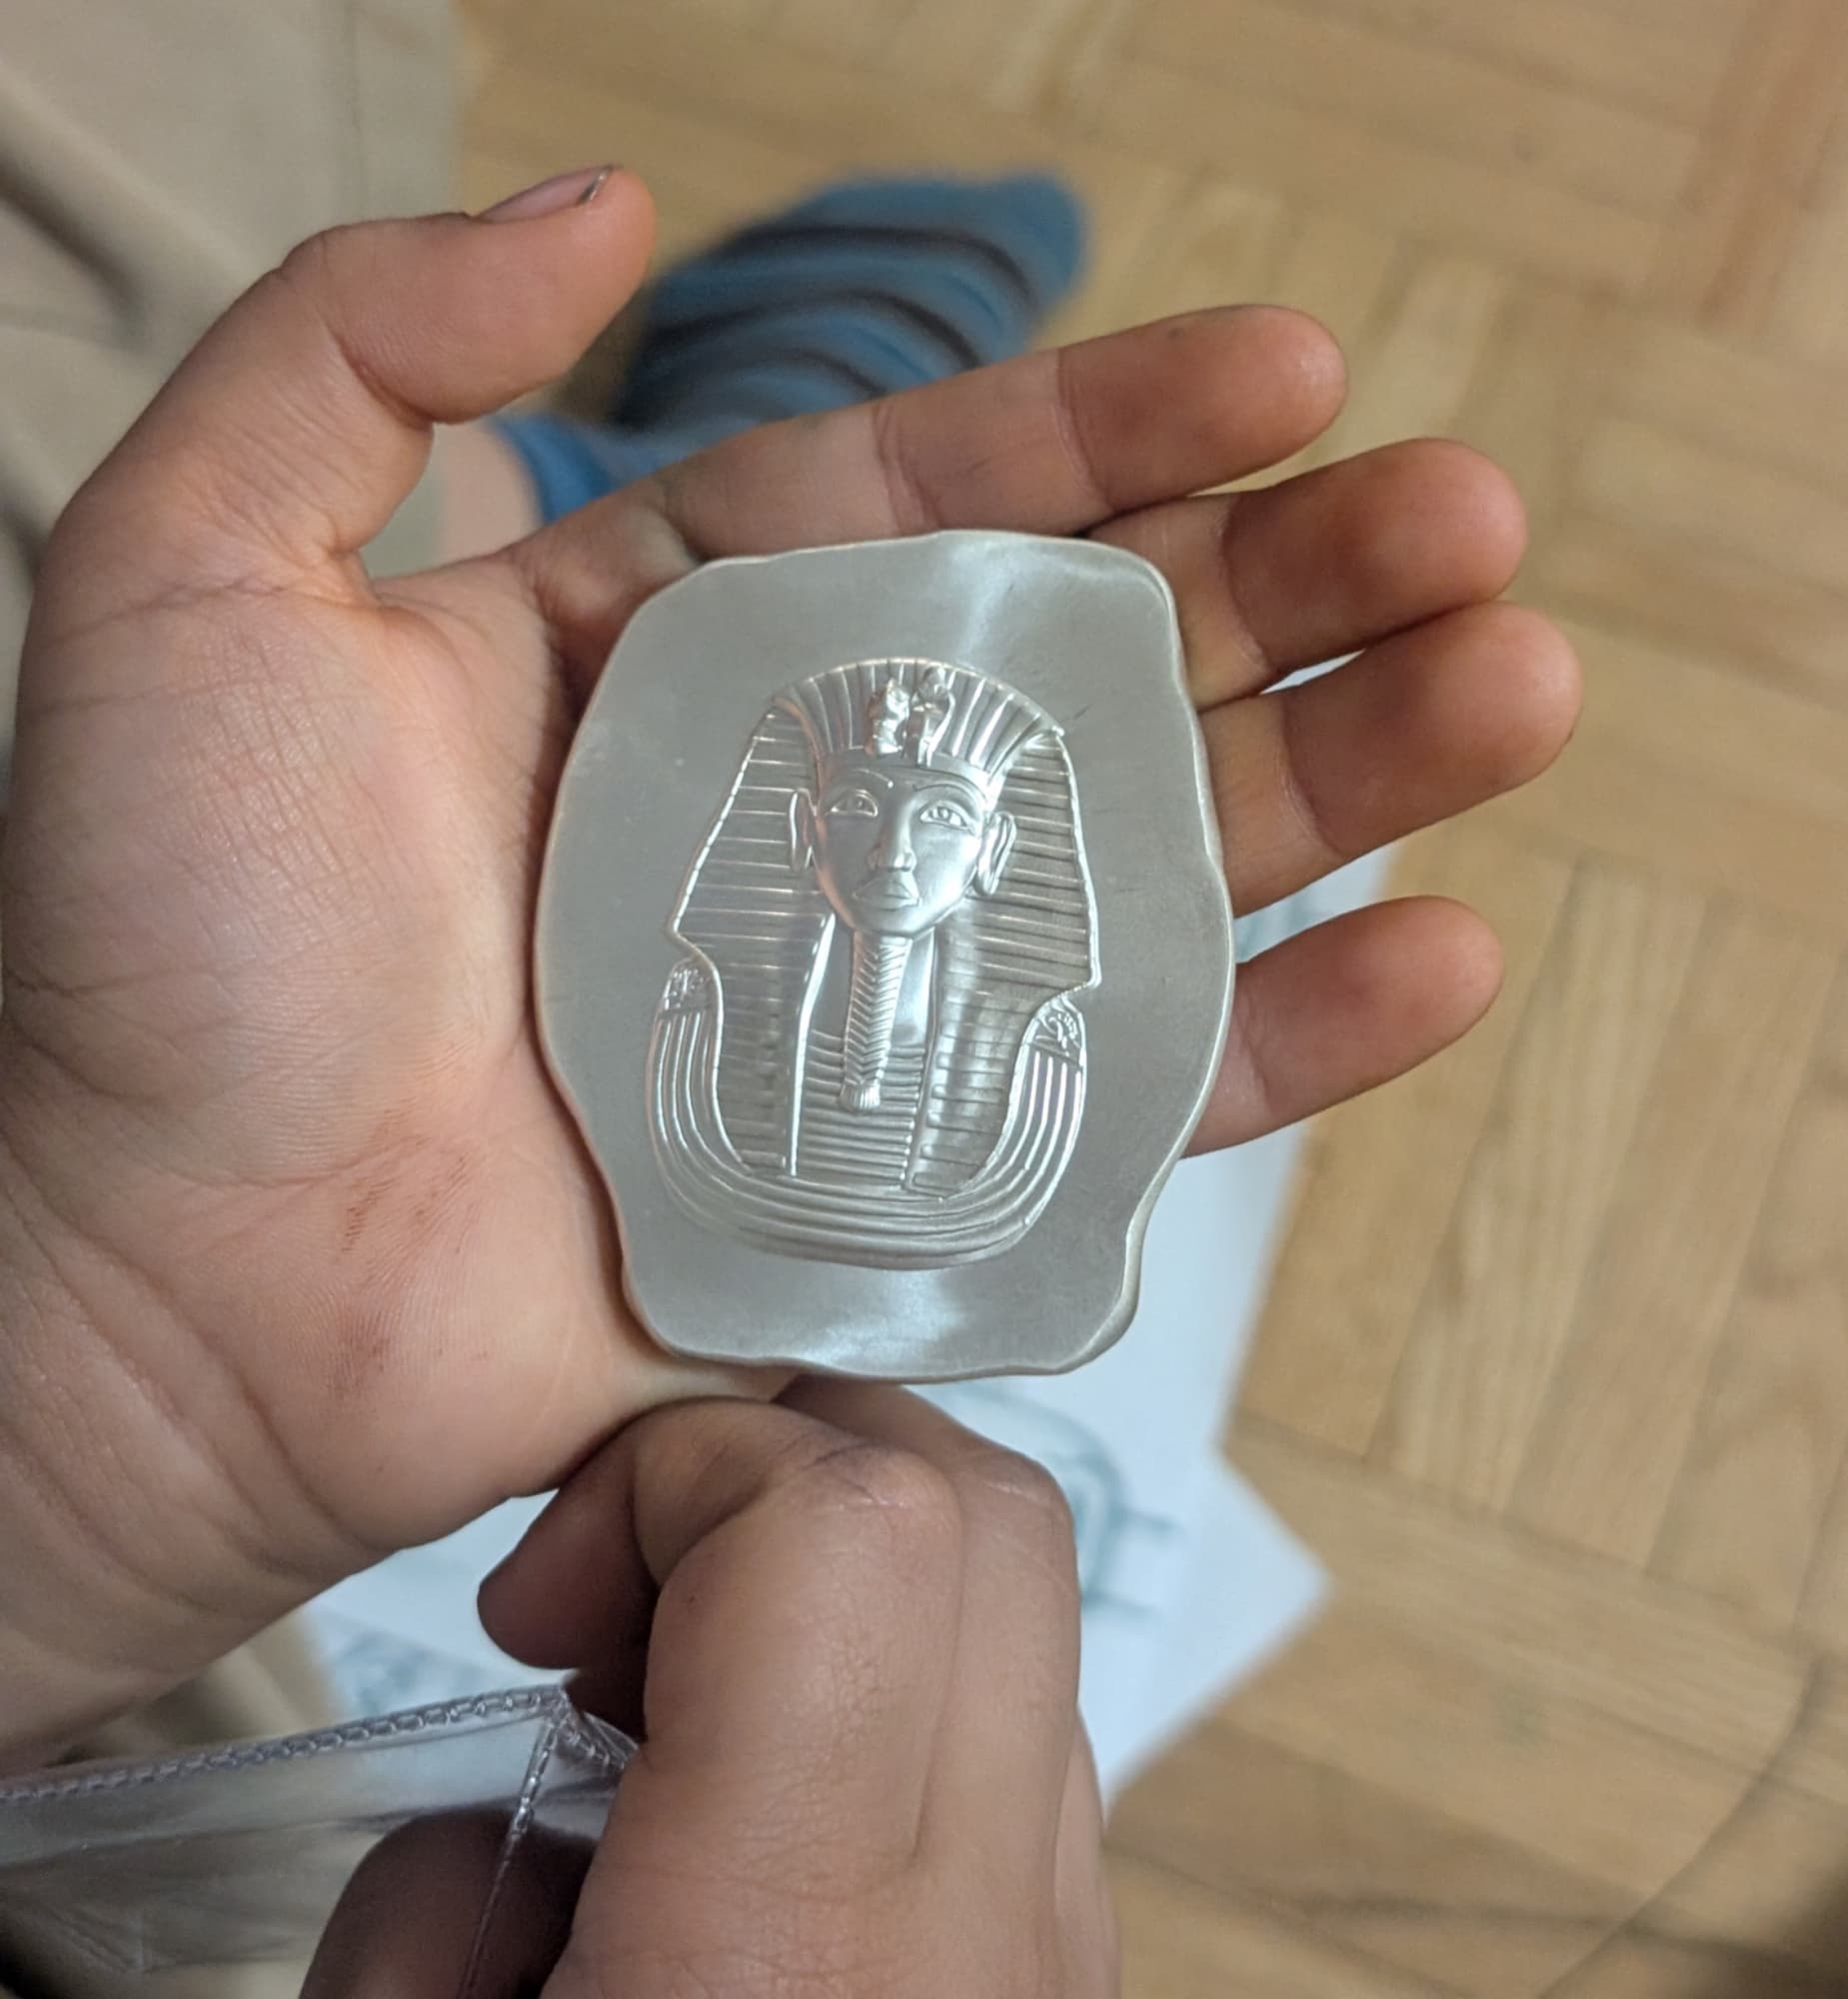
It will be invested. I will set aside enough for my husband to get the watch he wanted. I gave my son $500, which he promptly spent on a 5oz silver bar.
After depositing the check my bank is calling us non-stop trying to sell mutual funds. They also informed our old mortgage broker. We are ignoring their calls.