Nokia Q3 2026 Earnings: AI Growth vs. Execution
Nokia reported Q3 results, and there's plenty for investors to digest.
THE GOOD NEWS:
1) Revenue increased 10% year over year to €5.15 billion.
2) Comparable operating profit jumped 35% to €605 million, beating analyst expectations.
3) AI and cloud customer sales surged 123%, with €1.5 billion in new orders during the quarter.
4) IP Networks revenue grew 43%, while Optical Networks grew 18%.
5) Nokia expects combined IP and Optical Networks growth of 25–30% in 2027.
6) Nokia, T-Mobile and NVIDIA completed the first AI-RAN call on a live commercial network. This is an encouraging step toward making AI-RAN a real business.
THE BAD NEWS:
1) Reported operating profit declined 22% year over year, reflecting restructuring and integration costs.
2) Nokia lowered its expected free-cash-flow conversion to 35–55% of comparable operating profit as it invests in working capital and continues restructuring.
3) AI-RAN is still an emerging opportunity. Successful demonstrations and field trials must translate into commercial contracts and profitable revenue.
4) Nokia maintained its full-year comparable operating profit outlook of €2.1–€2.6 billion. That's reassuring, but it isn't an increase in guidance.
MY TAKEAWAY:
Nokia's AI networking business is already growing, while AI-RAN could provide another growth engine over time. My speculative thesis is that Nokia can build on its existing telecommunications technology, improve network performance and develop additional revenue streams.
The opportunity is real, but execution matters. I'll be watching commercial adoption, cash flow and profitability rather than just the headlines.
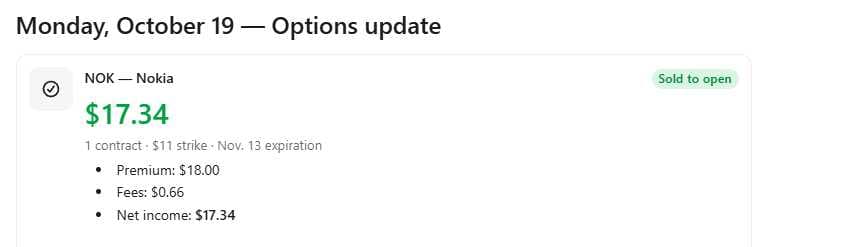
I do have a call option on this position as I'm using the premium as a substitute for the dividend and giving myself an exit price.