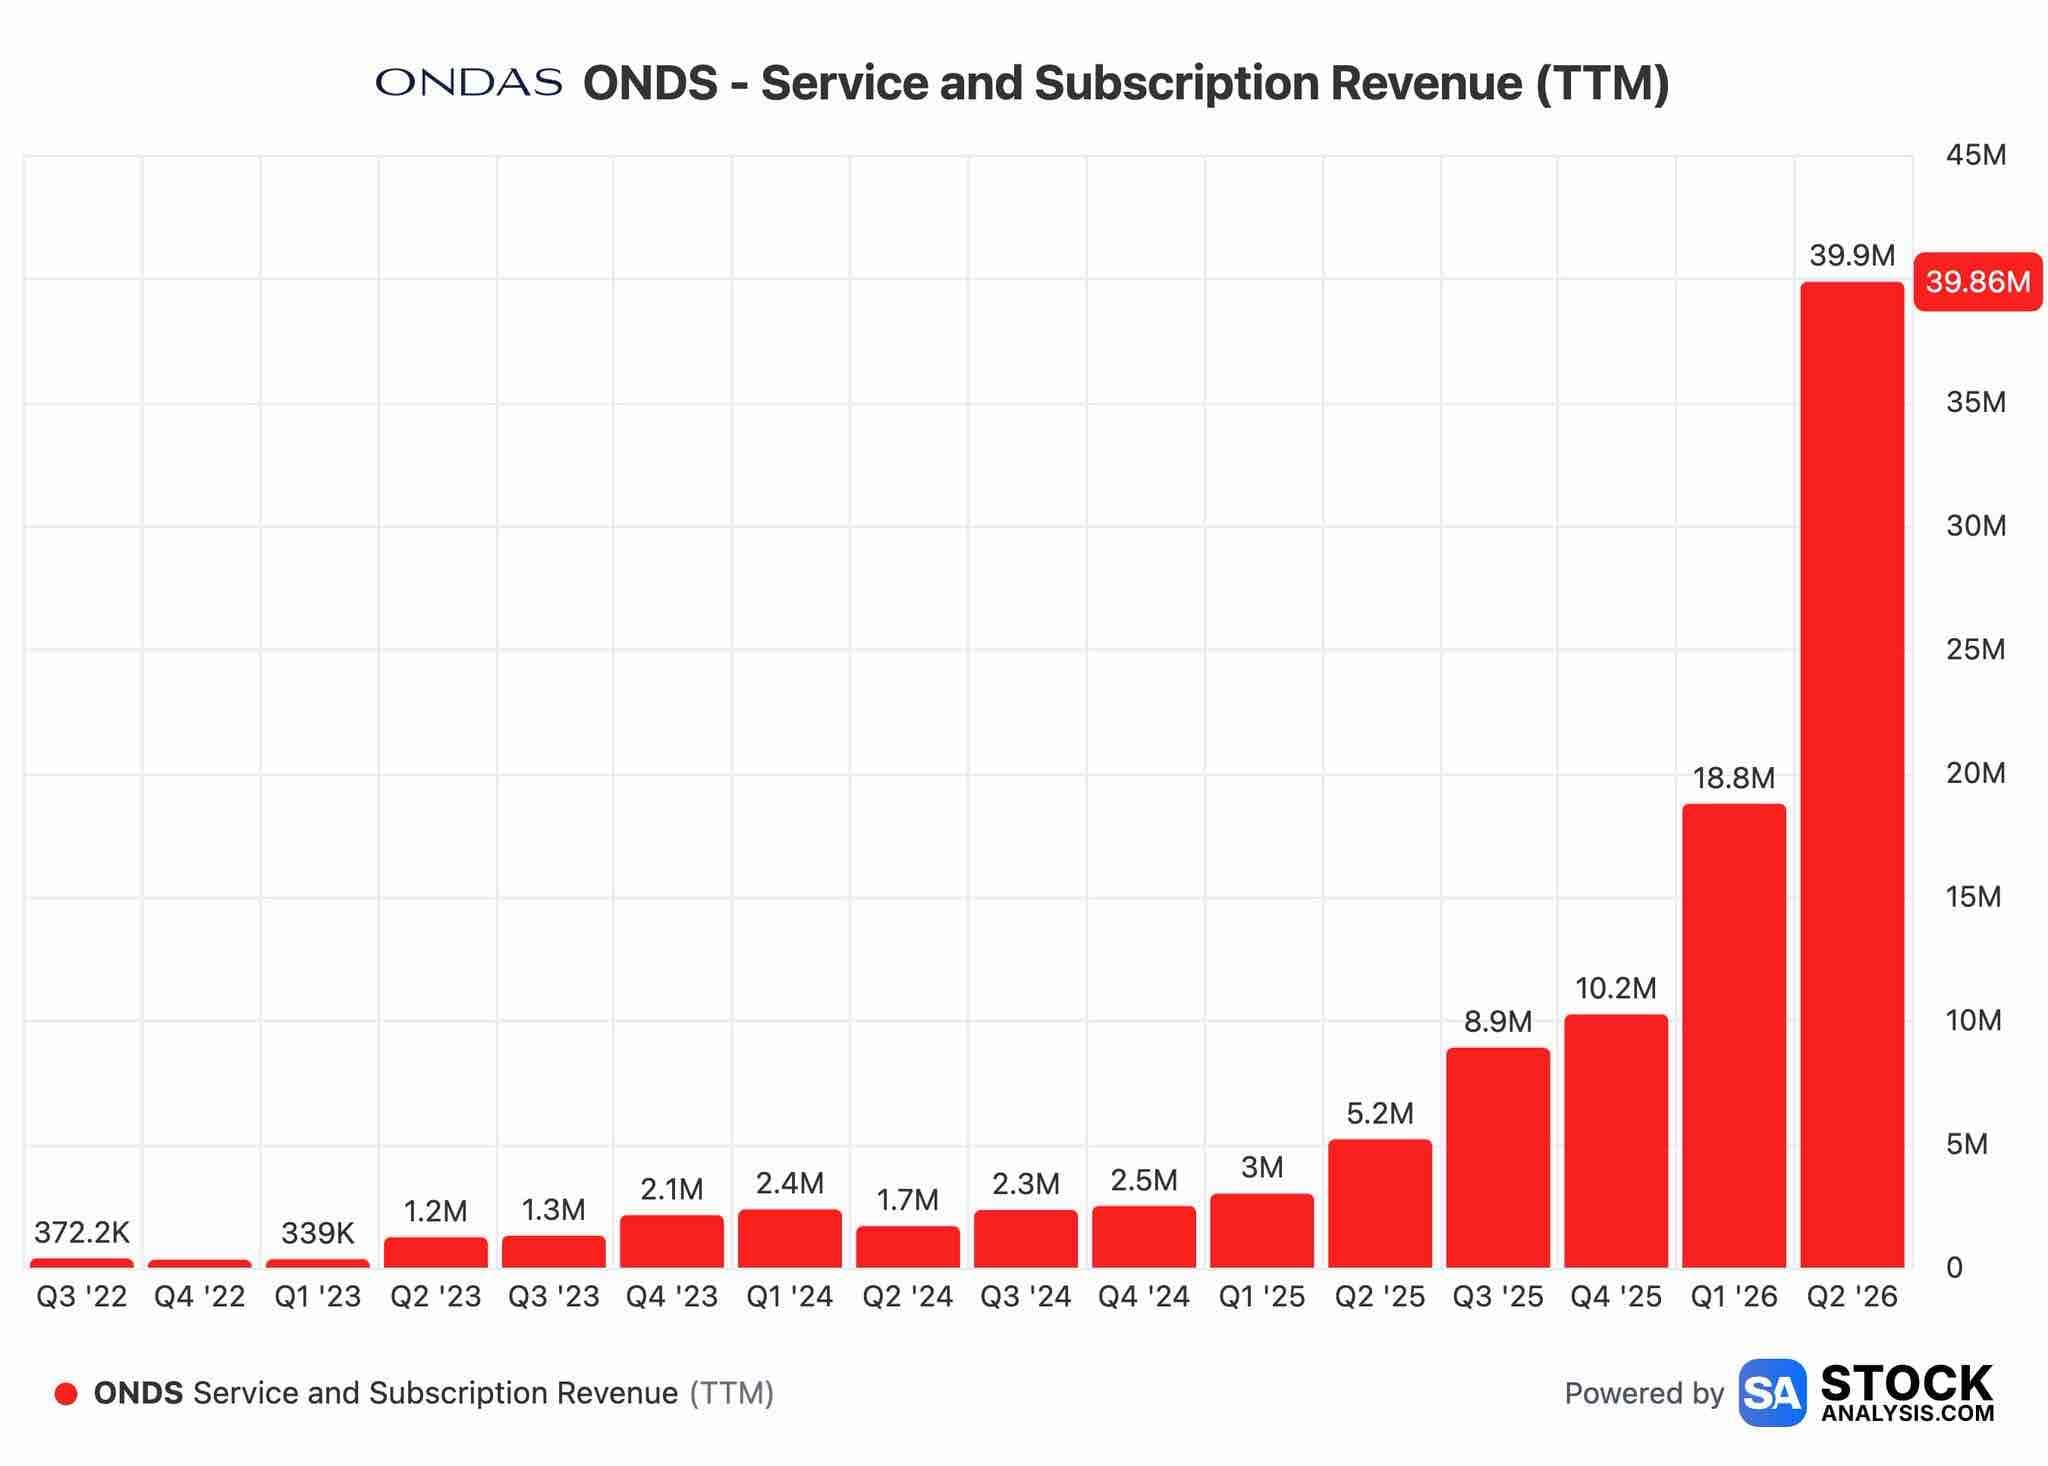
I like recurring revenue models. This subscription revenue from Cyberhawk/services is extremely appealing. Check this out... - 112% net retention rate. - 95% is recurring revenue. - Software: $7.6M ARR target. - Shell, QatarEnergy, PG&E, SSE, etc... Ondas is clearly acquiring the technology to be consider a vertically integrated technology leader and prime U.S. defense contractor. I get it, shareholders - it's not awesome to see dilution, but don't pretend like you don't know why/where it's happening/going. And yes - clearly a large portion of business is product/development related, but think bigger picture. Development = hardware sales = integration = application layer = maintenance/services. It's obvious this is an ecosystem play. In my opinion - Ondas is drawing similar strategical "ecosystem" parallels to Voyager. Can you spot the innovative MOAT, integations, partnerships and recurring revenue model embedded within? Now, I'm just starting my research - but I think these are both two companies that share a similar mandate... Both appear to be assembling ecosystems of complementary technologies to modernize industries dominated by entrenched giants. These often are industries where ridiculous tax payer or corporate spending often delivers slow innovation cycles or underwhelming value in return. It seems there is shared ambition: better technology, faster deployment, greater value. Each company has attracted the attention of "value juggernauts" like Palantir or Anduril, forming partnerships and strategic integrations through shared values and aspirations. Perhaps a complimentary duo in the modern-defense-complex. Honestly, I won't sugarcoat dilution - but the game-plan looks freaking obvious... Investments like these need investors who can think long-term, understand a strategic roadmap, and find trust in a founding management team. $ONDS$VOYG