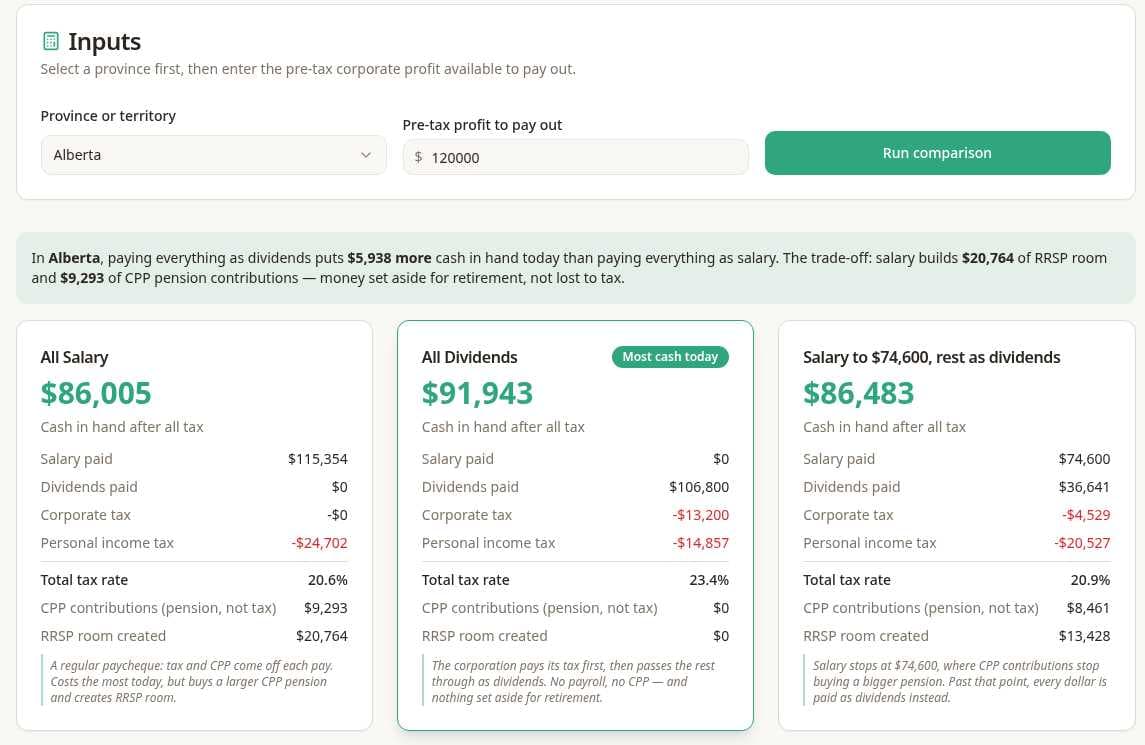
Every year I end up arguing with myself about how to pull money out of my corporation, and every year I kind of wing it. So I finally built a salary vs dividend calculator into Budgey: https://www.budgey.ca/salary-vs-dividend You pick your province, enter the pre-tax profit you want to pay out, and it lines up all salary, all dividends, and a mix where salary stops at $74,600 and the rest comes out as dividends. Here's $120,000 of profit in Alberta. All dividends leaves the most cash in hand, $91,943. The corp pays $13,200 of tax first, then $14,857 of personal tax on the $106,800 of dividends. All salary leaves $86,005. That's $5,938 less, but it creates $20,764 of RRSP room and $9,293 of CPP contributions. Dividends create zero of either. The mix comes out to $86,483 in hand, $13,428 of RRSP room and $8,461 of CPP. The $74,600 isn't random. It's where CPP stops buying you a bigger pension, so past that point I have it pay everything as dividends. I also made a point of showing CPP as pension money, not tax, because that's what it is, even if it doesn't feel like it on payday. So the "dividends win" answer really depends on whether you'd actually invest that RRSP room, and how much you value the CPP pension down the road. It also doesn't decide how much to take out in the first place. Whatever you don't need can stay in the corp and defer the personal tax. Curious what everyone does with their own corp. Straight dividends, salary to $74,600, or something else? And if you try it, let me know what you'd want added.
110 views
1 Comments
John
@cruzzer · 11m
I pay myself myself dividends. I have no interest in doing RRSP. The tax burden later is enormous.
See the full comment section 👀Sign up for the full Blossom experience!