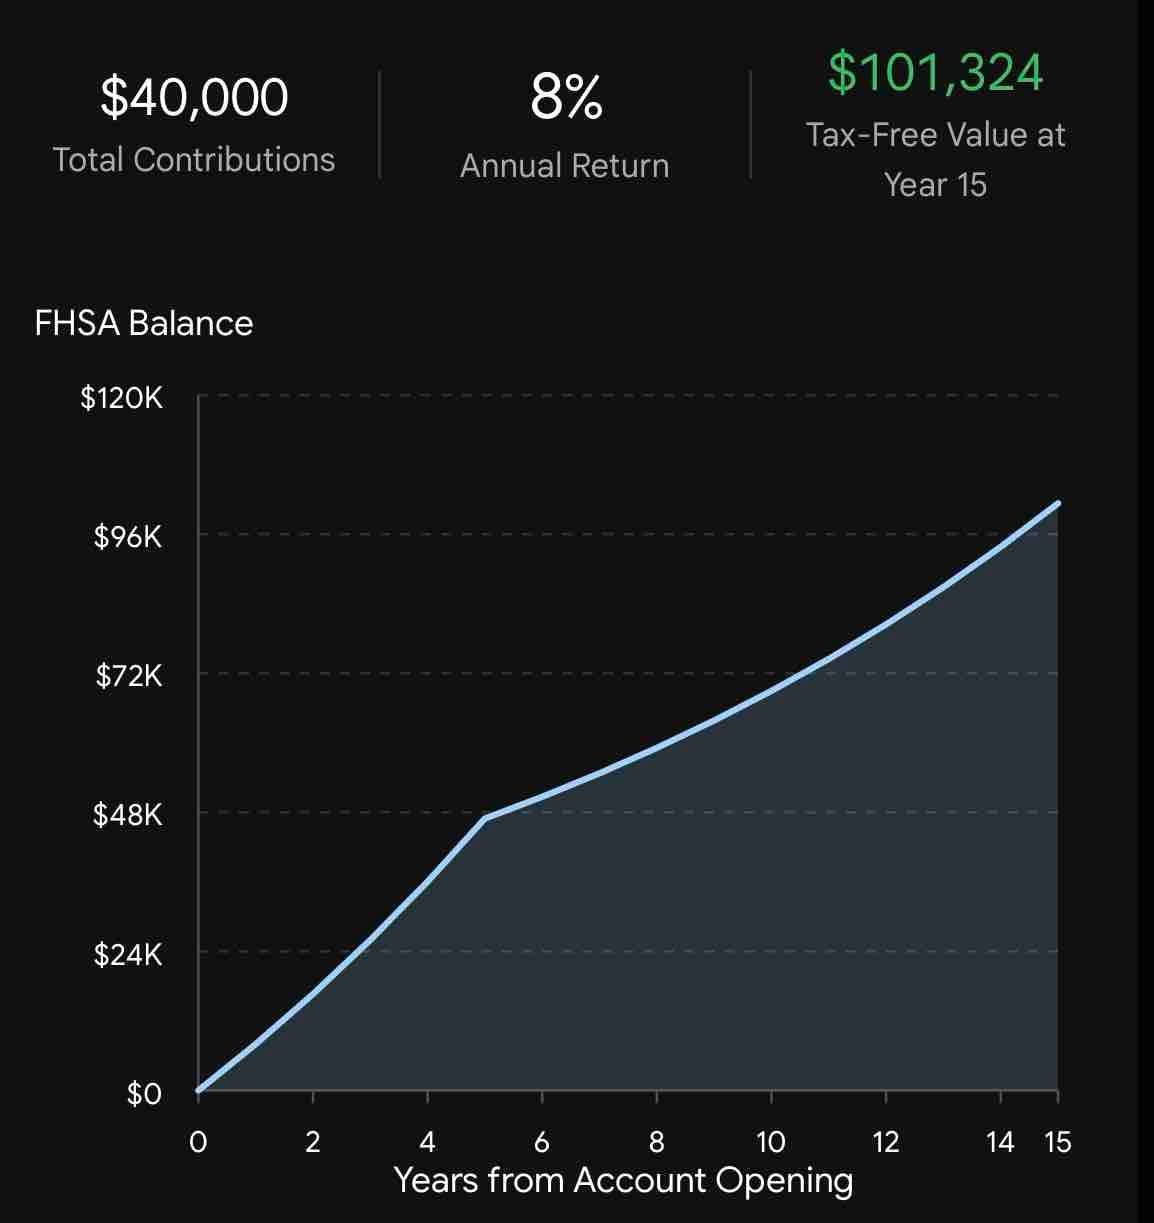
The FHSA is one of the most powerful account in Canada right now. Even if you don't plan on buying a home immediately, the math is undeniable. 🧵 You get $8,000 in contribution room per year (up to a $40,000 lifetime limit). Like an RRSP, it lowers your taxable income. Like a TFSA, it grows completely tax-free. Imagine you are 22. You max out $8,000 a year for 5 years. You get a tax deduction every single year. Then you stop contributing. You let that $40,000 compound at 8% for 10 more years. By the time you are 37, you have roughly $100,000 sitting there completely tax-free for a down payment. 💡High earner loophole: If you already maxed out your RRSP, open an FHSA just for the extra $8,000 annual tax deduction. If you decide to never buy a house, you can roll it directly into your RRSP later without using up any of your existing RRSP contribution room.
2,030 views
8 Comments
Carlos L@retirement_rants · 17d
Absolutely 💯 percent Setting up both my kids for this It really is a no brainer for anyone starting out
Retired
@retired · 17d
Such a great tool to build wealth as a Canadian 👌🏻
Nomer
@nomer · 17d
You also missed the first 5 yrs growth of the acct, the first dollar you invested in FHSA starts to grow. In my case, my last year of contribution (5th year) will be 2027, but my money by that time is not 40k but minimum 55k including the principal 40k and 15k growth.
Nomer
@nomer · 17d
I think the best usage for FHSA are tax deductions-tax free growth-tax free withdrawal for buying your first home, and unlike home-buyers plan in RRSP you don’t need to pay it back
See the full comment section 👀Sign up for the full Blossom experience!