The $4.1M TFSA Roadmap, Tax-Free Wealth 📈
Calling the TFSA a savings account is a massive branding mistake.
Stashing cash or GICs inside wastes Canada's best wealth-building tool.
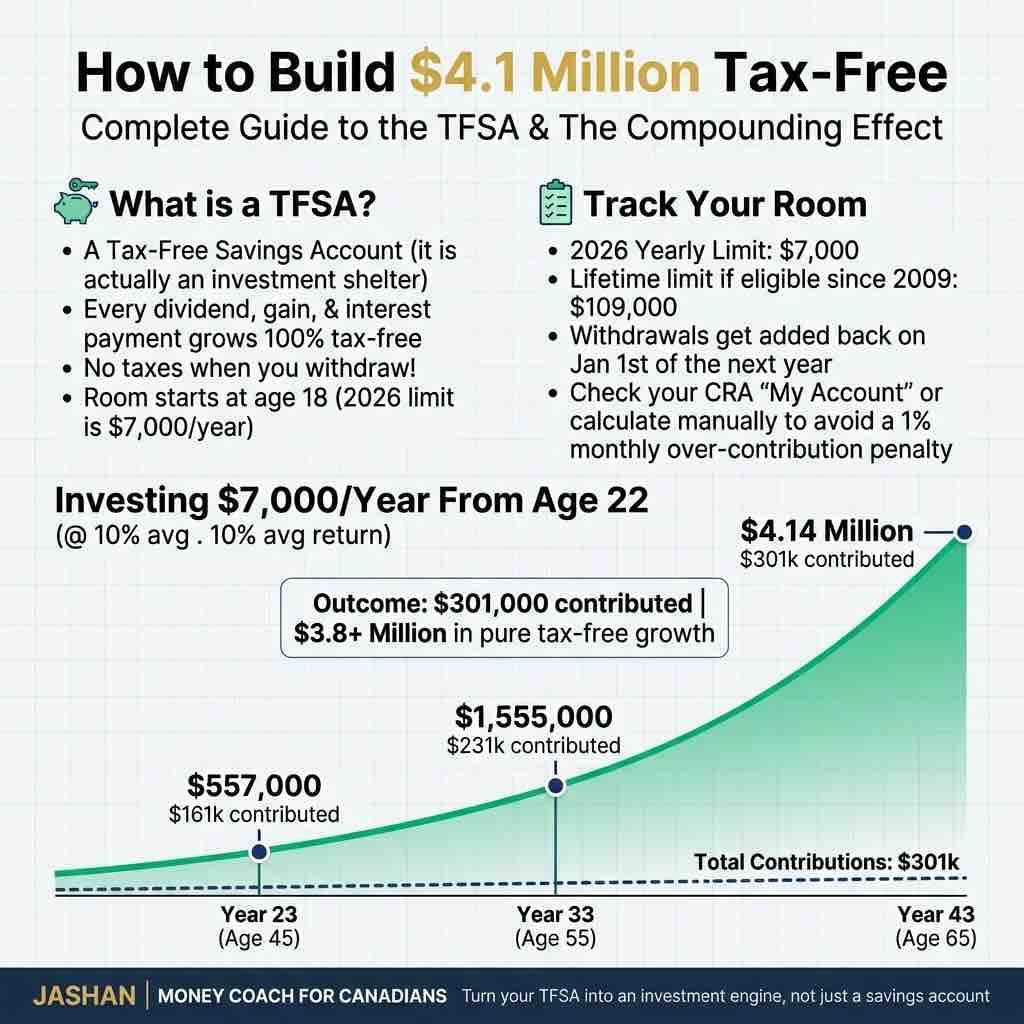
A TFSA is a tax shelter. Every dollar of capital gains, dividends, and interest compounds 100% tax-free.
When you withdraw, the CRA takes zero tax.
Withdrawals also do not count as taxable income, so they will never claw back your OAS or government benefits in retirement.
🛑 The 2026 Rules
• The annual contribution limit is $7,000.
• The lifetime cumulative room is $109,000 if you have been eligible since 2009.
• Contribution room starts accumulating automatically the year you turn 18.
• Any money you withdraw is added back to your contribution room on January 1st of the following calendar year.
Warning: Financial institutions tend to report contributions late in the spring. Your CRA portal lags until May, so track deposits manually to avoid the 1% per month over-contribution penalty.
🚀 The 43-Year Compounding Curve
If a 22-year-old graduate invests $7,000 per year into low-cost, broad-market index funds averaging a 10% annual return:
• By Age 45 (Year 23), you have contributed $161,000 and the portfolio sits at roughly $557,000.
• By Age 55 (Year 33), you have contributed $231,000 and the portfolio crosses $1.56 Million.
• By Age 65 (Year 43), you have contributed $301,000 and the portfolio reaches over $4.14 Million.
You put in $301,000 of your own money.
The remaining $3.8+ million is pure, tax-free market growth that the CRA cannot touch.
🎯 The Action Plan
First, keep emergency cash in a high-yield savings account.
Second, use your TFSA as a tax-free wealth building engine.
Third, automate monthly contributions into broad-market index funds.
Fourth, track your room manually to steer clear of CRA penalties.