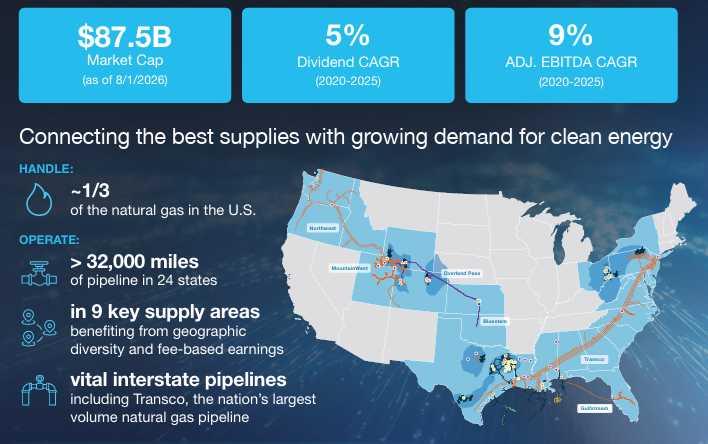
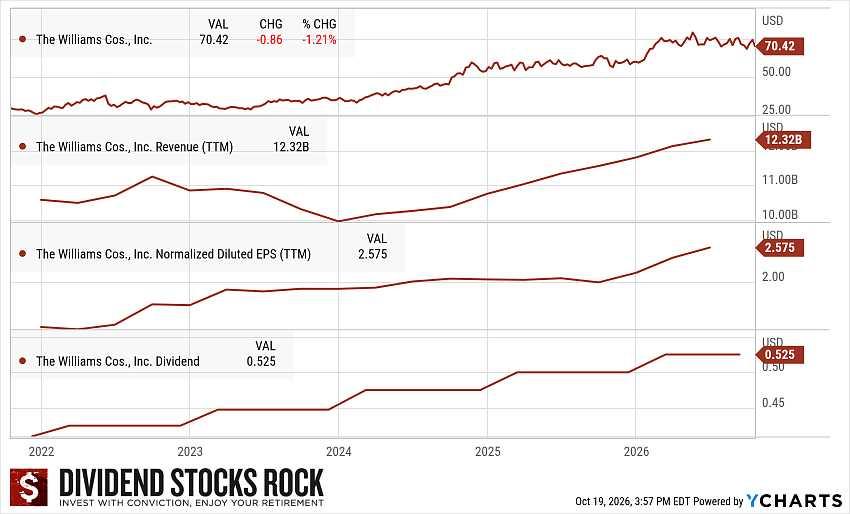
Most pipelines lost 10% or more from their summer highs. Williams fell 12%. Nothing broke inside the company. It raised its guidance for the year. Williams owns Transco, the largest interstate natural gas pipeline in the U.S. It runs from South Texas to New York City and now flows both ways. It links the cheapest gas in North America to the fastest-growing demand on the East Coast. Morningstar rates Transco as a wide-moat asset inside a narrow-moat company. The newer piece is power. Williams built a 200-megawatt gas plant for a data center in Ohio in under 18 months. It now has six of these deals, worth US$9.6 billion, on 10 to 12.5-year contracts. The dividend triangle: Management targets EBITDA growth of 11% or more over the long term. The dividend grew about 5% a year over five years, with another 5% increase in 2026. In 2025, cash flow covered the dividend 2.4 times. That leaves room to keep raising it while funding growth. The yield is 3.0%, below its five-year average of 4.7%. A yield above its average can flag a buying opportunity. Here it is the opposite. Even after the drop, the market prices Williams above its own history. What could go wrong: the Momentum acquisition pushes debt above the 4 times EBITDA ceiling management prefers, for now. Gathering and processing moves with drilling. And Williams is a pure natural gas company. If the power and LNG demand wave stalls, there is no other business to lean on. Full article: https://thedividendguyblog.com/williams-vs-oneok-two-u-s-pipelines-one-dividend-growth-winner/ Would you pay up for a pipe nobody can copy? I don't own Williams. Education, not advice.
388 views
0 Comments
No comments available.
Join the conversation with 500,000+ other investors 💸
Create an account to get access to everything Blossom has to offer!
📊 Personalized algorithm based on your investing style, experience level and interests
📈 Powerful portfolio and dividend tracking tools
👀 See what top creators and others in the community are investing in