Very excited to unveil a massive algo update which will drive huge improvements to the Blossom experience, incorporating the amazing feedback you guys shared 🫡 @kartik and I will be hosting a live on Sep 23 after the changes go live (targeting Sep 21)! Tune in if you can as we’ll have live Q&A 😊 https://www.addevent.com/event/zzkt1bv4zbsm ✨ A few cool new features to unveil as well 👀
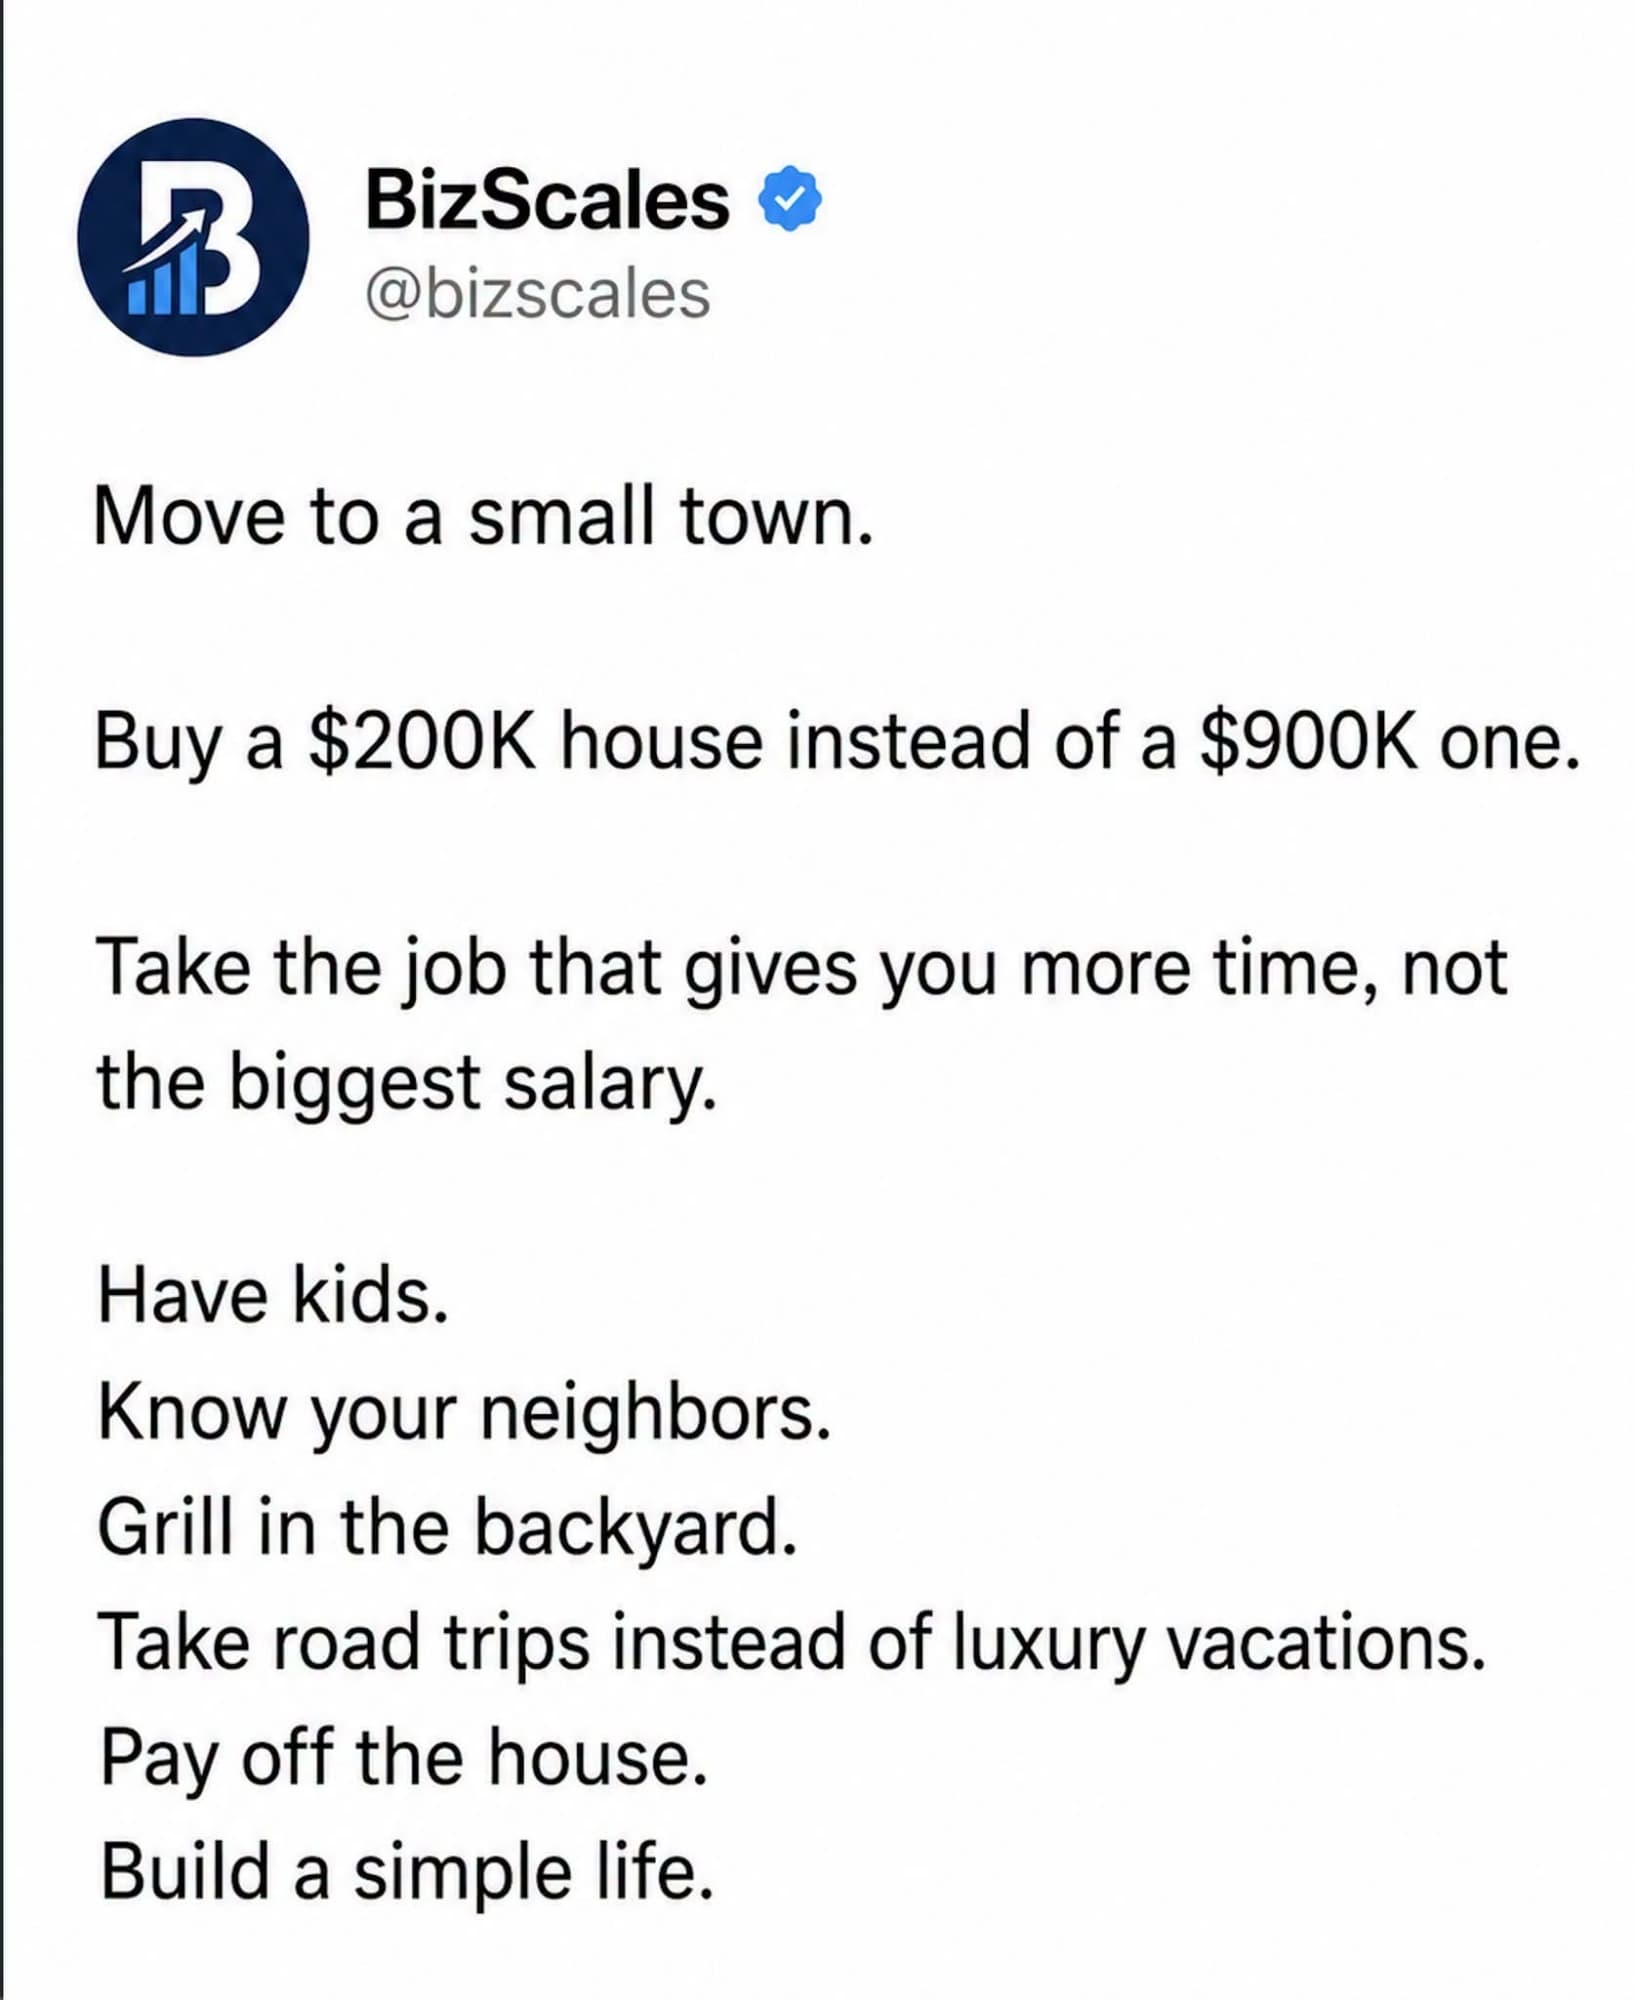
Saw someone posted this and thought...this is exactly how my wife and I have lived for the past 8 or so years since we been married.. The only difference is our house was 345k and we fly to places more than we drive. Other than that it describes us to a T. We live in small town Sask, know all our neighbours, take each other's trash out, everyone puts up Christmas lights and decorations during winter, kids roam freely, zero traffic, I walk to work, summer fire in our big yard with friends, strangers wave at you when you drive by...all while stacking our investments. Living the simplier life is so good...
Every day there's another headline about how AI is going to kill us all... with Sam Altman recently delaying the OpenAI IPO and implying that AI has a 10% chance of killing everyone by the end of the decade. Every time I see this kind of stuff I somewhat wonder how much of it is a real risk vs a marketing play to pump the stock... One Bloomberg opinion piece calls it "AI Panic Marketing": basically the message that "we're building a powerful, godlike AI that could end the world" is a form of advertising. On the other side, more than 1,000 employees across the frontier labs signed a letter this summer warning that competitive pressure was preventing anyone from slowing down, so I'm not really sure what side I'm on What do you guys think?
I wanted to wait until the end of the year to post this, but I’m too excited today. I reached the 50K portfolio goal,I set for myself for 2026! 🎉 What you don’t see behind this number is everything that happened this year. I got laid off, went through multiple interviews, landed a new job, and ultimately moved back in with my family because the commute from where I lived was just too much. Everything changed at once, and I’ll be honest, some days it’s been really hard to even get out of bed with the anxiety and depression that came with all the uncertainty. As a single-income person in my 30s, it’s been tough. Moving home has sometimes felt like I’m taking steps backwards, but I’m trying to see it as an opportunity to stabilize, save aggressively, and build toward my future. Five years ago, I didn’t understand ETFs or investing. I learned through Blossom, countless YouTube videos, and of course @joyeeyang my go-to is XEQT btw! For anyone just starting out, or feeling like they started later than they should have, remember: everyone is on their own journey. You don’t see the layoffs, sacrifices, family situations, setbacks, and adjustments behind someone’s portfolio. If you’re showing up and investing whatever you can, that is enough. ❤️ I’m usually so focused on what’s next that I forget to acknowledge how far I’ve come. So today, I’m letting myself be proud. $50K. Next chapter: Road to $100K.🚀 read more
Some people invest to quit their job Some for retirement Some for a better life! This is the only reason I invest Some people laughed at me and others said it couldn’t be done But who’s laughing now!! Suck it DQ, suck it McDonalds! Suck it Baskin Robbins! I no longer have to rely on the system for my Ice cream! Dreams do come true when you’re patient and work hard Thank you $VFV Thank you $XEQT Thank you blossom community for believing in me! read more
I’ve gotten to know a bunch of you through Blossom events, messages, and just being around the community, but I realized I’ve never actually shared much about myself or how I ended up here. For those I haven’t met yet, I’m Tim, I’m 20, and I work as an intern on the Brand Partnerships team here at Blossom. My journey here has been a pretty unconventional one. Growing up, my entire world was gaming. I started playing Fortnite competitively at a pretty young age, eventually playing professionally and getting signed to some of the biggest organizations in esports, including Overtime. Then, before high school, I decided to walk away from it. I had spent so much of my childhood behind a computer that I wanted to experience a completely different side of life. Somewhere along the way, I fell in love with business. From flipping cars, to running Amazon FBA, to starting and eventually selling a landscaping business, I was constantly trying something new. Some things worked, a lot didn’t, but I loved figuring out how to build something from nothing. That same curiosity eventually led me to investing. I became fascinated by the businesses behind the stocks. How they made money, why some companies won while others didn’t, and ultimately where I wanted to put my own money. That interest eventually led me into finance and most recently private equity. For a while, I thought I’d stay on the traditional finance path. Then I joined Blossom. It was a completely different direction, but looking back, it brought together pretty much everything I loved: investing, entrepreneurship, technology, and building. And it’s genuinely been some of the most fun I’ve ever had. I’ve gotten to work on things I never expected to be doing at 20, travel across the country for BlossomCon, and learn firsthand what it takes to build a company. But easily the best part has been the people. Working alongside @tigertim , @maxstocks, @brandon , and the rest of the team has given me some of my favourite memories. Everyone here genuinely cares about what we’re building, moves insanely fast, and still manages to have a ton of fun doing it. The culture being built at Blossom is something really special, and I’m incredibly excited to see where we take it. I also want to hear from you guys. If there’s anything you love about Blossom, think we could do better, or want to see us build in the future, drop it below or shoot me a message. I’d genuinely love to hear it, and you’ll definitely be seeing more of me on here :)read more
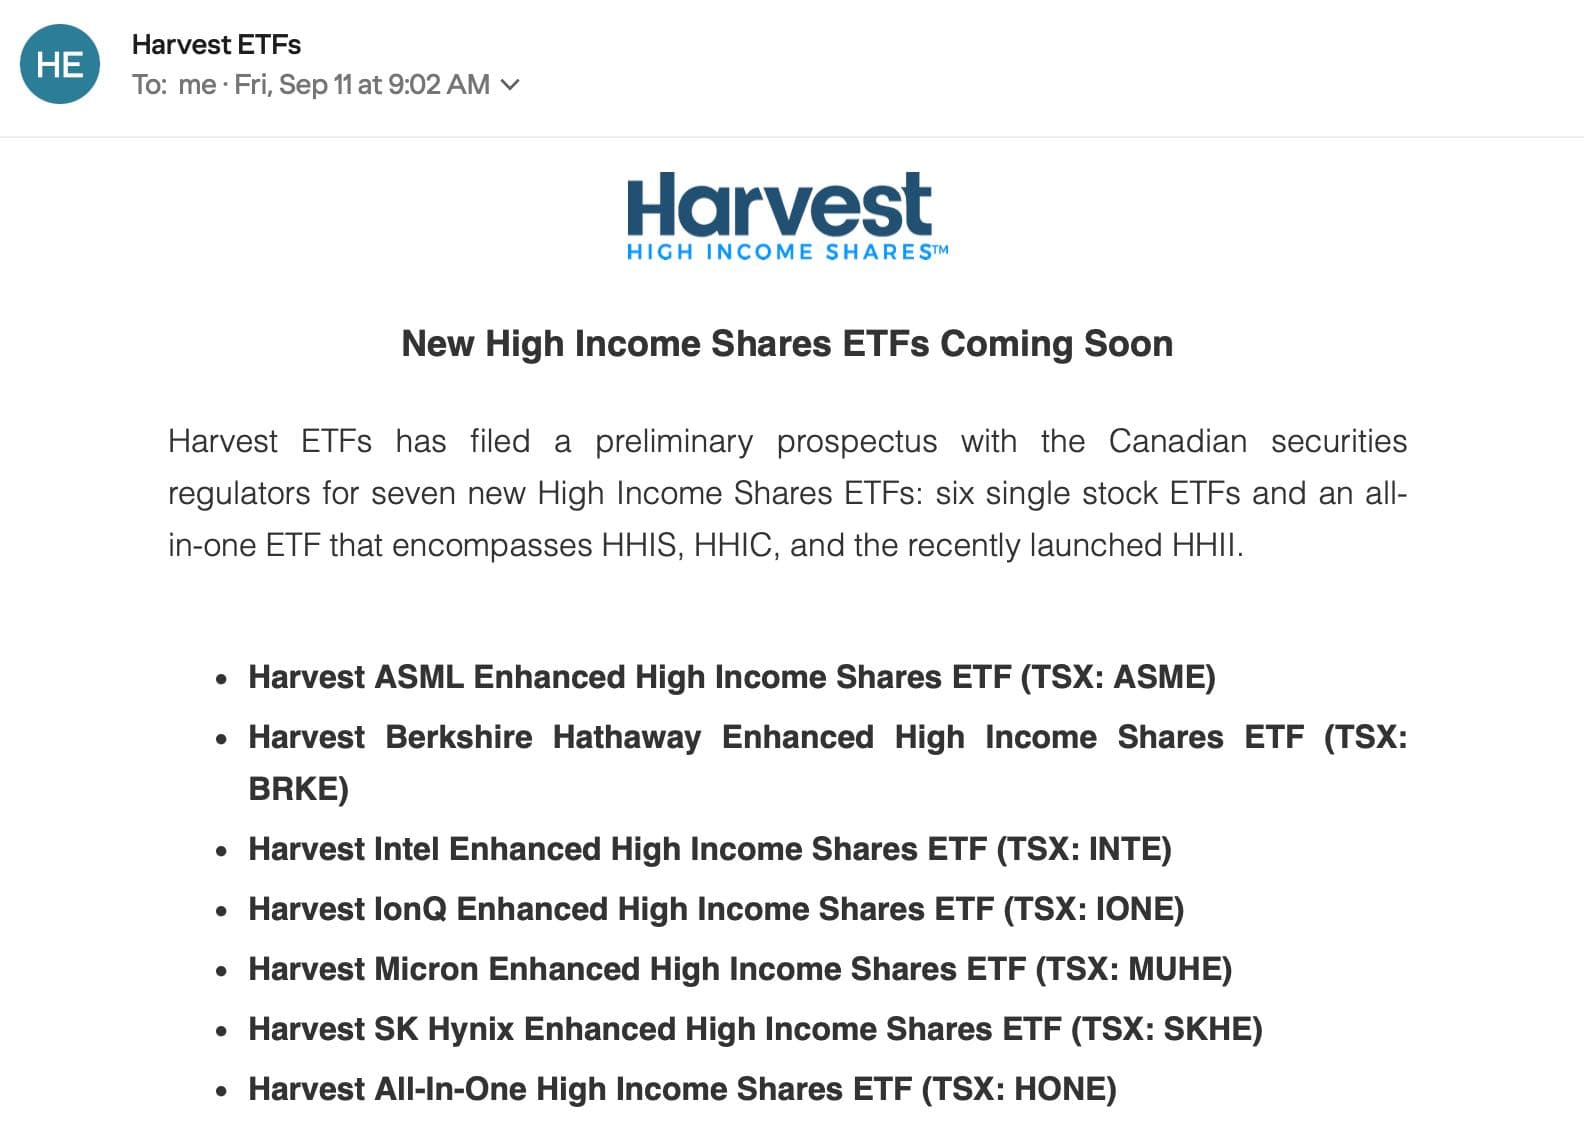
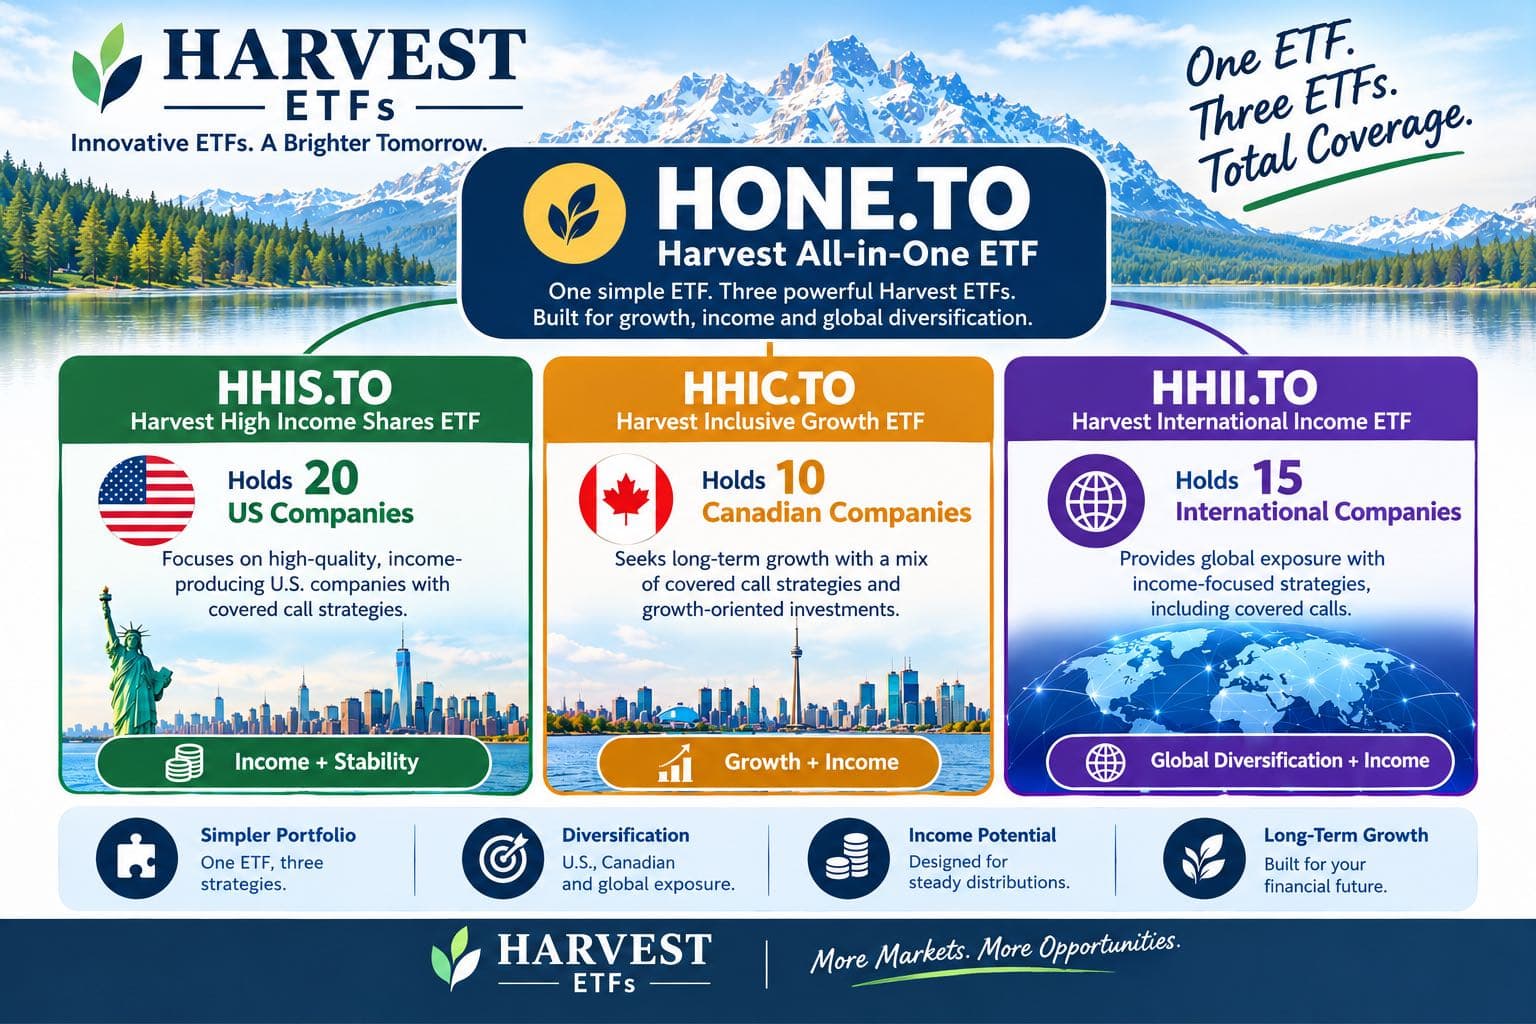
A BIG ANNOUNCEMENT from Harvest, and it looks like they will be releasing soon some new single stock ETFs and an all-in-one ETF of their very popular High Income Shares ETFs! 💥 Harvest ASML Enhanced High Income Shares ETF (ASME) Harvest Berkshire Hathaway Enhanced High Income Shares ETF (BRKE) Harvest Intel Enhanced High Income Shares ETF (INTE) Harvest IonQ Enhanced High Income Shares ETF (IONE) Harvest Micron Enhanced High Income Shares ETF (MUHE) Harvest SK Hynix Enhanced High Income Shares ETF (SKHE) .. and what you've been waiting for! Harvest All-In-One High Income Shares ETF (HONE) This will be what many passive income investors would be looking at, for a simple way to gain direct diversification in one ETF product. The initial holdings will include the following: - Harvest Canadian High Income Shares ETF (HHIC) - Harvest International High Income Shares ETF (HHII) - Harvest Diversified High Income Shares ETF (HHIS) There's no mention of what the allocations will be, but I would assume that HHIS would be the largest slice, followed by HHIC and then HHII. My random guess might be similar to BIGY where it'd be approximately 45% HHIS / 30% HHIC / 25% HHII? By bundling these all together, you would get a basket of 45 total holdings: - HHIC has 10 Holdings - HHII has 15 Holdings - HHIS has 20 Holdings Typically these are filed about a month before they finally start trading, so we can likely expect this to come out somewhere towards the end of October at the latest. ➡️ What would be your guess or desired allocations of the 3 ETFs? Comment down below! .read more
Almost 4 months into building my income portfolio and I have officially reached my goal of $1000 per month in distributions. This was intended to be a 6 month project but I’ve been working like a madman and I’ve reached my goal 2 months early. Now that I have reached my income goal I will be shifting my focus to growth. From this point on I will no longer be contributing to $HHIS & $BIGY, I will just hold my current position and do as I see fit with those distributions each month. I will also no longer be contributing to $HDIV$QDAY$CLSA$UTES$CMCL & $HBTE but leaving them on drip to let them snowball on autopilot. From this point moving forward all future contributions to my portfolio will be going directly into $XEQT for stable diversified long term growth on top of my solid income sleeve. I would love to hear your thoughts…
If you had $100,000 to invest for the next 20 years, would you rather: A) Build a dividend portfolio and collect income along the way B) Focus on growth stocks and worry about income later I personally lean more toward growth while I’m younger, but I can definitely see the appeal of building a portfolio that eventually pays you every month. What’s your choice? A or B? And why? $VOO$SCHDread more
After years of saying I would never buy bitcoin and a single stock etf I have made the move. This does not mean the flood gates are opening up in this regard. Giving myself some exposure where I think it makes sense. https://youtu.be/29Cc7VVgPdo?si=fi5vHkdP4EBPbj7g
What is actually considered a “pretty damn good” investment return? And if you’re earning 20%, 30% or even 40%+ in yield, should you really expect that to continue? Welcome back to Financial KarMoe Episode 19, where @karyungtom and Moe tackle another round of investing, personal finance and FIRE questions from the Blossom community. This episode goes deep into what a reasonable long-term investment return might look like, why comparing investment strategies isn’t always as simple as comparing two numbers, and why a high distribution or yield doesn’t automatically mean a higher total return. 📈 We start by discussing the idea of a “good” return and why expected returns need to be viewed in the context of risk. We also talk about high-yield strategies, covered-call ETFs, market demand and why investors should be careful about anchoring their expectations to unusually high returns. 📊 We then get into what you should actually compare your investment to? Kar explains why comparing two investments can be useful when you’re trying to isolate the reason for a performance difference—but much less useful when the investments have completely different strategies, levels of leverage or objectives. We also tackle a question from a new investor who wants to understand what to do with a non-registered account. We discuss capital gains, Canadian dividends, interest income, tax-loss harvesting, asset location and the trade-off between optimizing every last tax dollar versus keeping your investment strategy simple. 🌎 And yes… we talk about XEQT again. 😆 Both of us explain why we’re comfortable with the simplicity of using a broadly diversified all-equity ETF across accounts, while also discussing how investors with larger portfolios might choose to get more sophisticated with asset location. 🏖️ Then we shift into an important FIRE question: What happens when you stop accumulating and start spending? Would we still hold 100% XEQT or equivalent all-equity exposure in retirement? We discuss cash wedges, bonds, sequence-of-returns risk, withdrawals, distributions and why the “right” portfolio may depend heavily on the size of your portfolio and your retirement timeline. 🚗 We also answer some very non-investing questions—including whether it makes sense to buy a new versus used vehicle, whether a $100,000 car is reasonable if it represents only 5% of your net worth, and whether leasing a newer vehicle can ever be justified as a lifestyle choice. 🤓 We even tackle the question: “At what point can you stop calling yourself a beginner investor?” 💡 Finally, we discuss whether investors should try to time the market, the role of portfolio lines of credit and borrowing to invest, and why you should NEVER blindly copy another investor’s strategy. Your income, expenses, emergency reserves, job stability, family situation, risk tolerance and financial goals can all change the answer. And we finish with an important message about investing disagreements: you can disagree with someone’s strategy without thinking they’re an idiot. Different investors can have different goals, timelines and expectations—and that’s part of what makes markets work. https://youtu.be/UzNkFYu9xnoread more
I see alot of lazy list on blossom. typicall it looks like this.... $QDAY .25 $SDAY 1.45 $CDAY 4.50 $BIGY 11.11 $ULTY 2.72 $MSTY .70 $HYLD 1.87 $HDIV 19.22 $QDTE 9.30 ......The list goes on! What did you add? Why only show the distributions? How does showing only one side of the picture help others make up there mind in an investing process? I have all these questions that really boil down to 1 thing. hype. This platform lets you slam a bunch of popular tags on a post that adds basically nothing to the conversation. If investing in yield products solved investing that would have happend already years ago. Instead of posting this why not a comprehensive show if total returns and how distributions landed you with a solid alpha? Because that take alot of effort, instead.... lists.read more
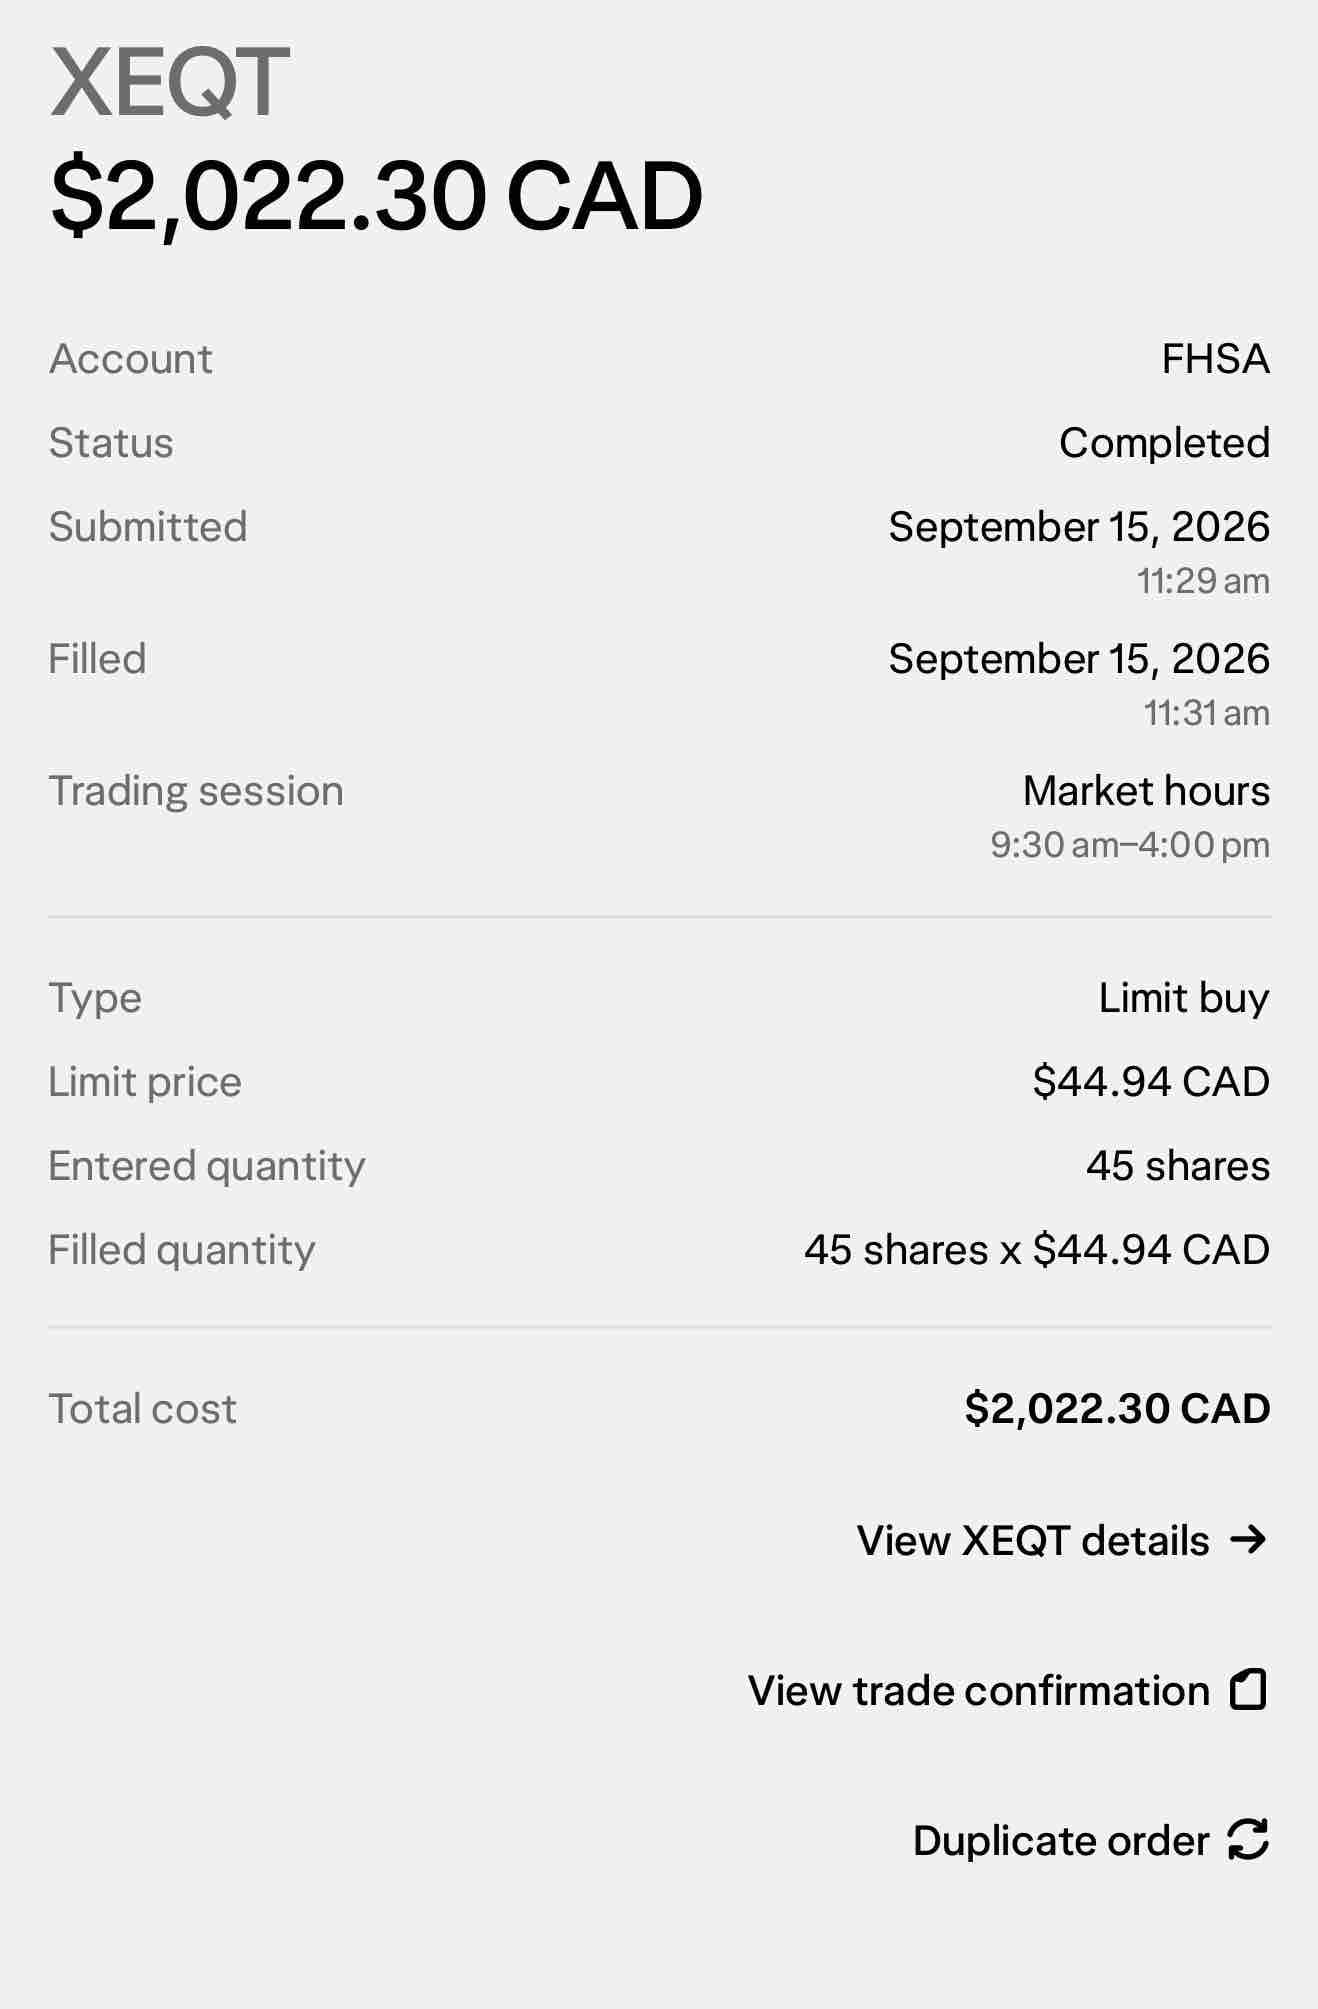
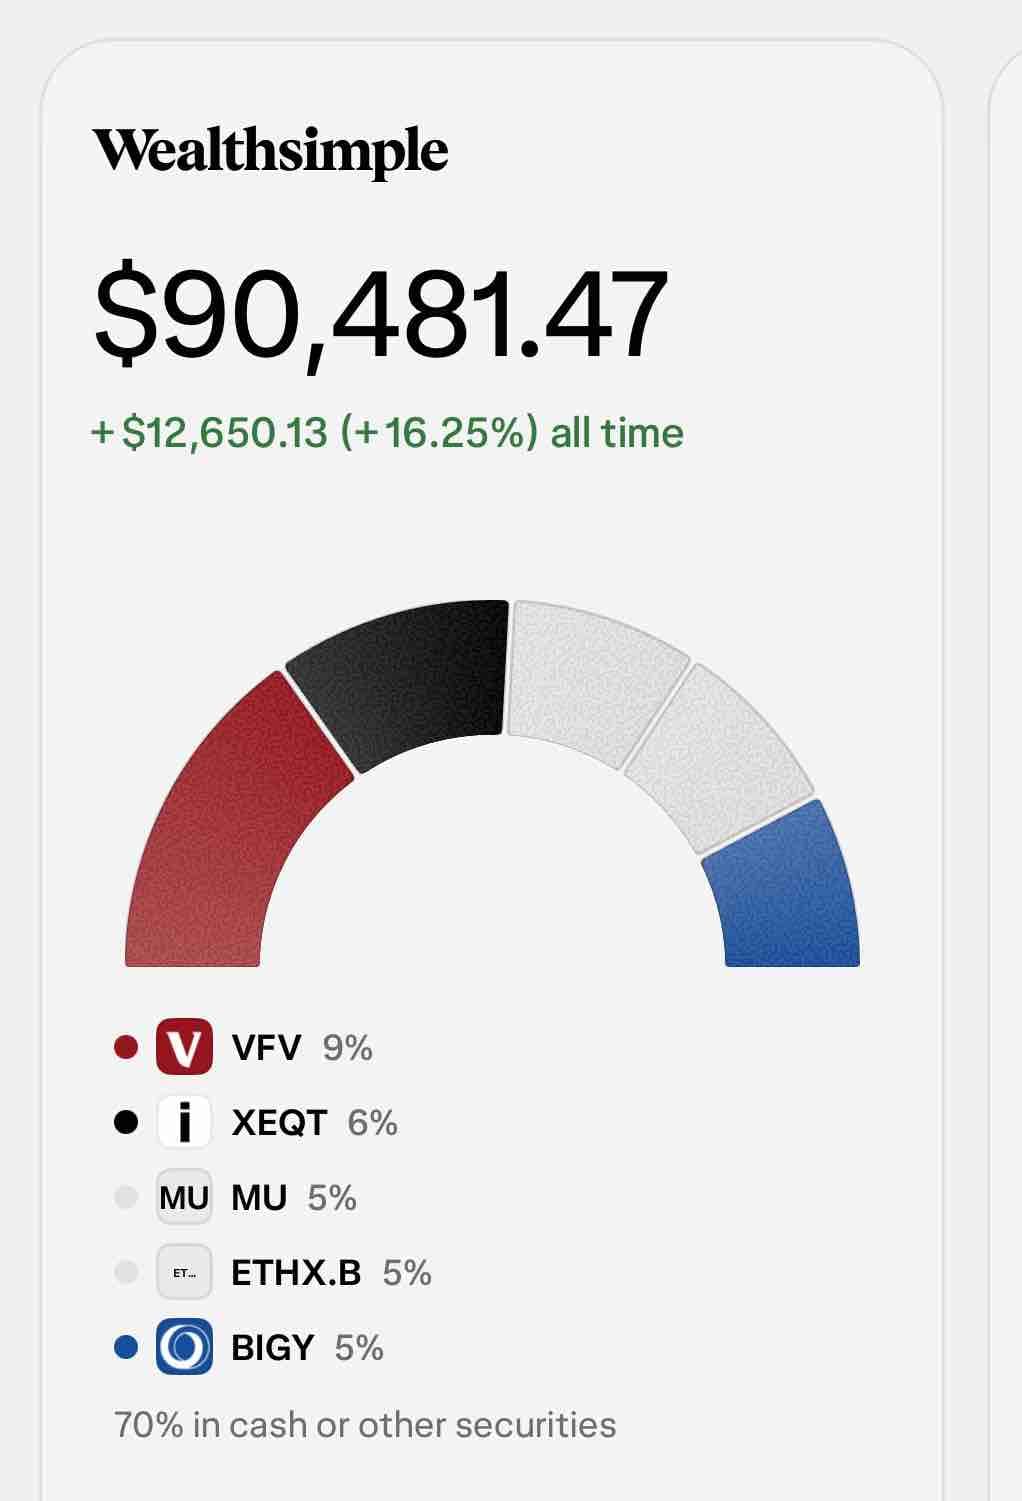
Today I reached 90k in investments 🥹 I still can’t believe it. Maxed out my TFSA contribution room for the year. Bought some $XEQT in FHSA today🔥 Excited to see how it goes. I want to reach 100k so that I can peacefully gift my wife a car 🚗 we have lived our lives without a car in Canada so far 😭 $VFV$MU$AMZN$VDYread more
Building the 50 year TFSA For me, the TFSA is the most coveted account. The contribution room is SACRED. I was obsessed with maxing it out as fast as possible to let compounding do its magic. Optimizing it has been my most recent priority. My goal with the TFSA is to be a buy and hold for 30+ years. Something I hopefully won’t touch until later in retirement. Make one ~$7000 contribution + buys per year, probably all into $VEQT . Then not look at the account again until the next year. With optimal long term total returns. The kind of thing a lot of people find a solution within a simple all in one fund like $XEQT. I love low cost passive indexing and am a true believer. But for me, it’s not quite enough. I personally believe: -In a Tech tilted future -In Bitcoin -25-30% home bias is kind of BS E.g. Do I believe in 30 years the Nasdaq 100 will outperform an all-in-one fund? Yes. Will it be a choppy ride? Also Yes. 8 months ago I said goodbye to individual stocks in my TFSA: https://www.blossomsocial.com/posts/Its-finally-done-TFSA-is-percent-ETFs__POST-1767812921730-ww8KVMzA_nAUaQLqSRtwRiLHr Today I took another big step forward with this in my TFSA refactor. I said goodbye to 4 holdings: $XIC $VFV $XEF $XEC And hello to: $VEQT I also trimmed over 1/3rd of $SOXX. Lastly I trimmed some $QQQM for some $VOO. This may seem like small moves, but it took a lot of thinking for me to pull the triggers. As usual, I’ve spent way too many hours thinking about my portfolio construction. I liked the lower fees and having the granular control over a decomposed all-in-one equity ETF. Where I subbed US all market cap for SP500 (VFV), and had modified allocations to Canada (XIC), and International (XEF, XEC). Ironically, I chose $VEQT as my all in one fund because it is heavier on the Canadian side (~30%). Overall the TFSA breaks down as: 69% Equities ($VEQT, $QQQM, $VOO, $SOXX) 28% Bitcoin ($IBIT , $FBTC) 3% Gold ($ZGLD) There is only really one more move left to make: completely get rid of $SOXX. I love the thematic tilt, but it simply does not pass the 30 year buy and hold test. I am still working on the plan to reallocate this semiconductor exposure partially into my other accounts. Cheers 🍻read more