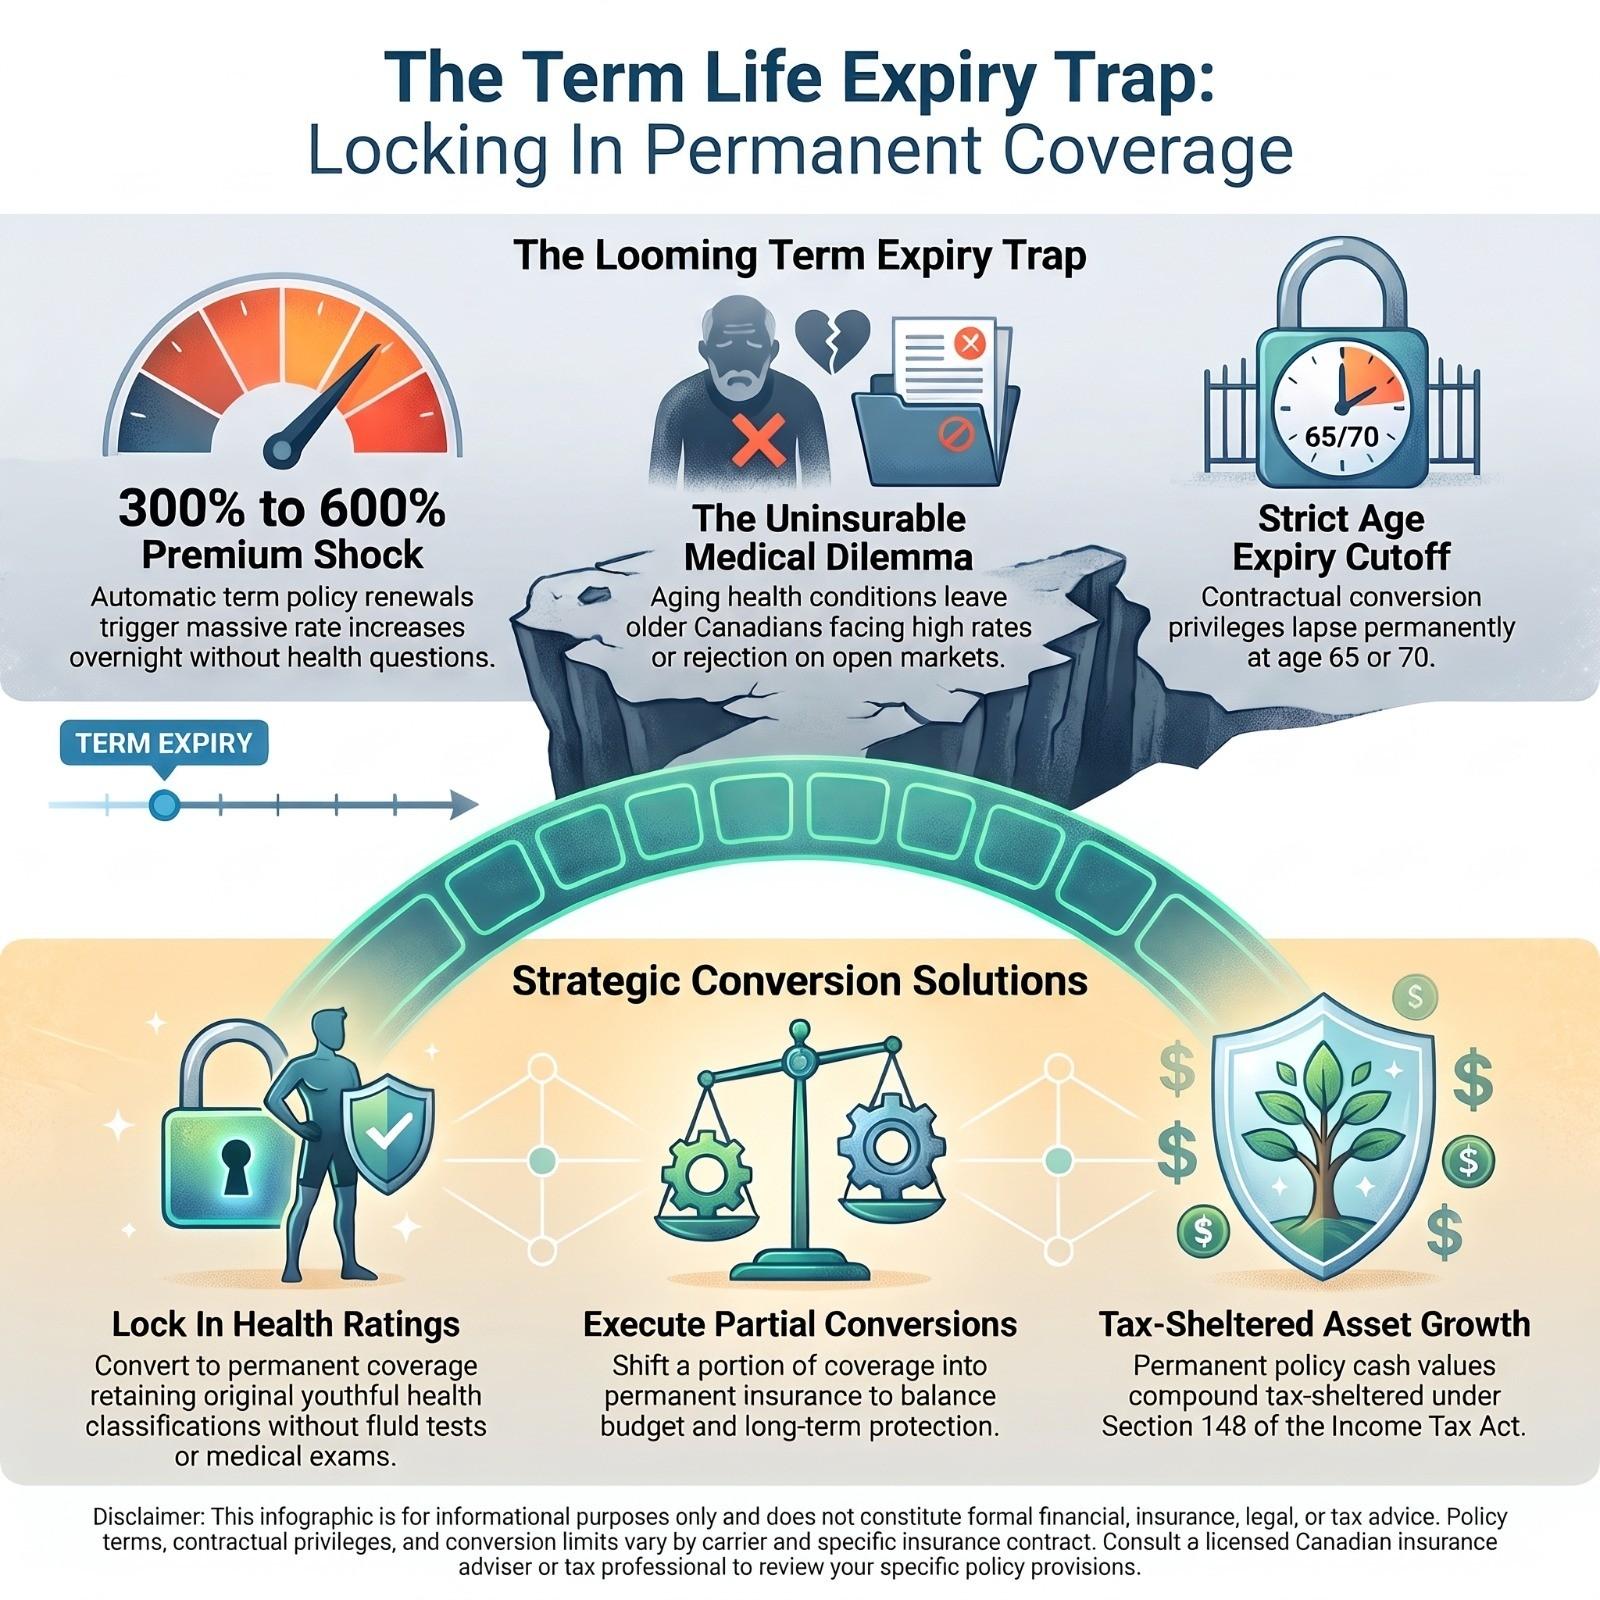
🚨 Got a 10- or 20-year Term Life insurance policy in Canada? Watch out for the "Renewal Price Shock." When your term life policy reaches the end of its initial term, your premiums can skyrocket by 300% to 600% OVERNIGHT. Most Canadians make a critical mistake here: they cancel the policy because it’s too expensive, or they try to apply for a new one—only to get hit with high rates or rejected because of health changes like blood pressure, cholesterol, diabetes, or weight. Here is the secret insurance companies don't advertise: The Guaranteed Conversion Privilege. Almost every Canadian term policy has a clause that legally allows you to convert your expiring term insurance into a Permanent Policy (Whole Life or Universal Life): ✅ ZERO medical exams (no needles, nurses, or doctor reports). ✅ ZERO health questions (even if you had a heart issue or cancer diagnosis). ✅ You keep the original healthy rating you had years ago! ✅ You lock in lifelong coverage that never expires and builds tax-free cash value under Section 148 of the Income Tax Act. ⚠️ THE CATCH: This right expires at age 65 or 70. If you miss the deadline, it is gone forever. Here are 5 Actionable Moves to protect your family's coverage: 1️⃣ Check your policy schedule for your conversion deadline today. 2️⃣ Consider a partial conversion (e.g., convert $250k of a $1M policy) to keep premiums manageable. 3️⃣ Lock in your youthful health class for life. 4️⃣ Choose between Whole Life (guaranteed dividends) or Universal Life (flexible indexing). 5️⃣ Corporate owners: Use permanent conversions to fund tax-free estate payouts via the CDA! Read through for the complete guide to converting term life insurance in Canada. 👉 How many years do you have left on your term life policy? Drop your thoughts or questions below! #LifeInsuranceCanada #FinancialLiteracyMonth #TermLifeInsurance #WholeLifeInsurance #UniversalLife #InsuranceConversion #EstatePlanningCanada #PersonalFinanceCanada #CanadianHomeowners #WealthProtection
162 views
1 Comments
Michael Noël
@therev · 16d
The best solution is don’t buy term unless you are investing enough to be self-insured when it runs out.
See the full comment section 👀Sign up for the full Blossom experience!