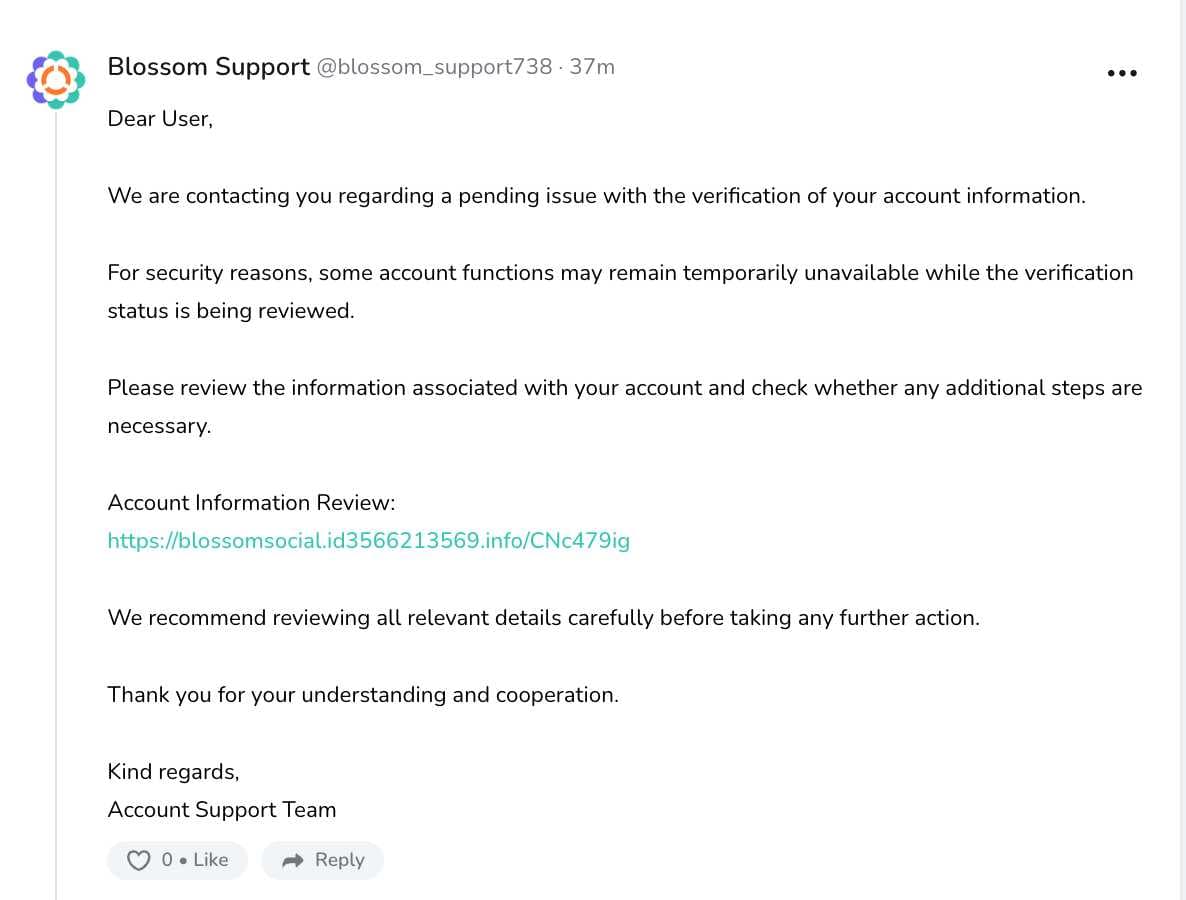
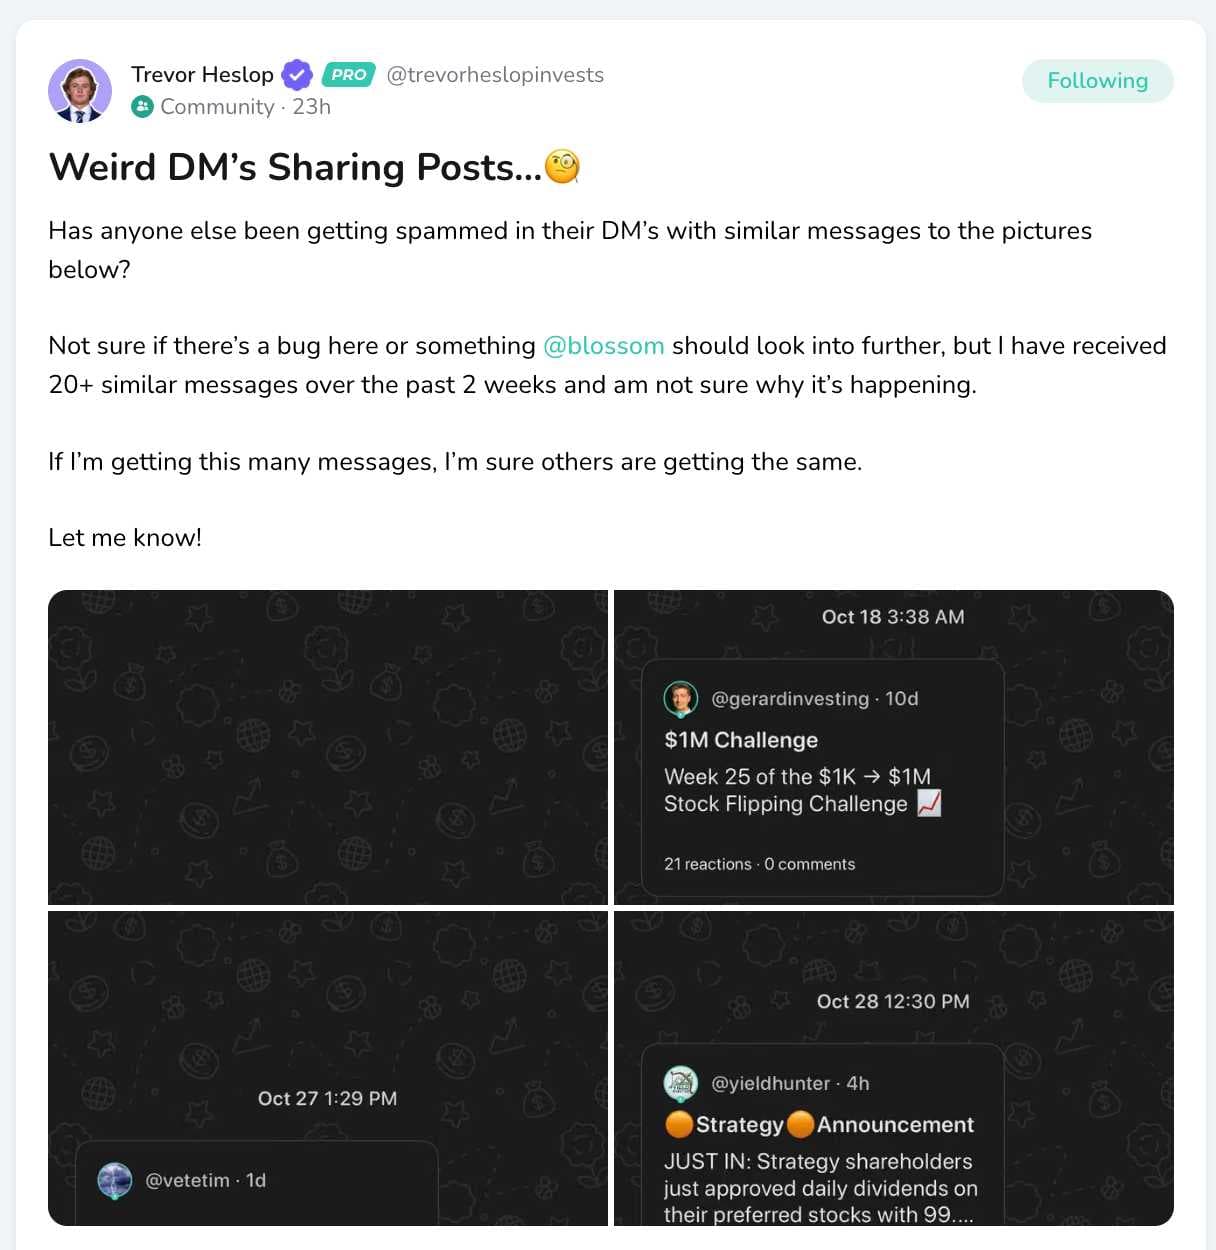
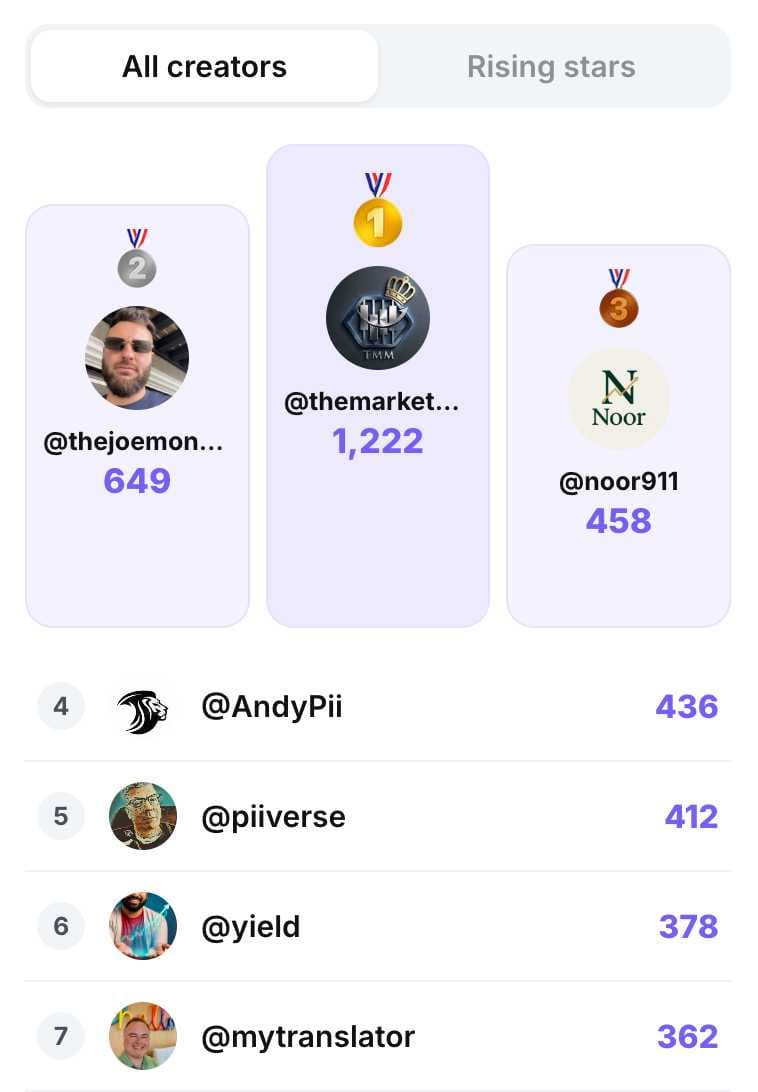
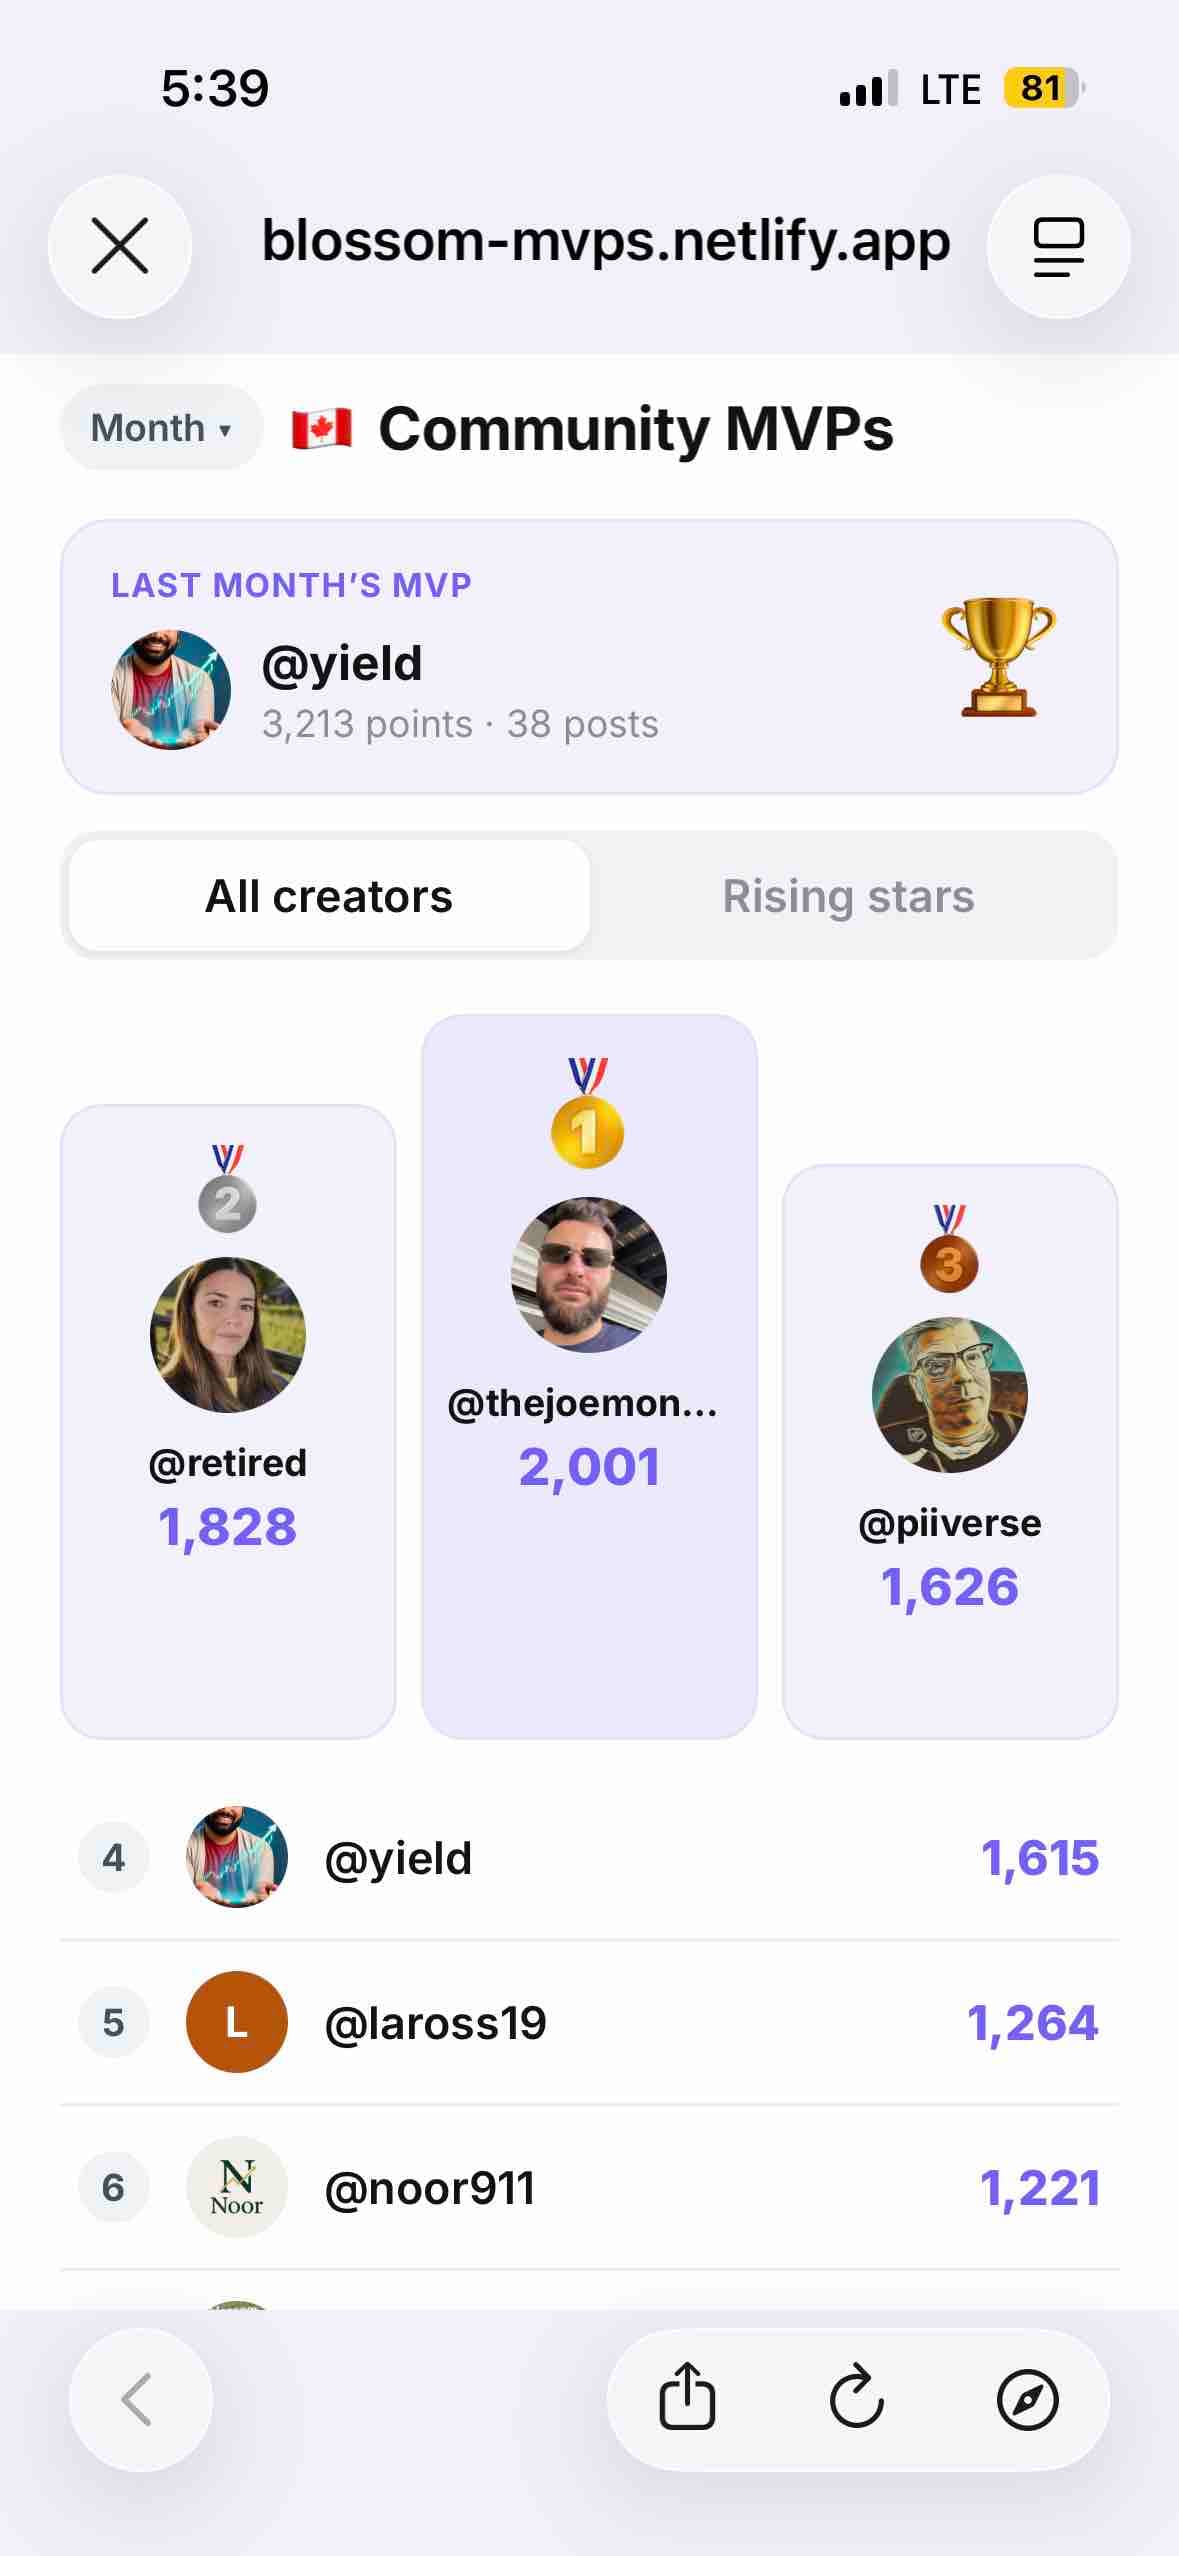
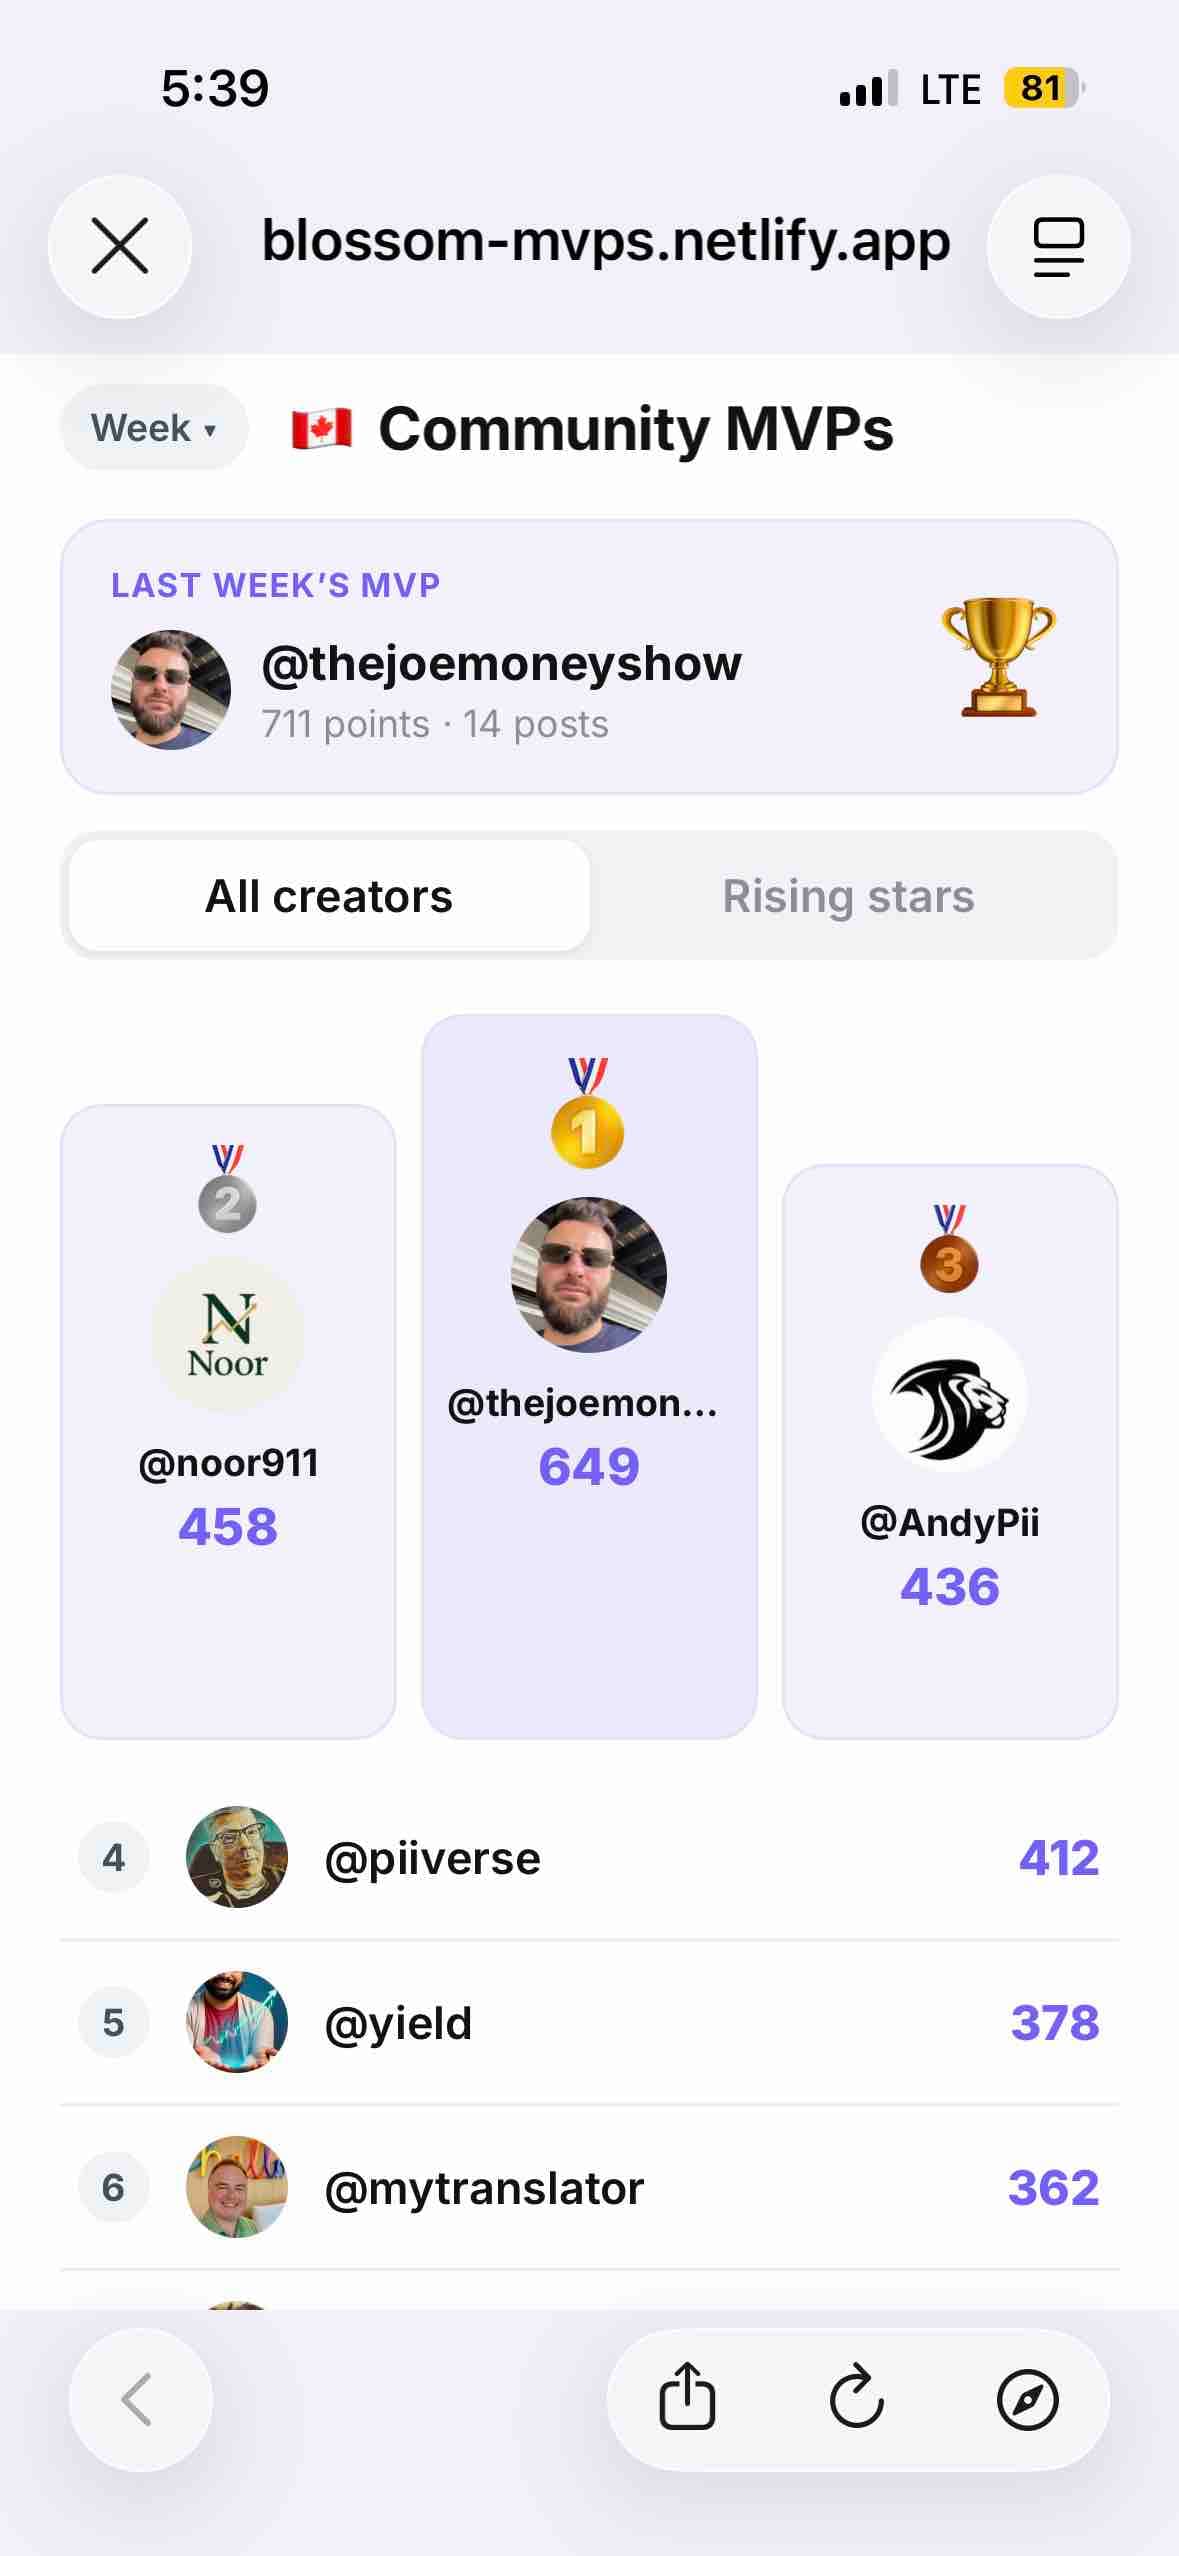
Quick flag that if you receive a dm or see a comment from 'Blossom support' it is a SCAM! Please report it and our customer support team will delete it and we're working on a fix to block these proactively which will be live tomorrow Re. @trevorheslopinvests's post "weird dms sharing posts" - this is actually not a scam, but was the result of when you long press the share button it sends a post (a bug on our end). The fix for this is now live when you update Blossom on the app store (thanks everyone for flagging this)! 😎 In addition to these fixes, lots of other cool updates on the way that I can't wait to share with you all! As a sneak peak here's the mock-up for a community leaderboard we're working on to help showcase the top Blossom creators each week - https://blossom-mvps.netlify.app/
Before my trip to Japan, I received harsh comments on my post because I said that I didn't care about home ownership and cottages are a money pit. This hit a nerve with this person who felt the need to put me down. "Everyone here knows that you desperately want to be a homeowner. You are LYING to yourself and everyone on Blossom knows it except for you!" When I told him that he was being condescending, he doubled down, repeating stereotypes about renters. Insisting that I must be broke. He took my refusal to engage in a rent vs buy debate with him as proof that I was wrong. He concluded that since, by my own admission, the estate taxes are more favourable for homeowners than renters, I am hurting my son by being a renter. So... I'm a bad mother for renting? I often feel like a bad mom. When my son was a toddler, we'd ride the length of a TTC subway line because it entertained him enough for me to work on my master's thesis (I had no childcare) 😅. Last year, my son overheard me saying that I was happy to be working on Christmas for the overtime pay, prompting him to announce at the gathering I missed that 'Mama is working because she cares more about money than her own son'. Recently, my son and I were sharing a bowl of ramen noodles at the food court when an unhoused person, asked me to buy him a bowl. When I said 'Sorry, I don't have any money' my son sobbed loudly yelling 'Mama you are LYING, you have thousands of dollars in your bank account!'. It's better to fumble through awkward money conversation then to not have these discussions. The reason I don't value home ownership is related to my childhood experiences. For those interested in that story, I will share it in the pinned comments below. Long story short, I don't drive. The Canadian dream of living in a suburb is *my* definition of hell. Unsurprisingly, because of our childhood my sisters and I all live downtown. Furthermore, due to my neurodivergence, I don't want to deal with the drudgery of shovelling snow, lawn care and other home maintenance tasks. Being a women with ADHD, I carry a lot of shame for not living up to gendered homemaking expectations. By renting, I can pay to outsource these tasks. Walkable neighbourhoods are rare in Ottawa, a sprawling car dependent city. Unlike the suburbs where homeowners tend to be the majority, in Canadian downtown cores, this ratio is flipped. You aren't going to tell a vulnerable female commuter that works 12 hour shifts and walks home from work past midnight and before dawn with a flashlight 🔦 that I don't deserve to pay for an apartment rental in a SAFE area. We don't shame people for going out to restaurants, paying for dry cleaning, dog grooming, car repairs or literally any other service. While I don't value homeownership, doesn't mean that I will gaslight anyone who dreams to own their home. The same playbook that makes you a wealthy renter will also build your down payment. The average age of the first time homebuyer in Ontario is now 40 years old! It is dishonest to pretend that homeownership in metropolitan cities is a meritocracy. This is due to decades of policies pushing young families away from cities. Housing supply in North American cities have been artificially restricted due to exclusionary zoning. Not to mention the history of redlining were banks denied mortgages specifically to black and indigenous families. Don't compare yourself with folks who bought their homes 20 years ago, when it was affordable. Renting or buying, tougher choices are needed compared to those who got in earlier. Investing is the great equalizer since it's more accessible than homeownership. Both my husband and I had non-linear career paths, hence it took us longer to get established professionally. Since getting married, we have moved to 3 different cities in search of better career opportunities. My husband's career benefited from these moves leading to him having a much higher salary. While larger cities are more expensive, they also offer more opportunities for networking and carrer advancement. The real estate market is more efficient than people realize, the trade offs of having less opportunities and lower salaries in smaller towns are reflected in the lower housing costs. Why am I worried about retirement? I had to drop out of the workforce when my son couldn't adjust to daycare. The week my son was born we were sued by a collection agency for failure to repay my husband's student loans. Unfortunately, my husband is over a decade older than me so I was terrified we'd have nothing saved for his retirement. Had we bought a place we wouldn't have been able to navigate these financial hardships. Fortunately, because we were renting a one bedroom apartment in Toronto we could find a way to live on one income, although we couldn't save for retirement, we contributed to my son's RESP (529 plan equivalent). The pandemic allowed my husband to work remotely allowing us to relocate from Toronto to Ottawa (medium cost of living city) for my current job. Renting allowed us to be location flexible to pursue more lucrative career opportunities, resulting in us now earning over 200K/ year as a couple. We were pressured to buy a place once we moved to Ottawa, however the math did not make sense because we want to live downtown. The downtown condos built in the last 20 years are too small for families (due to condos being built for investors and not end users). The older condos are spacious and cheaper, however the condo fees can run up to $1300/month. When we looked into units in older buildings with a condo lawyer, we uncovered multiple lawsuits and issues due to decades of delayed maintenance. The Math Behind Why we Rent A 2 bedroom downtown condo in our area goes for 670,000 K. The unit would be tiny with a bad layout. The condo fees for the unit are $900/ month. If we were to buy this condo using 100K as a down payment, the mortgage would be 3,300 per month. Adding the monthly condo fees, taxes and insurance the costs to own are $4,800/month. Meanwhile the rent for our larger apartment is half the costs of owning! Our building has pool, a scenic view of the city and a dining room appropriately sized for a family! It's not an apple-to-apple comparison we don't have in-suite laundry, our laundry room is in the basement and we have shitty old appliances. However renting allows us to invest 3-4K per month AND afford family vacations. Looking at historical data, Ottawa downtown condos have appreciated at a rate of 2% per year above inflation. Meanwhile, in the four years we have lived in Ottawa we went from zero to over 300K invested! 🤯 How we make renting work: 1) Use All Tax Sheltered Investment Accounts for Investing The FHSA (in Canada) is the renters RRSP, lifetime contribution limit of 40K means that my husband and I will get 80K in extra in RRSP contribution room. 2) Screen Your Landlord Just as a prospective landlord will screen tenants, you should screen your landlord. Check how the property is maintained. Being forced to move is stressful and expensive. My family avoids this by renting from buildings owned by rental companies. I prefer the service from professional landlords with full-time staff and a 24 h super on call. Look up Google and reddit reviews for rental companies. Introduce yourself saying that you are a long-term tenant looking to stay 'X' years and ask your potential landlord about their intentions to sell the home etc. You can't predict the future, but you can make an informed decision. 3) Lean into Location Flexibility We rent to live in a walkable neighbourhood in the best school district for my son. In many urban areas it's cheaper to rent than own. This is because you can only charge what the market will bear. Obviously, your landlord didn't buy the property yesterday, they profit from their business. 4) Don't Rent More Space than you Need! Homeowners tend to get more space than needed while renters tend to only rent the space they need. Embrace this, bigger homes mean more money spent on utilities, furniture and junk you don't. Consider multi-unit housing to reduce costs via economies of scale. People overestimate how much a larger home will make them happier while underestimating how much a longer commute will make them miserable. 5) Invest more than the difference Just as a homeowner shouldn't ONLY rely on their home equity for retirement, renters should be investing MORE than the difference between the costs of owning vs renting to build up a sufficient nest egg. Psychologically, it is hard to have the discipline to save, homeowners benefit from the forced savings of a mortgage. Setting up auto deposit into your brokerage account helps! 6) Ignore The Haters Don't feel pressured to buy if you're not ready. Homeowners are also throwing money away on front-loaded interest, renovations, real estate transaction costs, land transfer taxes etc. 7) Evaluate What matters to You Money, like time, is a limited resource. Decide what matters to you and budget accordingly such that your spending aligns with your values. Be flexible as priorities change over time. Your unconventional financial journey is not failure but a story of resilience. Plot Twist Over the weekend my uncle, a Silicon Valley Tech CEO, visited us. His wife gave my sisters and I envelopes to open at the same time. My son saw my face change. 'What's wrong mama, you look sad. I guess you didn't like your card!' I was stunned to see a check with my name on it and a lot of zeros.. My sister whispered "Are you going to buy a house now?" "Nope " I replied. It will be invested. I will set aside enough for my husband to get the watch he wanted. I gave my son $500, which he promptly spent on a 5oz silver bar. After depositing the check my bank is calling us non-stop trying to sell mutual funds. They also informed our old mortgage broker. We are ignoring their calls.read more
The market is red, and I’ve been taking advantage of the opportunity to buy more $XEQT and $VDY 😂 I think I’ve officially maxed out how much I can purchase without leaving myself broke. I’m curious, who else is buying right now? Are you excited about the lower prices, feeling nervous about the market, or waiting to see how much further it drops? I know red days can be scary, but if you’re investing for the long term, they can also be opportunities. Blossom community, what’s your move? Are we buying, holding, or sitting this one out? 🌸 happy investing!
Alright Blossom fam! ❤️ Despite October being a VERY red month, I was genuinely happy to find myself at #2 on the NEW Rising Stars leaderboard, after being #1 last week?!! That's sooo fun!! My goal for 2026 was to have 40K in my TSFA form 25K. I reached it , then raised it to $50K, and now I'm pushing for $75K by year-end. I'm getting pretty close, and I wasn't anywhere near these numbers this time last year! What's even more meaningful is that this happened during one of the most challenging years I've had. I was laid off, relocated, moved back in with family, started a new job and now commute a significant distance every day. Yet I continued prioritizing investing, even through October's red market. I've put a good portion of my surplus paycheques towards buying the dip, and I think I've officially run out of money to keep doing that. 😭 But I also want to share why this community means so much to me. I know there are opportunities to network with people who've built significant wealth, and I enjoy learning from them too. But one of the biggest reasons I started posting more consistently on Blossom was to connect with people on a similar journey. The 9-to-5 employees, the people earning average salaries, supporting their families, navigating an expensive economy and making sacrifices while trying to build wealth. I don't always have the time to network offline or even see my friends as much as I'd like. Finding people with similar mindsets and financial goals here has been incredibly valuable. And it's not just about portfolio updates. I've had conversations with people who've become more confident investing because of something we've discussed. I've also encouraged friends and family to start investing and build portfolios I wish I had at their age. That's what I want Blossom to be about: sharing substance, learning from each other and helping more people feel confident building wealth. Thank you to everyone who engages with my posts and makes these conversations worthwhile. Whether you're at $1K, $25K, $50K or $500K, there's something we can all learn from each other. Now, let's get some green market days because this girl needs to rebuild her buying power!!!! 🎃💚 happy investing! read more
Happy Monday, Blossom! 🌸🗳️ I voted in today's municipal election, and I think this is an important conversation to have on a platform like this! Municipal elections are about choosing the people making decisions about housing development, roads, public transit, attracting businesses and jobs to our communities, and even school funding and resources that help shape the next generation. But what does this have to do with personal finance? The city we live in can influence our budget in so many ways. How much do we spend on housing? How far do we have to commute to work? Are there good job opportunities nearby? Can we afford to raise a family here? Do we have access to the services and infrastructure we need? All of these things can affect how much money we have left to save, invest and put towards our financial goals. Investing in ourselves also means investing in the communities we live in.The decisions made locally can shape our opportunities, our cost of living and the future we're trying to build. That's why I voted today. 🌸 Have you voted in your municipal elections? And what's one thing that makes a community a good place for you to build your future? happy investing! read more
We're celebrating Episode 25 of Financial KarMoe and Moe's birthday 🎂 (not 25! lol)! 🥳🎈 This episode, @karyungtom and Moe discuss common investing mistakes, covered call ETFs vs. broad-market investing, and why a high distribution doesn't necessarily mean higher returns (Shoutout to @scottsinvesting, @saini, @ian_s whose posts we reviewed). We also answer @griff79's question from Blossom about funding your TFSA for 2027, explore value investing during inflation, and debate whether long-term investors should actually hope for a market crash. To wrap things up, we get personal with birthday freebies, frugality, and Canada's tipping culture. Is it getting out of hand, especially when picking up takeout or a coffee? 😅 💬 What do you think? Has tipping culture in Canada gone too far? Let us know! https://www.youtube.com/watch?v=yBthz2Wmr2o
It's Halloween, and while everyone else is worried about ghosts, goblins, and things that go bump in the night, @karyungtom and I are more concerned about something REALLY scary... 👀 💀 BAD FINANCIAL DECISIONS! 💀 We're getting ready for Episode 27 of Financial KarMoe, and we're opening the floor to YOU! Got a burning question about investing, ETFs, $xeqt / $CAGE, retirement planning, taxes, the Smith Manoeuvre, leveraged investing, personal finance, or anything money-related? Maybe there's a financial myth haunting you, an investing strategy that sounds too good to be true, or a money question you've been too afraid to ask. Now's your chance! 🧛♂️ Drop your questions in the comments below, and Kar and I will pick some/all to tackle in our next episode. No question is too scary, no topic is off-limits, and no financial skeletons need to stay in the closet! 😂 🎃 Your mission: Give us your best financial TRICK or TREAT! Let's make Episode 27 a BOO-ming success! 👻😛read more
I borrowed $42,000 to invest in XEQT using a Wealthsimple Portfolio Line of Credit (PLOC) — and after about two and a half months, here's exactly how it's going. 📈💰 In this video, I share an update on my ongoing experiment with borrowing to invest, including my current XEQT portfolio value of $42,362, approximately $362 in total returns from price appreciation and dividends, and roughly $300 in accrued interest so far. After accounting for the interest I've paid, am I actually ahead? Well, sort of! I explain how I went from borrowing $35,000 to $42,000, how much more I could potentially borrow based on my linked investment accounts, and why I'm being cautious about taking on additional debt. I'll break down my monthly interest costs, how XEQT's dividends contribute to the overall return, and how I plan to manage this portfolio going forward. Another important part of this strategy is the potential tax benefit for Canadian investors. When borrowed money is used to invest in eligible income-producing investments, the interest may be tax-deductible if CRA requirements are met. Based on my family's tax situation, I estimate that the potential tax benefit could offset some of the borrowing costs. I'll explain how this factors into my calculations, while keeping in mind that tax treatment depends on individual circumstances. I also discuss why I chose a Wealthsimple Portfolio Line of Credit instead of a margin account, the built-in borrowing limits that help me manage risk, and what could happen if the stock market takes a significant downturn while the debt remains outstanding. This $42,000 XEQT investment is an ongoing experiment that I'll continue documenting here on Moementum Finance. I'll share the returns, dividends, interest costs, potential tax benefits, market downturns, and ultimately whether borrowing to invest was worth the risk over the long term, for me. 💬 For those of you who have borrowed to invest, what is your main holding (stock or ETF) purchased with your borrowed money? Let me know in the comments! ⚠️ DISCLAIMER: This video is for educational and entertainment purposes only and reflects my personal experience. It is not financial, investment, tax, or legal advice. Borrowing to invest involves significant risk, including the possibility of losing money while still owing the full amount borrowed. Investment returns are not guaranteed, and interest deductibility depends on CRA requirements and individual circumstances. Do your own research and consult qualified professionals before making financial decisions. https://youtu.be/kbCg0PAwSIEread more
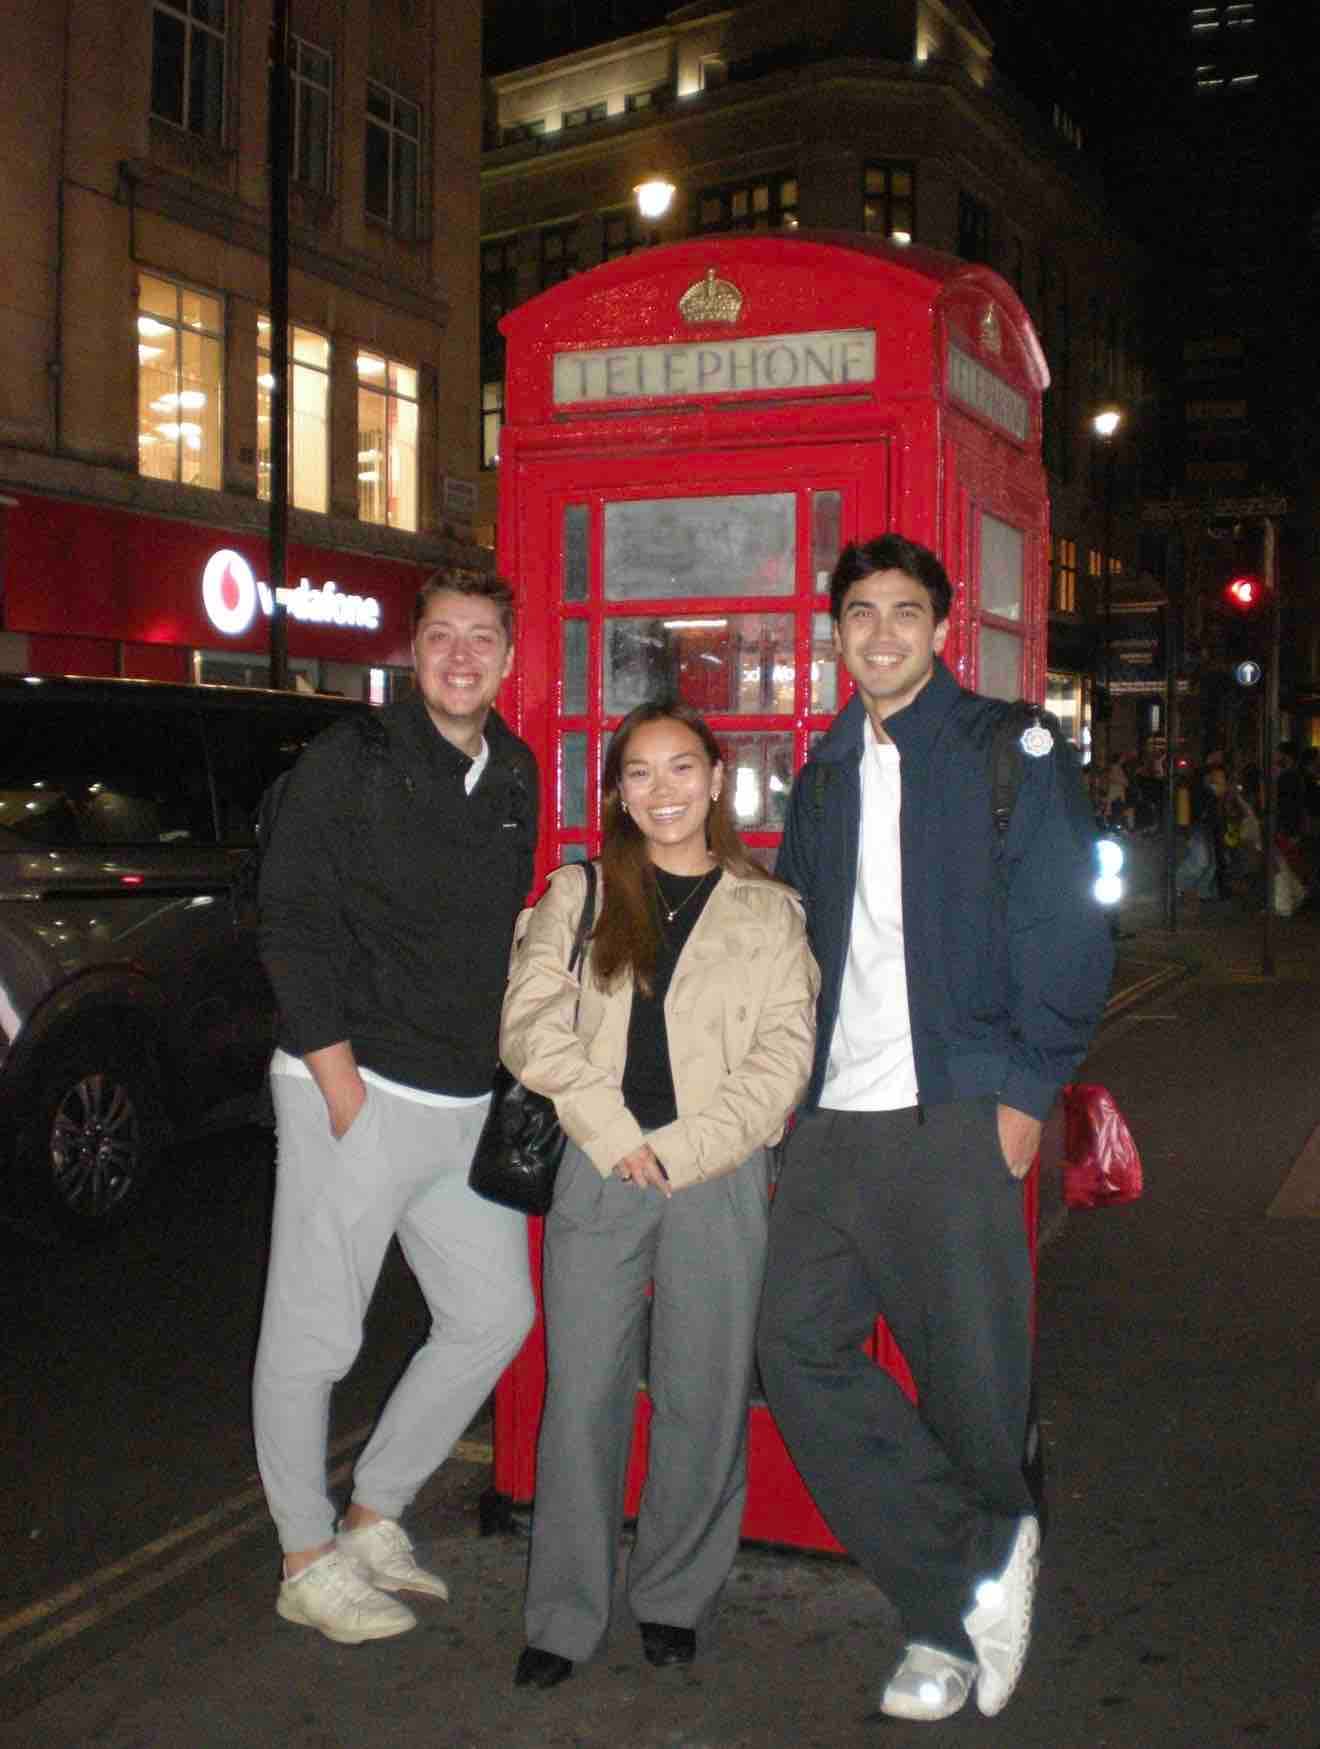
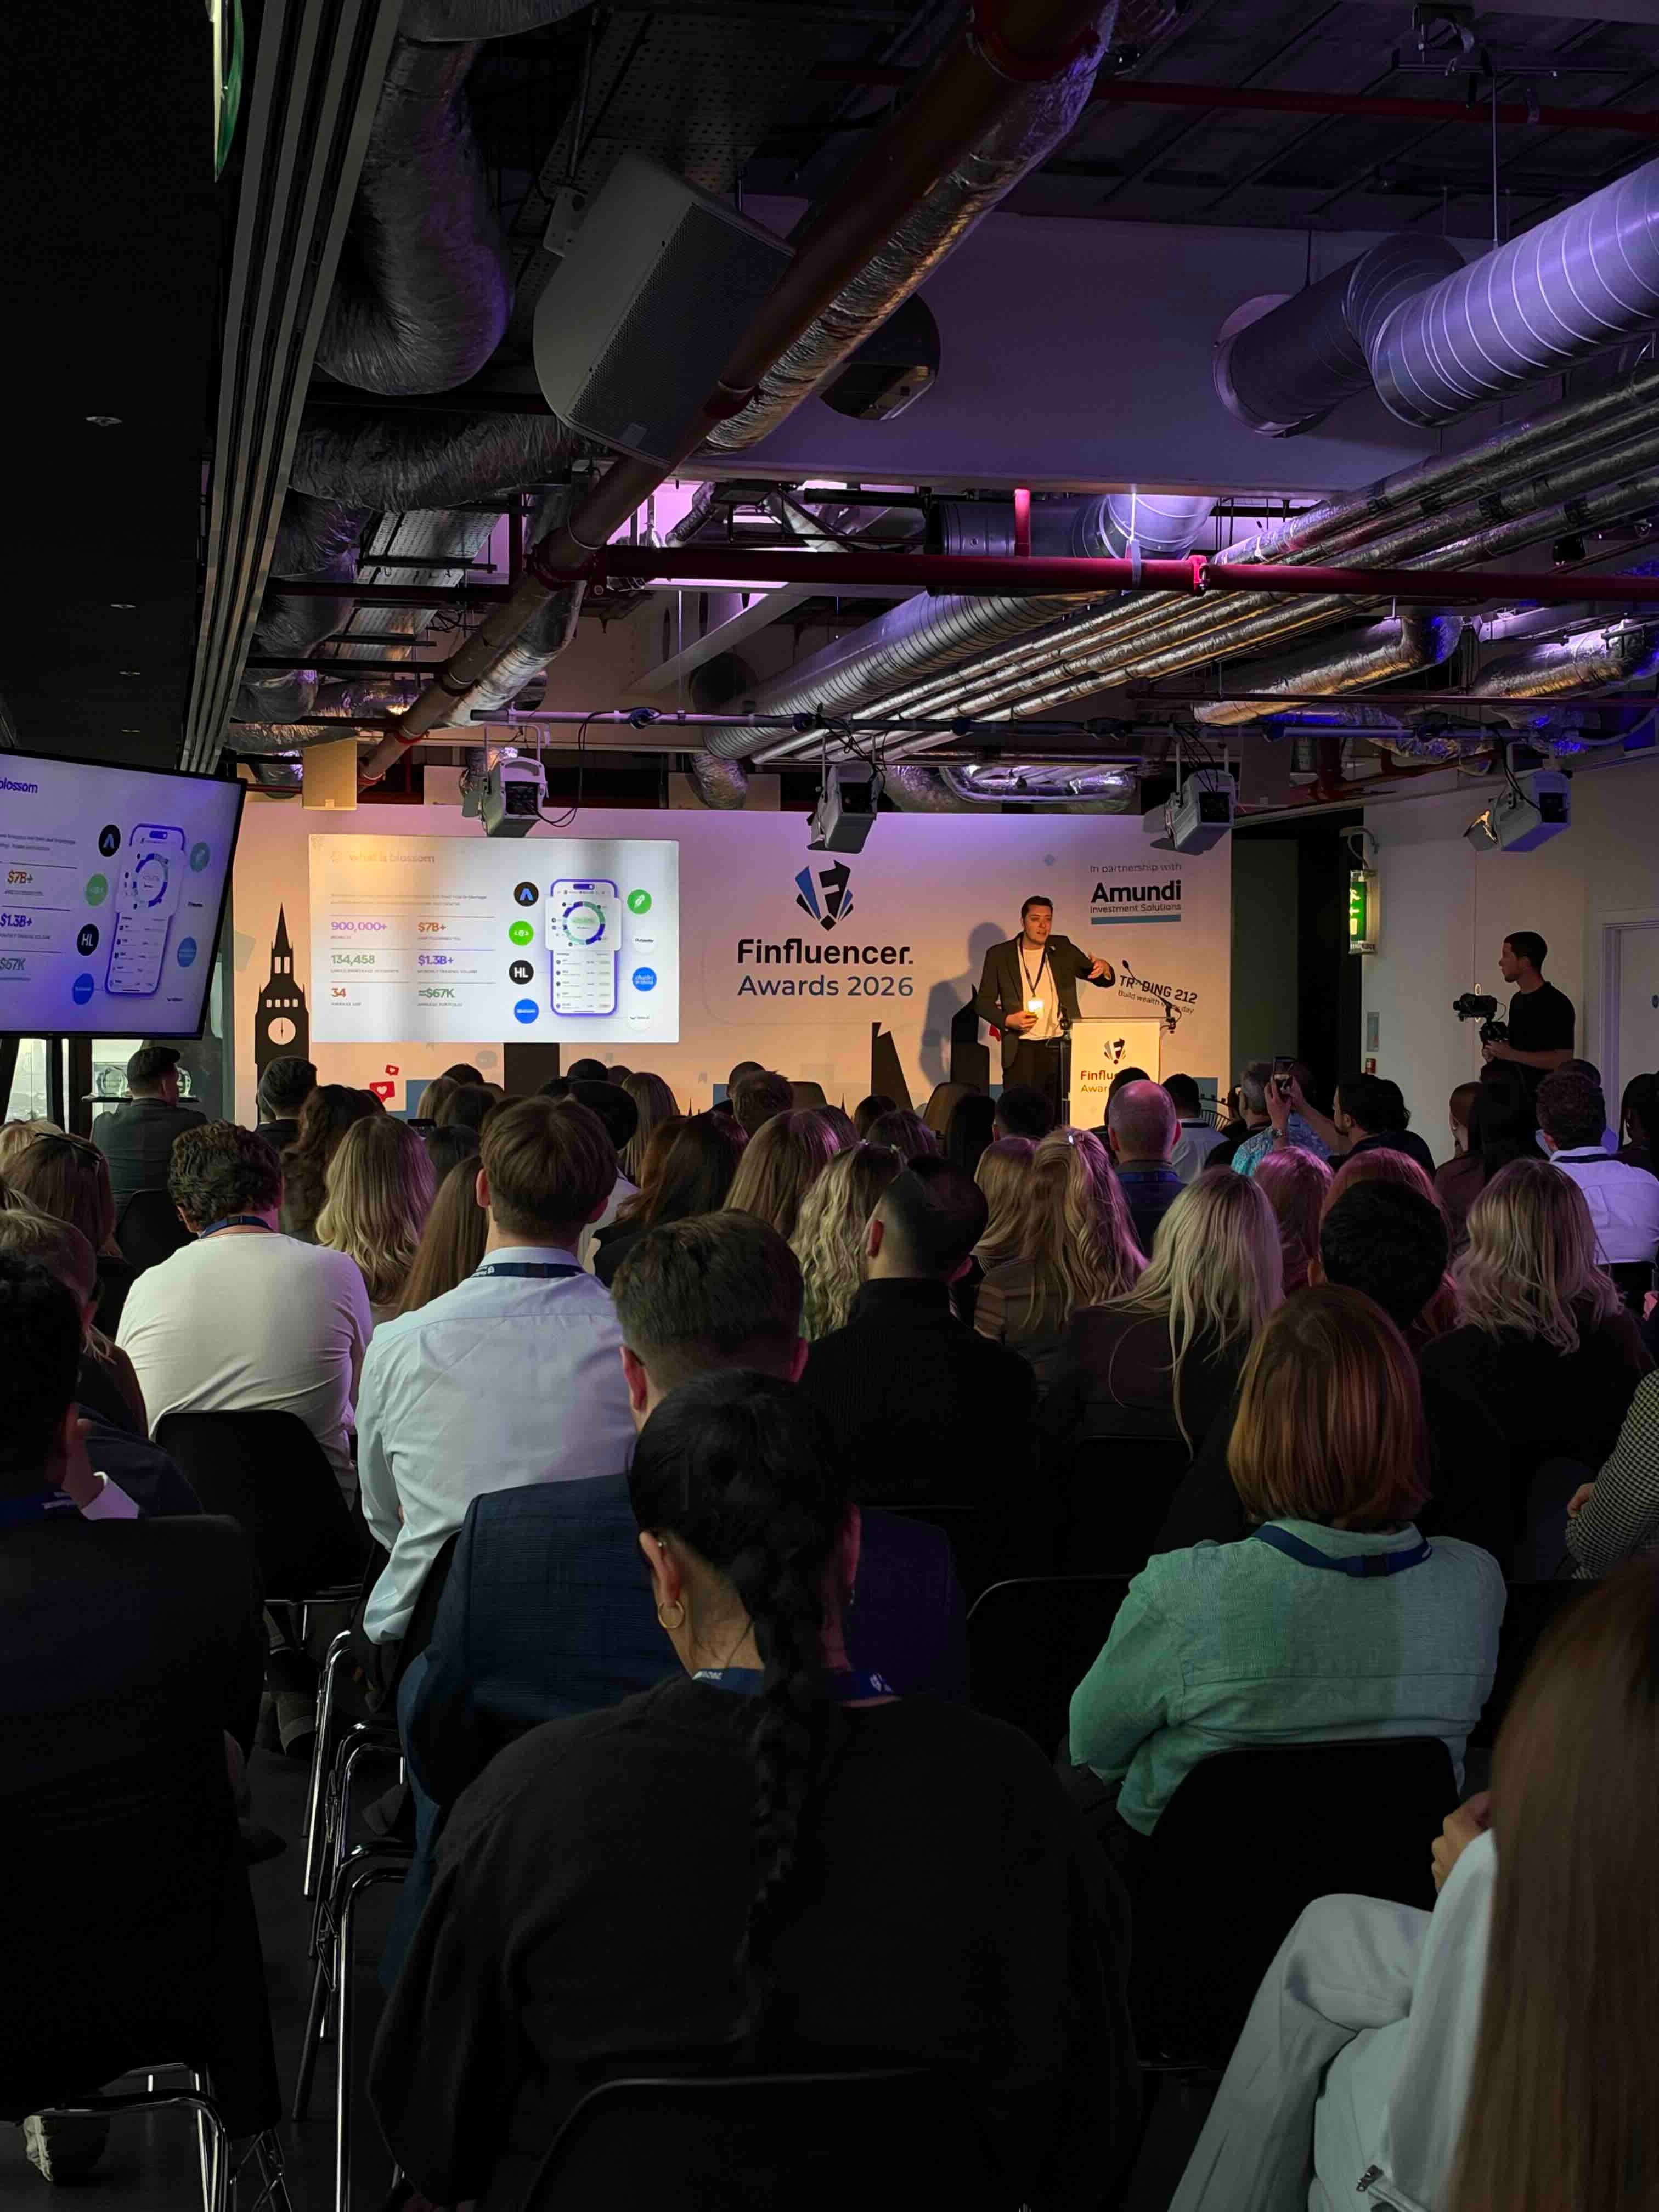
Just arrived home from a quick trip to London - it was my first time visiting. What a cool city. Full of friendly people. And so much character! Found it super interesting to learn that there’s still very much a ‘saving’ mentality in the UK. But that seems to be changing. Shoutout to Max for delivering an incredible speech (as usual) about Blossom. He presented our platform and mission in a great way and it was very well received by the Brits!
This November, we’re putting our money (and moustaches) where our mouths are. Team Blossom is officially joining the Movember movement, and inviting the entire community along for the ride! Our goal? Raise $10,000 for men’s health, supporting mental health and suicide prevention, prostate cancer, and testicular cancer. But we’re not stopping at donations! To make things a little more spicy, we’ve set up some fun fundraising challenges. From @maxstocks learning a KATSEYE dance, to mystery punishments, questionable moustaches, and a whole lot of chaos, every milestone unlocks something new. The best part? EVERYONE can participate (women too!). 🥸 GROW A MO: Put down the razor and grow that glorious moustache. 🏃♀️ MOVE FOR A MO: Can’t grow a moustache? No problem! Walk, run, or get moving for men’s health. Track your activity through Movember and sync your progress to your Mo Space. DONATE FOR A MO: Donate to a good cause and help us reach our $10,000 goal and unlock the next challenge! 📸 Post your progress photos throughout November and tag @meetblossomsocial on Instagram so we can share it along on our socials, bonus points if you're wearing Blossom merch! JOIN THE BLOSSOM MOVEMBER TEAM OR DONATE: https://movember.com/t/blossom-social-team?mc=1 Because investing in your future means investing in your health, too. Let’s grow something good. Together!read more
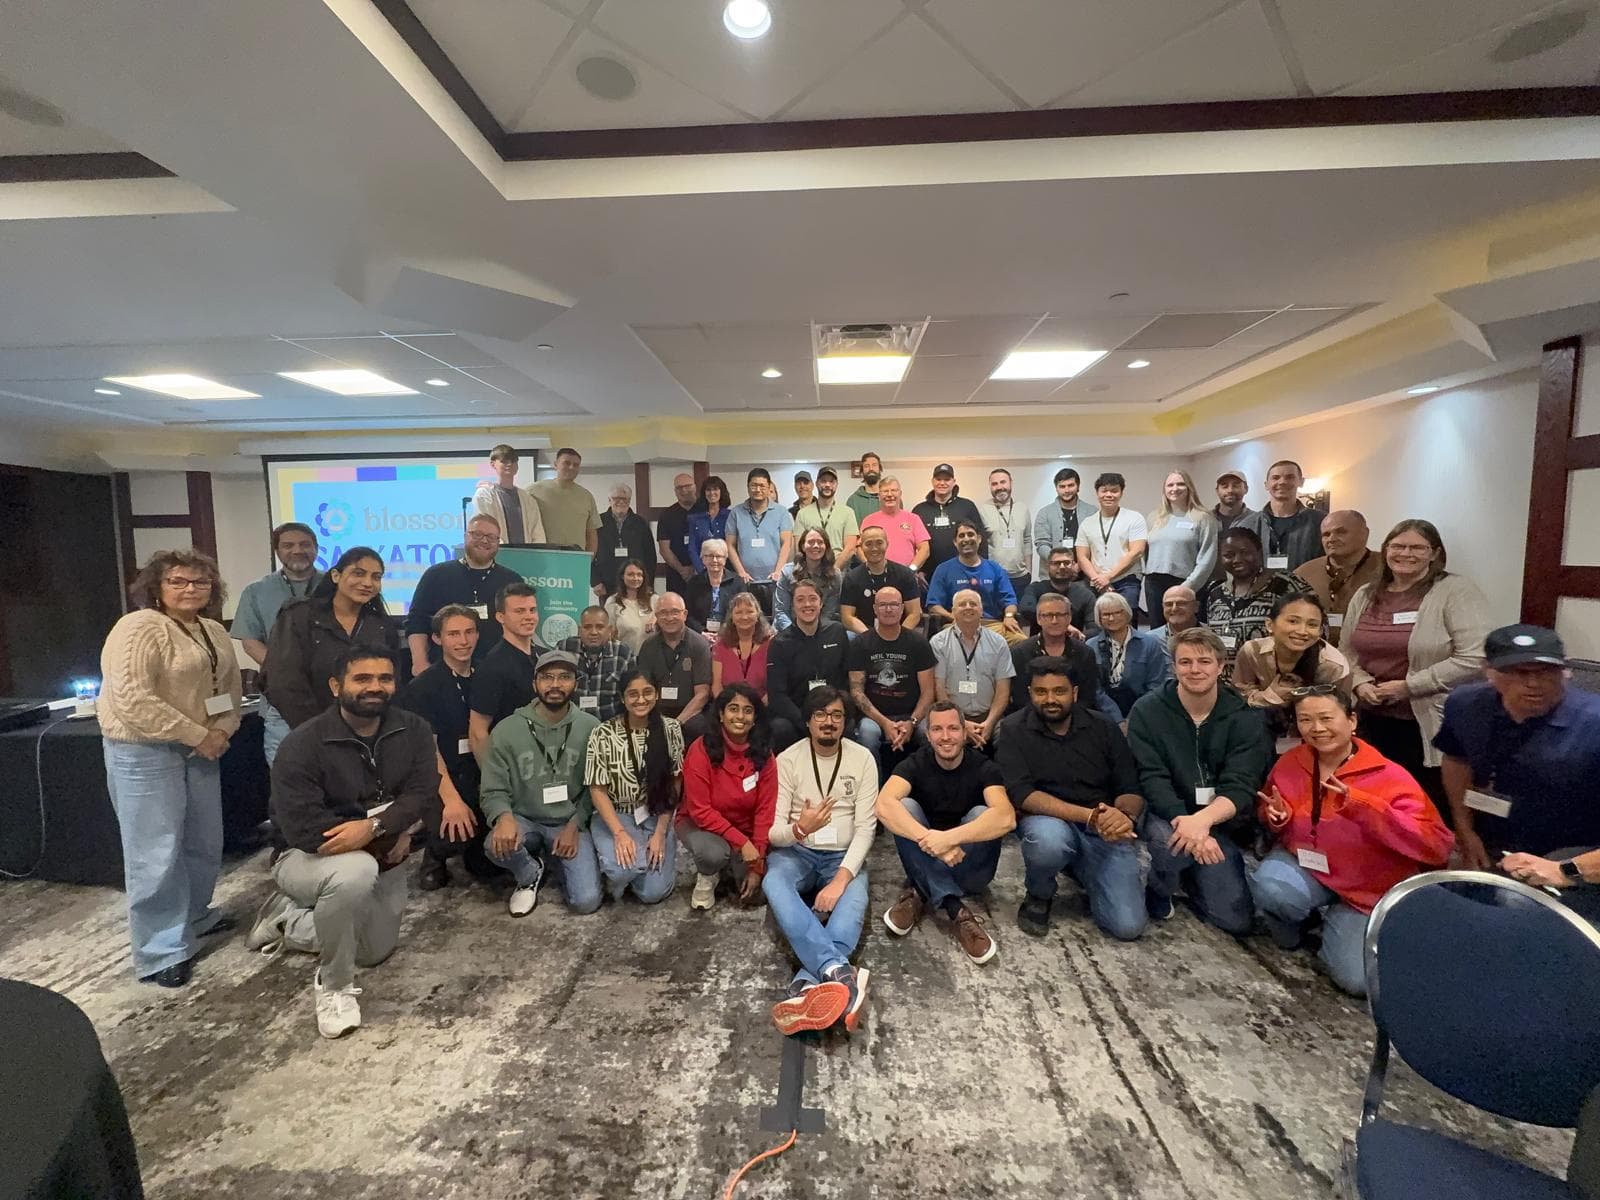
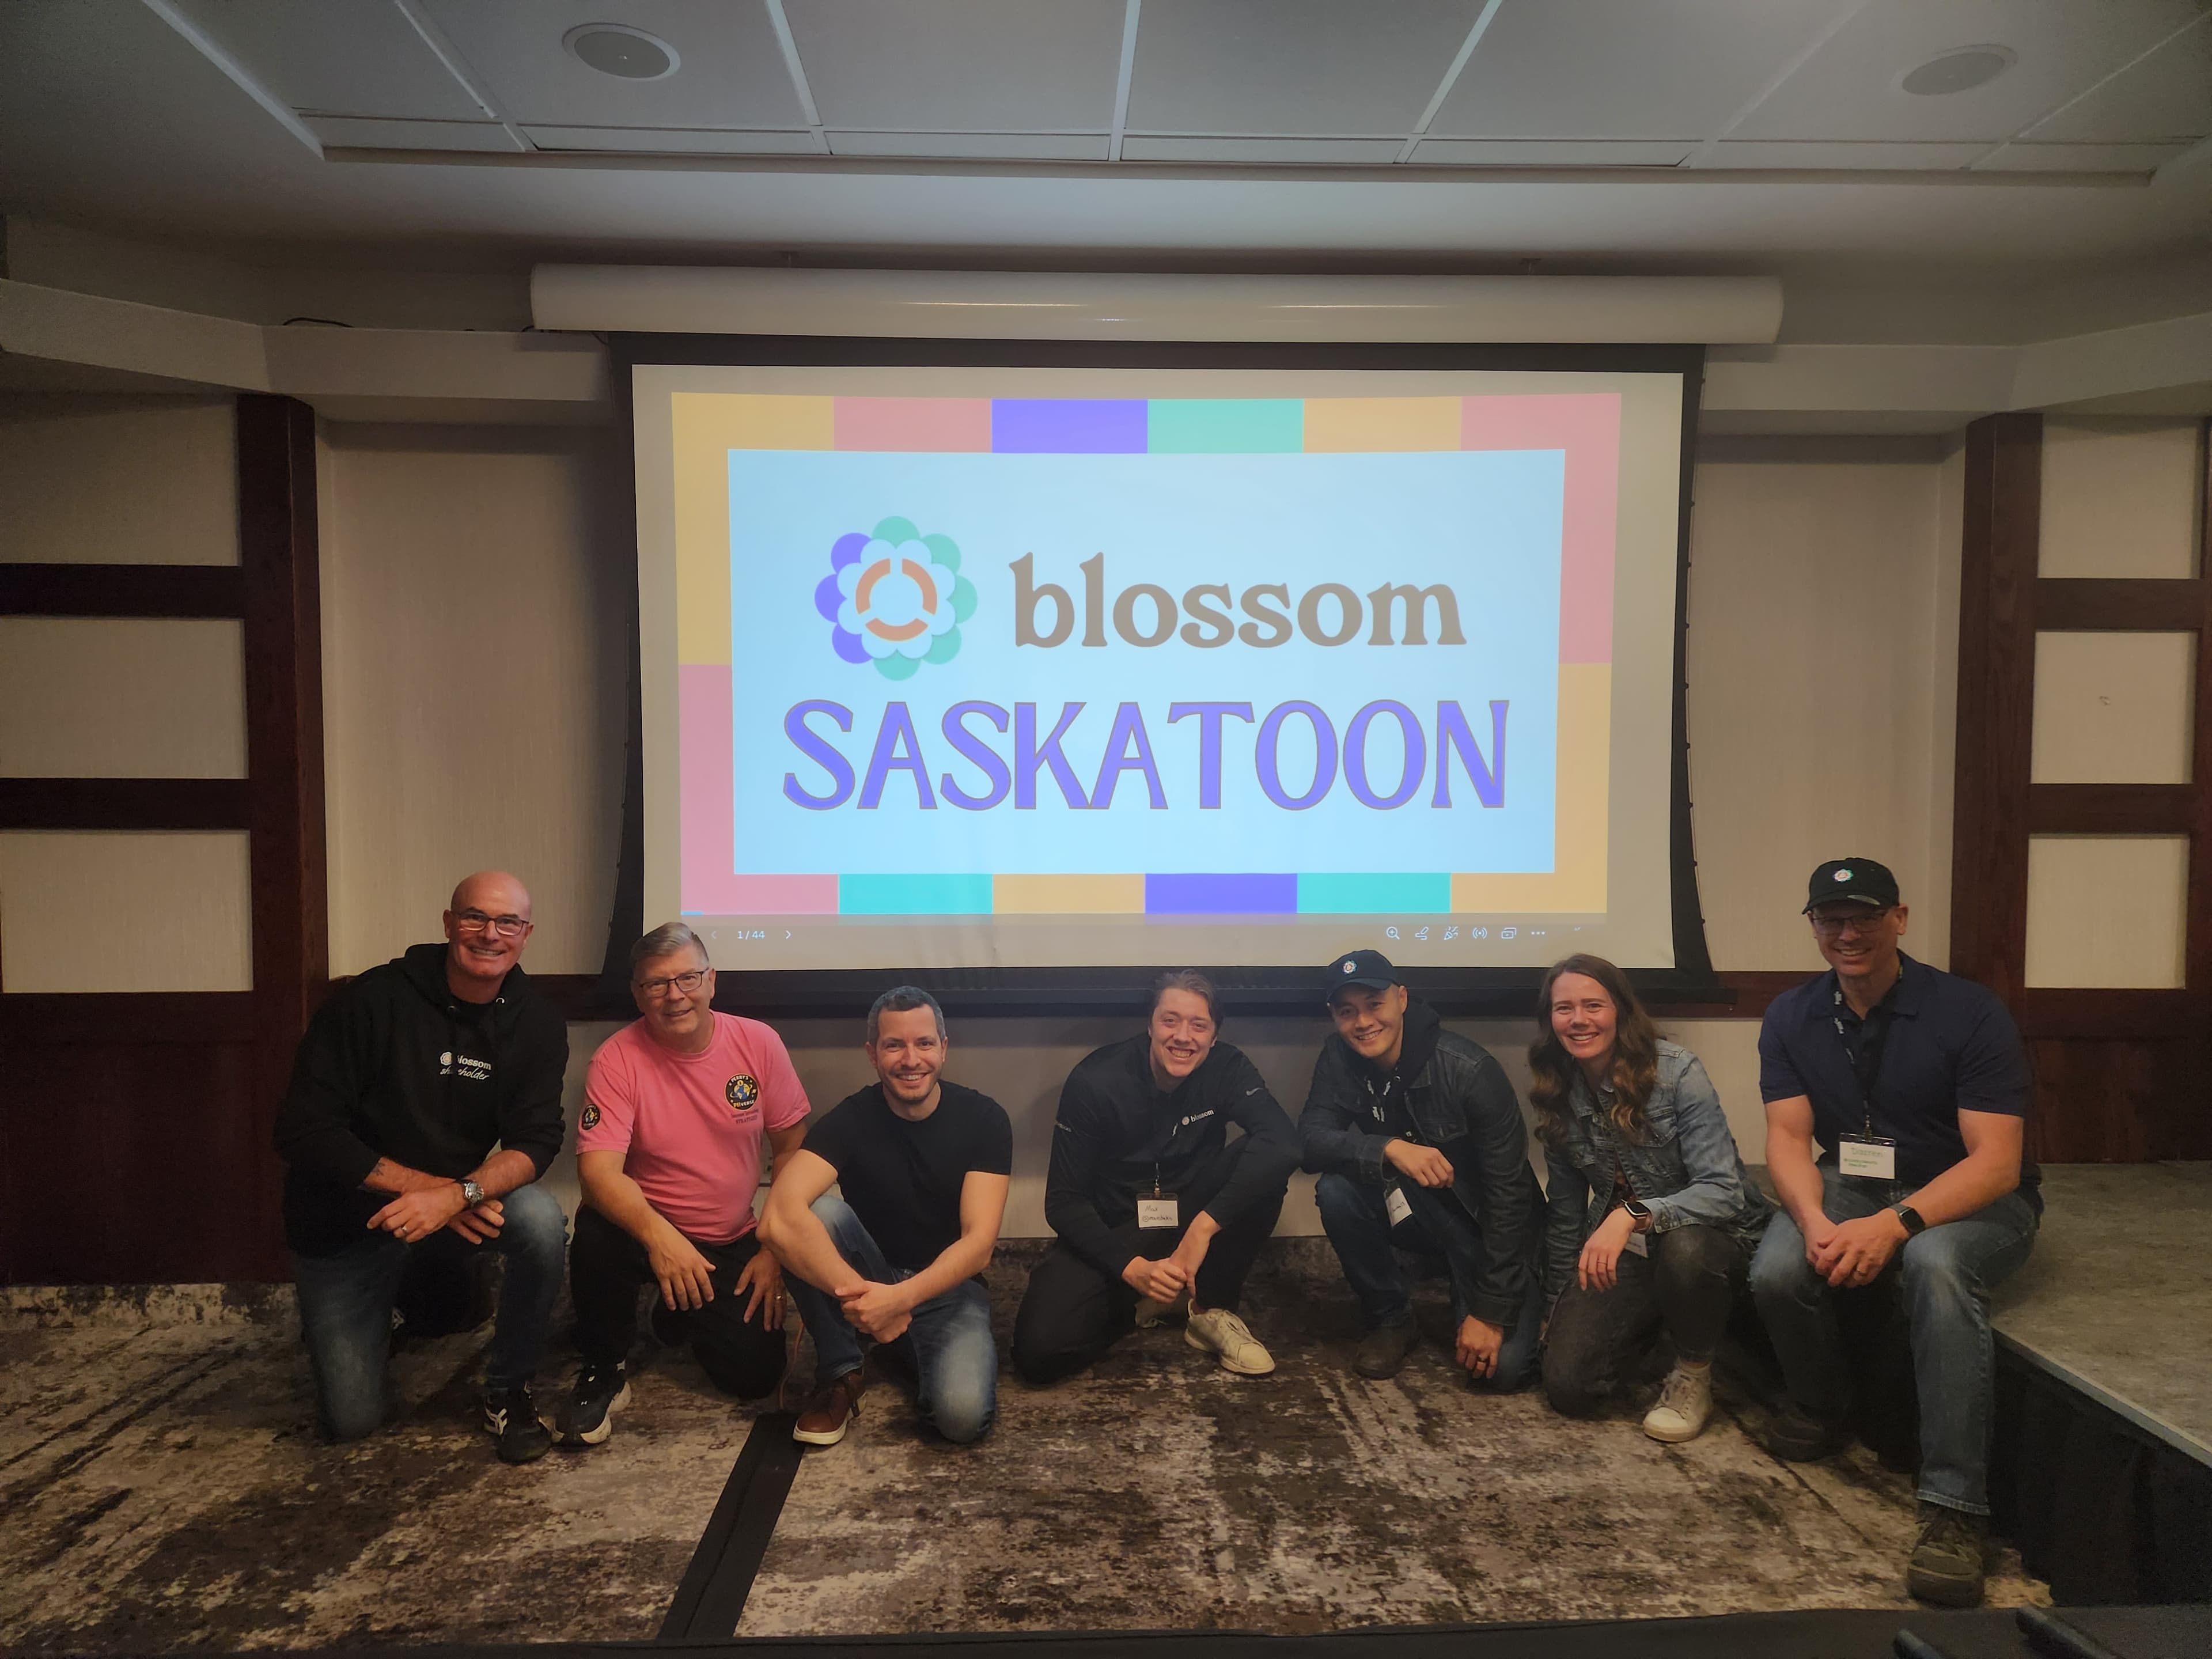
Yesterday was a good day, Saskatoon Blossom was a success, started off the morning by picking up @maxstocks , @canadiantshirt and @piiverse at the airport, then went out for lunch altogether with @crazycanuckinvestor , right after lunch we went to the venue and started setting up and putting together a few final things before doors opened at 2pm. Right after the doors opened there was a lineup of people outside waiting to come in, it was amazing to see investors gathering together to chat finance, nerd out and just enjoy each other's company. My wife @jesswang did an amazing job with the sideshows and all the background planning and helping with being the MC for the event. Thanks to Max for brining out merch to handout to people. We had two different panels, snacks, games that got people moving around, and then had pizza and Q and A to end the night. Everyone was so friendly and some people also decided to sign up on Blossom since they came with friends! After the event the main crew went out to a pub, had some drinks and food to unwind. The pub ended up turning into a mini club, and we were surrounded by young adults around us. We joked that we were the nerdiest table there but definitely the wealthiest as well. Good times yelling at each other over the loud music with great company. Maybe next year will do it all over again!
Has anyone else been getting spammed in their DM’s with similar messages to the pictures below? Not sure if there’s a bug here or something @blossom should look into further, but I have received 20+ similar messages over the past 2 weeks and am not sure why it’s happening. If I’m getting this many messages, I’m sure others are getting the same. Let me know!
this morning my wife daughter and I all finished our 8km race in the Victoria weekend event in under 1 hour. we all are happy. her bf doing the full marathon. crazy 17500 registrations... a record for the event.
Market volatility, shifting valuations, and a higher cost of capital make for some interesting investment decisions. Curious how others are positioning and where they’re putting new money to work. There’s a reason they say cash flow is king. Curious to hear your reasoning.
Good morning, a very happy Monday and happy Thanksgiving to all of the Canadian @blossom community 🇨🇦 I’m definitely thankful for relocating to this incredible country 21 years ago, for my amazing wife, my beautiful family and awesome friends and colleagues. I’m also thankful for market opportunities, and took advantage by picking up some more $NBIS$BE and $VRT this morning. I hope that each and every one of you are able to both appreciate and enjoy the things and people you are thankful for today. Happy investing 🫶🏽
I have been absent from posting and my channel. As you can see from the photo it has been for good reason. Yes we sold our house. But this sale gave me a big reality check. We all know how the real estate market is these days. We purchase in 2023, at what I would argue is the peak of recent sales. Now we are selling at the polar opposite of that. There are many personal reason for this sale, but the bottom line was that it had to happen. For to long many people including myself were not willing to talk about finances. Ironic now that I share it in Youtube. I think that talking about finances is healthy. Of course it’s not for everyone and I get it. To put this sale/loss into perspective, we lost nearly all of our market gains from the last 3 years. Yes you read that right. But there is a silver lining, which is the part that changes my outlook. The house be purchased is not far from our current house. It has a carriage house that my mom will move into. We went from a small Lot to almost half an acre which is what we wanted when we bought this house. The market is down for everyone. So while we took a loss on this house we purchased the new one for less than he bought our current house. My Mom is 76 and as some of you know is now a widower. She will be renting from us. So from a mortgage and cash flow perspective we are better off. For me I could not get my head around the loss we were going to take. Through this move we have done many things to save money. As you can see by the uhal. I am excited to get into the new house where I will now have my own space for my Youtube videos. For those that watch my channel the set up I had was done each video. So that was on top of research shooting and editing. So while I have been absent I have still been learning. Today it’s the Rational Reminder podcast EP 433 with Dave Chilton. What is your favorite podcast? Share with us. I am always looking for new things to watch and listen to. read more
⚠️ Warning: This post was vetted through AI. You may want to look away now. 😂 After experiencing the uninformed and unwelcome opinions of people shaming the use of AI, and, even more frustratingly, misrepresenting my financial situation, I decided to reread The Subtle Art of Not Giving a Fck*. It reminded me of something I already knew: Not every opinion deserves my attention. Fundamentally, I don’t participate in negativity, harassment or hate. I don’t need to convince everyone that my choices are right, and I certainly don’t need the approval of people who have decided they know my financial situation better than I do. But I did feel that the developing culture of AI shaming deserved my attention, not because I want to argue with the naysayers, but because I think there’s an opportunity to have a more positive, productive and inclusive conversation about it. I genuinely enjoy sharing my financial growth, milestones, lessons and journey here on Blossom. It’s one of the fun parts of this app for me. I’m excited about what I’m building, and I enjoy sharing the process with people who are interested in learning, growing and having conversations about money. And just to be clear: I don’t use AI because I’m illiterate, incapable or unintelligent. I was a professor in a dental department at a post-secondary institution. I know how to think, research, question information and form my own conclusions. Using AI doesn’t equal incompetence. It’s a tool. A tool that helps me organize my thoughts, be more productive, communicate ideas and accomplish my goals. And I actually think there’s something beautiful about that. Technology can make participation more accessible. It can help someone find the words they struggle to find, organize thoughts that feel overwhelming, communicate in a language they’re still learning, or simply make it possible to participate when life is busy. That feels more inclusive to me, not less. Of course, AI isn’t perfect. It can be wrong. It can misunderstand context. It can produce information that needs to be checked. That’s why I believe in using it responsibly: question it, fact-check it, protect your privacy and ultimately take responsibility for what you choose to publish. That isn’t giving up your intelligence. That’s using your intelligence to use a tool well. AI is here. It’s ubiquitous. And honestly, it has barely begun. We don’t shame calculators because people used to do long division. We don’t shame spreadsheets because people once balanced books by hand. So why are we suddenly treating the use of a new tool as a character flaw? Telling someone to stop using AI because it’s “not real” is about as logical as trading your laptop for a pen and paper, your smartphone for a corded home phone, and your GPS for a paper map. Technology changes. We adapt. And perhaps the most important part of all of this: The people who have reached out privately, with thoughtful messages, encouragement, curiosity and kindness, far outweigh the toxic noise. Those are the people I choose to give my energy to. AI isn’t going away. Neither am I. And I’m not going to spend my time arguing with people who are determined to misunderstand me. I’d rather keep learning, keep questioning, keep investing and keep moving forward. You don’t have to use AI. You don’t have to like AI. But you also don’t get to decide what tools someone else is allowed to use to build their life. And yes…AI helped me write this. 😉 I’m okay with that.read more
Midlife Changes Everything ❤️ In my 30s and early 40s, I put everyone else first. I prioritized my family’s needs, often at the expense of my own financial security. I thought being a good mother, partner, and person meant making sure everyone else was okay, even if I wasn’t building a secure future for myself. Eventually, I realized something had to change. I couldn’t keep neglecting my own needs and expect to create the life I wanted. So I started investing in myself, financially $XEQT, physically 💪🏻, mentally 🧠, and emotionally ❤️🩹. But here’s what I didn’t anticipate: when you’ve spent years putting everyone else first, the people closest to you may struggle when you start putting yourself on the list. Boundaries change. Expectations are challenged. Sometimes, the shift brings resistance from people who were comfortable with the old you. It’s hard, but midlife has a way of making you question what truly matters. Our bodies change. Our recovery, sleep, and health require more attention. Our children grow up, our parents age, careers evolve, and we become increasingly aware that our time is finite. Meanwhile, society has spent decades telling us what success should look like: a career, a home, possessions, and a retirement date. But we rarely talk about the cost of pursuing those things while neglecting our health, relationships, peace of mind, or financial independence. And money matters. Financial insecurity can limit our choices and weigh on our mental and physical well-being. Not everyone has the same opportunities, but where we can, building financial resilience gives us greater control over our future. So perhaps midlife is our invitation to reassess. ❤️ Financially: Build security and options, one decision at a time. 💪 Physically: Protect our strength, nutrition, sleep, and long-term health. 🧠 Mentally: Challenge old expectations, set boundaries, and stop measuring ourselves against everyone else. 🤍 Relationally: Nurture the people who bring meaning to our lives, without losing ourselves in the process. And remember to enjoy the present while preparing for the future. Because the goal isn’t to spend our entire lives accumulating wealth only to discover we’ve neglected the very things that make life worth living. Financial independence isn’t just about having money. It’s about having choices. The freedom to decide how we spend our days. The health to enjoy them. The relationships that give them meaning. And the peace of mind that comes from knowing we’re taking care of ourselves, too. I’m learning that choosing yourself isn’t selfish. You can love people deeply, support those you care about, and still protect your own future. You don’t have to wait until retirement to start living intentionally. And it’s never too late to change direction. We’re not just building wealth. We’re building a life we don’t need to escape from, with the freedom to enjoy it while we’re healthy enough to do so. ❤️ What has midlife taught you about what truly matters? read more
5,828 views
+4
What are you most comfortable owning and continuing to buy