I think Canadian beginners overcomplicate investing when realistically a few good ETFs can do the job. For a starter portfolio this would be a great starting point. $10,000(CAD) example 40% $XEQT — Global diversification ($4,000) 28% $VFV — S&P 500 growth ($2,800) 16% $VDY — Canadian dividends ($1,600) 10% $XEF — International stocks ($1,000) 6% $RY — Royal Bank or your own high-conviction stock ($600) I like XEQT as the foundation but I’d add more U.S. exposure for the growth potential and VDY for dividend income. Obviously there’s some overlap and risk with being 100% in stocks. But this is just my opinion and probably what I would do. Overall I think it’s a simple portfolio that gives beginners a solid starting point for long term investing. read more
What should investors know before buying covered-call ETFs? Is a high distribution yield really passive income, and how do you know if your investments are actually growing your wealth? In this episode of Moementum Finance, I'm joined by Zayla Saunders, Vice President of Online Distribution at BMO ETFs, to talk about her personal money journey, investing philosophy, and what she's learned from helping Canadians become more confident investors. Zayla shares how money wasn't openly discussed in her household growing up, how she went from financial planning and mutual funds to believing in broad-market index investing, and how reading "A Random Walk Down Wall Street" book helped change her perspective. We also discuss why she favours low-cost index ETFs, the importance of paying yourself first, and how keeping investing simple can help you build wealth over the long term. We dive into the growing popularity of covered-call ETFs and income investing, including the difference between distributions and total returns, return of capital, and why NAV erosion is real. Zayla also explains her work at BMO ETFs, how the team supports self-directed investors, and why understanding what's under the hood matters before buying an ETF. We also discuss ETF overlap, common investing mistakes, market timing, BMO's T-Series ETFs, and how Zayla approaches her own portfolio. She shares her perspective on financial independence, explaining why she values financial autonomy and the freedom to make your own choices. Plus, we talk about spotting red flags in online financial content, building better investing habits, and why you can still enjoy your money while working toward your financial goals. 💬 We'd love to hear from you: If you could go back and give your younger self one piece of money or investing advice, what would it be? Let me know in the comments! https://www.youtube.com/watch?v=hiUF2bQvs1Yread more
Google $GOOGL just had its worst day ever, erasing over $500B from its market cap. A penny stock losing 50% of its value is entirely normal… but a mega cap dropping -17.5% in less than one month??? That should raise some concern. Didn’t I tell you this would be the year of volatility? Remember when I asked you when was the last TIME you saw a company borrow so much, so fast… and then saw its stock do well in the near term? 🤔 Here’s the link in case you want to re-read it: https://www.blossomsocial.com/posts/Google-or-the-Government__POST-1787405080828-nDo2PppJ_qoQV3QbaHcPIAvML Are you focused on making a quick buck off the hype of whatever influencers you’re following… or on making the BIG bucks by following those who have experience and actually want to show you how to WIN? 🏆 It’s all about learning where the puck is going! Natural selection is alive and well. This is the Way! 🏄🌊 read more
When I was 16, I had saved about $5,000 from lifeguarding and doing odd jobs for neighbours, and I asked my parents if I could invest with their advisor. That money went into growth mutual funds, which wouldn't be my choice today. I'd use a low-cost index fund now. But watching that money grow between 16 and 20 made investing feel real to me. I'd worked for that money. Seeing it grow without picking up another shift made me want to put more in. Looking back, I'm glad I started, even though I'd choose a different fund today. I still had plenty to learn, but I was already building the habit of setting money aside and investing it. What was your first investment, and would you make the same choice now?
These aren’t rules, facts or anything definitive; just some of the many opinions I’ve built over nearly 30yrs of stock investing. Take em' or leave em', it's all good to me because they're accurate. 🤷♂️ Here goes, in no particular order. Far too many investors… … have a gambling mentality when it comes to investing. ... focus on where a stock once traded to determine 'fair value’. ... think their pain threshold for unrealized losses is far higher than reality. ... risk far too much for a potentially very small win. ... create a lot of bad habits during bull markets. ... fail to acknowledge mistakes, so they fail to learn from them. ... under-estimate how can be lost going all-in on high or no P/E growth. ... rely on 'wishful thinking' over an actual 'investment thesis'. ... ignore anything negative about their stocks due to confirmation bias. ... will jump into day trading and/or margin usage at worst possible times. ... make blindly 'buying the dip' they're primary investing strategy. ... consider bullish "what-ifs" , while ignoring bearish "what-ifs". … equate every bit of news as a catalyst, while it's just ‘business as usual’. .*. spend too much time on small positions & not enough on large positions. .*. fall prey to "how much lower can it go" thinking, and later learn A LOT! ... underestimate 'company specific risk' and invest too much in one stock. ... worry about how they rank against others instead of focusing on self. … don’t understand what ‘the market is forward looking’ truly means. ... fail to factor 'we don't know what we don't know' in investment thesis. ... confuse getting lucky with having a sound investment thesis. ... will eventually get kicked in the throat by an unexpected margin call. .*. own too many individual stocks complicating things for no reason. … don’t spend enough time trying to break their bullish investment thesis. … scream "manipulation", when wrong about their favorite stock. ... spend too much time on social media telling others their stocks are best. ... think 'time in the market' guarantees profits, which isn't true for stocks. ... fall for recency bias when projecting future returns. … think they know more about a stock/company, than they actually do. ... taking on more risk, in an effort to make up for recent losses. ... sell their winners early and hold their losers indefinitely. ... willingly pay high expenses on ETFs that don't deliver. .*. happily DCA to lower cost basis, but won't do it to raise cost basis. ... turn a blind eye to dilution from rampant share issuance. ... ignore importance of long-term diversification. ... assume any ETF or mutual fund is safer than a stock. .*. get caught up believing the hype of a highly speculative stock. ... don't bother researching balance sheet & other key metrics.. ... under-estimate what's needed to retire 'comfortably', incl. fire/coast fire. .*. over-estimate what's needed to retire 'comfortably' (opposite of above). ... are far too quick to give advice while being ill-equipped to do so. ... over-estimate their true returns by failing to offset deposits. ... get cocky during bull markets & ultimately lose years of gains because of it. I think I've shared something similar to this in the past, so if I'm being honest, not really sure why I'm sharing... As with most of my posts, it's likely driven by what I'm seeing in my Blossom feed. And full disclosure, I've been guilty of a few of these (.*.) myself. Maybe you're guilty of some too. ** Wanted or not, I'll add to this list as more come to mind. **read more
I dont delete post or comments. Im not always the most..... Rational person to argue. But I do acknowledge when im wrong, and leave it for people to see. My post on @thejoemoneyshow and trading $XEQT got deleted. Not by me. And maybe not even by Joe.
Using global indexes. this was a question on the @karyungtom@moementumfinance podcast. Unfortunately for us..... they couldnt do the math on the spot..... Unfortunately for them...... I have too much time on my hands. First of all. This is not a matter of if but a matter of when. Also, im pretty lazy so I will be using a 7% default for returns past already historical preformance. So far the tfsa has been around since 2009 and has a running total of $109,000 between 09 and 26. not gonna lie, Ai doing some heavy lifting and probable Bull Shpiting but! if you made contrabutions at the start of every year and held a global market equity similar to xeqt then switched it to $xeqt when it was avalible you would have $394,000 not im gonna have to again, make some stuff up. You see, we dont know what the later contribution limit will be for the tfsa. so we will say every 3 years they will increase the limit by $500 ( a slight pattern in the past contrabutions limits) In conclusion.... Starting in 2009 and maxing out all contrabution room and the potential later room i can expect we will be seeing alot more tfsa millionaires in the year 2038..... 29 years after the tfsa inception. read more
$9000 lost this week. Volitility is the price to play the game. Being 100% equity regardless if its indexes or not it still majorly Volitility. You cant escape it, I dont try to. Also holding money on the sides to take advantage of situations like this is a pretty suboptimal practice. With all that in mind the only thing I really have control over in times like this is how much popcorn 🍿 I will make when watching the market do its thing. So far im almost $13000 off my highs thats a pretty small price to pay all things considered. https://youtu.be/aqOGSi-xpWs?si=BcD5fIRxPQqecIc5
I've been really MIA on Blossom since the passing of my sister... It's given me a lot of time to reflect on things. I still enjoy everything about finance and check my portfolio often, but I really want to stress the importance of realizing why we are doing this. What is the end goal of all of this? Seeing a loved one go in their early 30s is difficult, and it's made me realize that the time we have on this planet is really, really short. I have come to the realization that staring at numbers and watching them grow isn't as important as spending some of that time with loved ones. I want to start taking the kiddos on more vacations, buy the van that the wife wants, and try to see my parents more. The key for me will still be to be responsible with my finances, but instead of waiting for that next portfolio goal, waiting for the kids to grow older, or waiting to retire... why not live now? The whole point of becoming wealthy is to USE THE WEALTH, not to stash more and more so we can become so rich that we never actually enjoy the short time we are given on Earth. When the drunk driver went head on with her Uber vehicle, I truly believe she had no clue, could've just been chilling on her phone in the back then dead the next second...goes to show our life could end at any second and we might not even realize it. This post isn't saying we shouldn't be financially responsible, but that we should also enjoy life today... Tell your loved ones you love them, and use your finances to better your life. Willread more
I spoke to a police officer today in the lower mainland who had a 300k down-payment for his house in Chilliwack, BC and his monthly mortgage payment is still $4500....thats 3 times my mortgage payment and we make roughly the same salary.... I literally don't know how folks out in Vancouver and Toronto do it? Unless someone has rich parents or living in tiny places... is everyone else just house poor?
If you didn't get a chance to read the first post.. I basically created a script that analyzed all NASDAQ 100 companies to identify which are currently in a Golden cross and which are facing a death cross and listed the top companies that have seen pull back since they made the cross to afterlife and those that are fresh in crossing and could still snap back to life. Here it is for your reference: https://link.blossomsocial.com/7uYa/wydjpekb And after that doom and gloom post now we will cover the top GOLDEN CROSS achievers. Without further ado the top 4 companies with the deepest Gold status: 1. $MRNA - Golden cross since Jan. ‘26 Yesterday: $222.76 50DMA: $180.72 200DMA: $85.67 Price vs. 200DMA: +160% 2. $CRWD - Golden cross since May ‘26 Yesterday: $261.15 50DMA: $239.05 200DMA: $166.57 Price vs. 200DMA: +56.8% 3. $PANW - Golden cross since May ‘26 Yesterday: $380.57 50DMA: $371.82 200DMA: $268.94 Price vs. 200DMA: +41.5% 4. $AMD - Golden cross since 2025 Yesterday: $566.42 50DMA: $547.58 200DMA: $409.08 Price vs. 200DMA: +38.5% Now PAUSE and read this next part with care please… Did you notice how close $PANW and $AMD were to their 50DMA yesterday? That’s a sign that stocks are pulling back to test the bottom support and what do you know today both actually broke below it. That is very important to understand that when a stock forms a strong Golden cross the 50DMA becomes the bottom support with no real upper resistance except previous highs. Let's take $AMD (an absolute ROCK SOLID company) as an example: Today it actually broke the 50 day support and closed at $504 which is -8% below that support level.. and as soon as that happens the stock finds a new lower major support level and upper resistance ceiling which has now become the 50DMA. So now the situation is no longer as exciting as it was because the pull back has been severe enough in the short-term to BREAK the upward trend… and now levels are stacked like this: 50DMA (New Resistance): $548 Today’s price: $504.8 A few lower support levels can be tested 200DMA (New Major Support): $409 Now for the stocks that made a recent cross into Golden territory and now seeing sky as the limit up if momentum holds, these are still healthy trend up despite the major market pullback and ONLY two companies made that cut: 1. $MAR - crossed into gold Oct. 19th Yesterday: $399.65 50DMA: $359.35 200DMA: $355.63 Price vs. 200DMA: +12.4% 2. $TRI - crossed into gold Sep. 18th Yesterday: $116.35 50DMA: $104.57 200DMA: $96.53 Price vs. 200DMA: +20.5% How do I generally use this information, well one way is using it to filter potential candidates for short-term PUT and CALL options... Another is using it as a consideration for entry timing after a stock has stayed in the gold for over 30 days or support an exit decision if it stays dead for 30 days. This is one of many technical analysis inputs I would use to make decisions on short-term swing trades running for a few months to maybe a year... if you are a hold-and-forget investor then you don't really need to worry much about all this... cause you’re not bothered by the short-term volatility and are planning to hold for years despite how a stock fluctuates up and down. This is educational and not financial advice, please DYORread more
Amazon tonight, and I'll be honest, this is the one I've been waiting on all week. It's the biggest position in my TFSA at 35%, so yeah, I have skin in this one. The Street wants about $1.96 to $2.01 a share on roughly $202B in revenue. Amazon guided sales between $197 and 202B, with operating income of $22.5 to 26.5B, up big from $17.4B last year. Here's the thing though. Consensus revenue is sitting right at the very top of the guide. So even a good number might not surprise anyone. Keep that in mind before you judge the headline. Don’t get fooled by the growth rate. It'll look like growth slowed down hard from last quarter's 20%. It didn't. Prime Day ran in June this year instead of July, so it landed in Q2. Amazon says growth would be about 400 basis points higher without that shift. Calendar noise. Ignore it. AWS is the whole print. Everything else is a side conversation. Last quarter AWS grew 36.7% to $42.2B, fastest pace in 18 quarters, with a 39.4% margin. The models have it around $45.4B this quarter, up about 37.5%. So the bar is simple. Hold near 37% and the story is alive and well. Slip into the low 30s and the stock gets sold, I don't care what the EPS says. Demand isn't the question here. There's a $496B backlog and capacity is basically sold out through 2027. This is a supply story. One more thing I always remind myself with Amazon. Read the operating income, not the EPS. The EPS bounces all over the place because of the Anthropic stake getting revalued. Last quarter that was $53.4B of other income. That's not the business. The business is the $22.5 to 26.5B operating income guide. Judge it on that. Then there's the spending, because there's always the spending. Roughly $220B in capex this year. Free cash flow is negative over the last twelve months and long term debt doubled to about $129B. Look at last night. Google spent big, printed negative cash flow, and got punished. Microsoft spent less than feared and got rewarded. Amazon has to show it belongs in the second group, not the first. Hold the capex line and hold AWS growth, and this print works. Raise the spending guide again and it'll get the Google treatment. The setup is actually interesting. The Street loves it, average target around $332, UBS just went to $348. But the stock trades at roughly 28 times forward earnings, which for Amazon is near a five year low. It has lagged its own earnings growth because everyone's worried about the spending. Options are pricing about a 7% move tonight, so buckle up either way, and Chris Camillo called Amazon his number one trade going into this print, so I'm not the only one watching closely. My drawdown line is at $229.76 and the stock is around $253, so the watchlist isn't the story tonight. The thesis is. Not financial advice. Just how I'm going into it.read more
Always trying to take a step back and look at the big picture and scan for opportunities… yesterday I ran an exercise across all 101 stocks in the Nasdaq 100 to see which ones are in a death cross and which are in a golden cross. (Python script did the heavy lifting using data) To explain how this works for those not familiar with the concept… this is a methodology to monitor average closing prices over the last 50 trading days and compares it with the average over the last 200 days. When the 50 day climbs above the 200 day, that's a golden cross, a sign short-term momentum has turned up. When it drops below, that's called a death cross and a is generally a bearish signal of a continued downward trend. So the script tracked the moving averages for all NASDAQ 100 stocks except for SPCX and HONA which were recently listed and don’t have 200 days of trading. Hope that intro got you excited to see the results of the research exercise… we will cover top death cross names and top golden cross names in 2 separate posts… starting with the doom and gloom. (Maybe PUT candidates for those who trade options? 🤔) First I’ll start with the 3 worst performing stocks that are in the deepest state of death cross meaning they are sitting at a significant gap below their 50 and 200 day averages. ☠️🪦⚰️ Since this script ran yesterday some negative momentum has continued and numbers might be even worse now. 1. $APP - Death cross since March Yesterday: $254.91 50DMA: $295.8 200DMA: $417.76 Price vs. 200DMA: -39% 2. $ALNY - death cross since Feb. Yesterday: $174 50DMA: $237.8 200DMA: $286.5 Price vs. 200DMA: -39.3% 3. $CRWV - death cross since Jul. 28th Yesterday: $60.74 50DMA: $80.15 200DMA: $91.52 Price vs. 200DMA: -33.6% Notable mention: $RKLB - death cross since Aug. 27th Yesterday: $59.1 50DMA: $64.59 200DMA: $80.02 Price vs. 200DMA: -26.1% This one was really disappointing for me one of my biggest holdings and I exited this week for a minor loss as I no longer hold the same levels of convection until more clarity on the Neutron launch progress is demonstrated… until then the re-rating catalyst I built my thesis around has lost its steam and will continue to monitor for signs of it snapping back to life before re-entry. NFLX, INTU, FER are all also in a death cross still spiraling downwards but still a little less severe. —— Now the next 3 companies just crossed into death spiral only this week and could still snap out of it if momentum shifts… these are ones to watch next week to see how they lean. 1. $GOOGL - as shocking as it sounds it flipped into death cross just yesterday Oct. 29 Yesterday: $283 50DMA: $340.29 200DMA: $340.94 Price vs. 200DMA: -16.8% 2. $BKNG - flipped into death cross Oct. 22 Yesterday: $150.43 50DMA: $172.5 200DMA: $177.13 Price vs. 200DMA: -15% 3. $AXON - flipped Oct 23 Yesterday: $438.05 50DMA: $467.17 200DMA: $479.84 Price vs. 200DMA: -8.7% There you have it folks a list of possible top candidates for continued decline… I’d say Google is the most likely to flip back into safe zone within coming weeks. My personal observation (and this is completely my POV not based on science) is that once a stock passes 30 days on a death cross or a golden cross trend the price performance will most likely continue on the same trajectory of decline or growth for months to follow… something major breaking or a major positive catalyst will be the thing to break the trend. In plain english if it stays dead 30 days it will most likely a falling knife and if it stays gold for 30 days it is most likely a rally upwards. Now are you interested in learning about the other side of the spectrum the companies with the ever exciting GOLDEN cross forming to show growing momentum and positive price performance ? I’ll be dropping it tomorrow, so I’d invite you to follow to keep track when it’s posted. Not financial advice, DYORread more
I have been thinking about how to make this easy and actionable for anyone interested to learn about options trading and I thought there is no better way to start than by demonstrating what an option would look like if written out like a real contract between two people. In the following posts of this series I’ll cover the more technical stuff in detail, but for now I’ll keep this post fun, simple and without too much jargon… Strip it down and an option is basically a deal between a buyer (buying a right) and a seller (selling an obligation). So let's write a hypothetical options contract out. Take your time to read it, because all the terms you’ll need are sitting inside the contract. (strike, premium, expiration, underlying) ———— Draft CALL Contract Theoretical (this is just for illustrative purposes to help you understand the concept): I, Moe the buyer of this call option contract, reserve the right, but not the obligation to buy 100 shares of ABCD (underlying) for $50 per share (Strike Price) valid until 21st January 2027. In exchange for this right I agree to pay a premium of $1.50 per share. I, Mr. Market the seller of this option contract am obligated to sell 100 shares of ABCD for a set price of $50 until 21st January 2027 if the buyer chooses to execute the terms of this contract. For this I will receive $1.50 per share in premium. End of contract. ———— Now some quick context and basics to help land this for you guys: 1. We have two types of options contracts CALLS (option to buy when price goes up) and PUTS (option to sell when a price goes down) 2. All options contracts for stocks and ETFs are for 100 shares (you don’t pay price of share you only pay for the premium per share in the example above that would be 100*$1.5 to own the right to purchase the stock at $50) 3. Every contract has a strike price at which the buyer can exercise the contract to buy or sell the shares 4. Every contract has an expiration date after which if the holder doesn’t exercise it expires worthless and the seller keeps the premium. This is post one in a six post series, feel free to drop questions or feedback in the comments below and I’ll answer everything. Hope this was easy to follow for anyone looking to explore options and there is a real option contract example in the image attached.read more
Alphabet reported tonight and the after hours reaction is ugly, down to around $295 at the low. Let me walk through what actually happened, because it's more mixed than the EPS headline suggests. EPS came in at $2.12 against a $3.02 consensus. That's a big miss on paper. But look under the hood. There was an $8.7B loss on equity securities in the quarter, which knocked about $0.55 a share off net income after tax. That's an investment mark, not the business breaking. Revenue was $127.6B, up 25%, but that was a narrow miss against a consensus closer to $128B, and the ad business was soft: Search came in at $63.35B against roughly $65B expected, YouTube missed too, and total ads were about $82B against $83.5B expected. Operating income of $40.6B also came in below the $43.2B some were modeling. I won't dress that up. The core ad engine had a softer quarter than expected. Cloud though, Cloud revenue surged 103% to $30.7B, well ahead of the $29.1B or so expected. It didn't just beat, it accelerated past last quarter's 82%. Operating income at Cloud went from $3.6B a year ago to $11.1B. Growth and profitability at the same time. That's the monetization proof everyone keeps asking for. The spending is the other half of the reaction. Capex hit $51.4B in the quarter, $132B year to date, and free cash flow went negative at minus $9.1B. Ironically the capex actually came in below the $55 to $56B some expected, but negative free cash flow is negative free cash flow, and the market is punishing it. Google is a core position for me, 25% of my TFSA, so I'm not writing this from the sidelines. My honest read: Cloud is carrying the thesis right now, ads had a soft quarter, and the cash flow picture is what the stock will trade on until it turns. All three things are true at once. Not financial advice. Just my read.read more
"Here's a data-point for you... Golf courses consume 200x more water than all of our datacenters. In fact, they consume more in two days than all of our datacenters combined." – Andy Jassy, CEO $AMZN$AMZN
🇨🇦 Your Wealth-Building Checklist 1. Open a TFSA. Invest in a globally diversified ETF and let time, compounding, and tax-free growth work for you. 2. Pay off high-interest debt. Stop interest from working against you. 3. Build an emergency fund. Keep it accessible and earning interest. 4. Know your numbers. Create a budget and track your net worth. 5. Pay yourself first. Save before you spend. 6. Live below your means. Set clear financial goals and give every dollar a purpose. You don’t need to be rich to build wealth. You need a plan, consistency, and time. *list is not exhaustive and in no particular order. In saying that I personally prioritize my Tfsa above all else. Personal finance is just that, personal haha. As always do your own research 😉read more
I don’t think debt is the enemy. I think not understanding how it works can be. Consider two women. At 29, one borrows $180,000 to buy an apartment building. Her tenants help pay the mortgage, and she gradually uses the income to acquire more properties. Twenty years later, those properties are paid off, generating income and giving her more financial freedom. The other woman borrows money, too. For a car, a wedding, and a lifestyle she wants to enjoy today. There’s nothing wrong with wanting those things. But the payments leave her with less money to save, invest, and build wealth over time. Same tool. Very different financial futures. This is what I find interesting about debt. It can help you build wealth, or it can consume the money you need to build it. Neither outcome is guaranteed. Property comes with risks, and borrowing magnifies both gains and losses. But understanding the difference between borrowing to acquire assets and borrowing to fund consumption can change how we make financial decisions. I think financial literacy is about more than learning to budget or pay off debt. It’s about understanding how money works so we can make choices that serve us in the long run. The goal isn’t to look wealthy. It’s to build wealth. And the more we learn, the better equipped we are to do that.read more
How does a 16-year-old build a six-figure stock portfolio? In this episode of the Retail Rundown Podcast, 16-year-old Charan from New Jersey shares how he went from a 7th grade stock market competition to running a six-figure portfolio, while building 240K+ followers on Instagram and a 30,000-member Discord community along the way. That journey has included some huge swings, including a nearly $100K win on $PENG options and a $60K options loss on $AAOI that completely changed how he sizes trades, takes profits, and cuts losses. Charan explains how he researches stocks using AI and social media, why he’s bullish on memory stocks like $SNDK and $MU, why he bought $NBIS after Michael Burry went short, and why he thinks dropping out of high school to day trade is a mistake https://youtu.be/ZZ_PetTNbBo?si=QSEmMhrjwRYQ9Alw
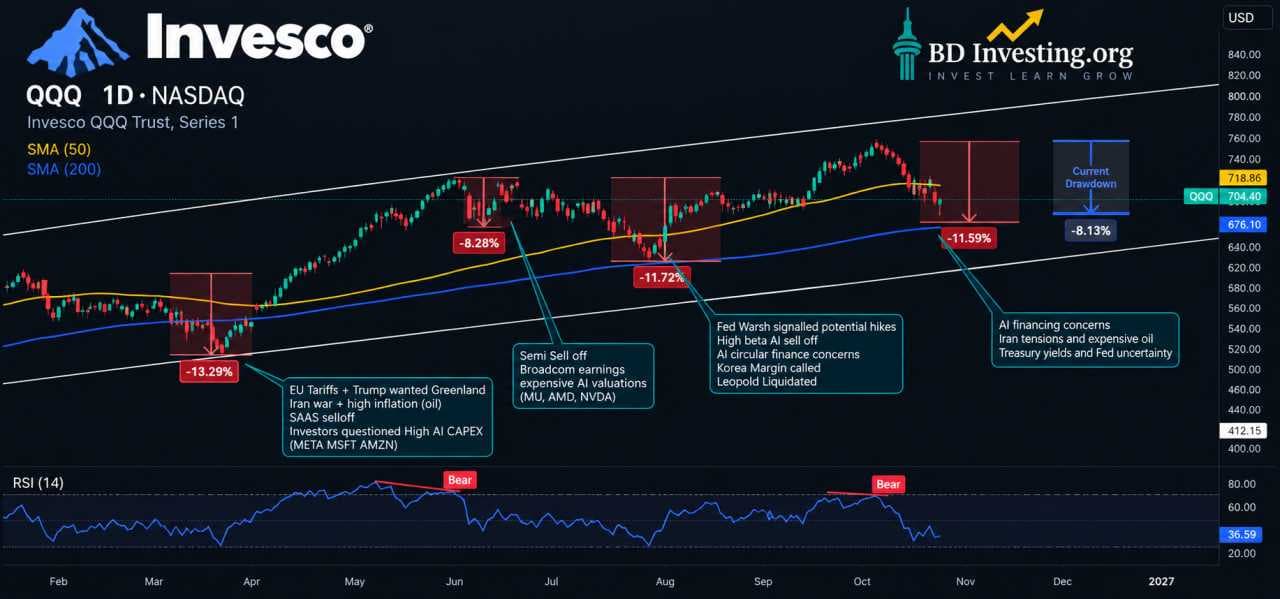
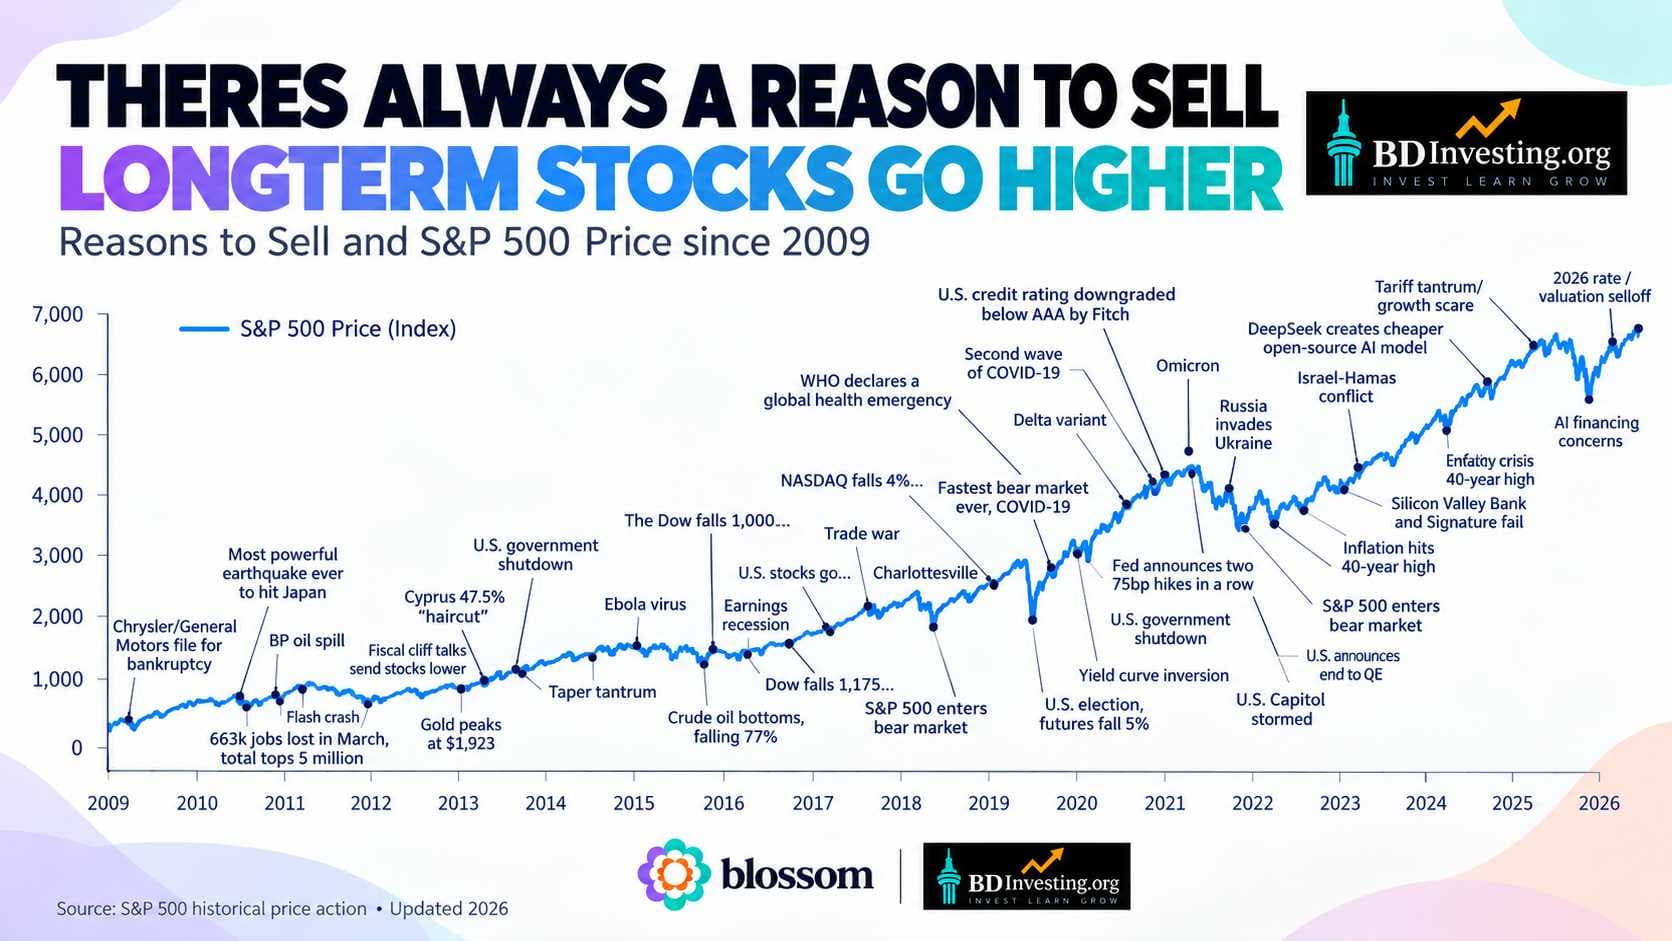
2026 has been an exhausting year for growth investors. Look at the $QQQ drawdowns this year: March: -13.29% June: -8.28% July/August: -11.72% October: -8.13% so far Notice a pattern? Almost every selloff has been driven by the same concerns. Expensive valuations, massive AI CAPEX spending, iran war ,inflation, interest rates and financing costs. Different headlines, same fears. What's frustrating is that many companies continue to report strong earnings and growth, yet their stocks keep getting punished. The fundamentals can improve while valuations compress. That's been the story of 2026. As investors remember this is the long game. Theres always a smart reason to sell, but stocks tend to go higher even with bad news. Buy the dip & HOLDread more
Following yesterday's post about my 150k milestone achieved, I got some very good questions about my investment schedule. So I wanted to make this quick post to bring some clarity and transparency about my contributions. Because I started investing late, I have to compensate with aggressive contributions to make up for the lost time (when you invest, time is your friend, but it is also your enemy!). Therefore, I invest consistently $250/week from my pocket. The money goes to FEQT or FINN to try and keep the target allocations I have defined. In addition, my business matches my contribution by 100%, and pays me a yearly dividend. So my total contribution is at least 35k/year. All goes to my RRSP for personal tax deductions. I also reinvest my tax return in my RRSP. My goal is to reach $1M invested by 2034 (when I'm 60). From there, the growth will start to compound nicely, so my contributions will no longer do the heavy lifting. 🚀read more
Another DCA going straight into $FEQT! Market up? Don’t care. Market down? Don’t care. Every Monday, same amount, same plan. No market timing, no second-guessing, no emotions. Just a simple, automated investing routine and a long-term mindset. The beauty of investing? It doesn’t have to be complicated to be effective. Consistency over timing. Discipline over emotions. Simplicity wins! 🚀read more